PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchStart by agreeing on what counts as a shared cost, then build a monthly plan from real take-home income and recent spending records. Choose a contribution method and payment setup that everyone understands, include irregular expenses and savings, and review the plan each month. There is no single split or account arrangement that suits every couple, roommate household, or other adults sharing a home.
1. Agree on what is shared before moving money
Talk through the arrangement before opening an account or transferring funds. Discuss each person’s income, existing obligations and debts, comfort with account access, and approach to spending. Then list which costs are genuinely for the household and which remain personal. The FDIC identifies communication and disclosure as important when people begin sharing expenses in its July 2022 guidance on sharing finances.
Shared costs might include rent or mortgage payments, utilities, groceries, and household supplies. Other costs—such as an individual’s debt payments, personal subscriptions, or expenses for dependents—should not automatically become joint obligations. Define edge cases in advance, including how to treat a guest’s costs, a room used differently by each person, or an expense that benefits one household member more than another.
2. Build a complete monthly picture
Start with take-home income and bills
Write down each person’s monthly take-home income, then list regular household costs, individual obligations, planned savings, and personal spending. Use bills, pay stubs, bank records, and receipts rather than relying on memory. Consumer.gov’s budget guidance recommends gathering income and expense information before making a plan.
Free tools Windows power users keep installed
One-click scans. No signup required.
#1 Best Overall

- Effective Budget Planning - Take control of your finances with the budget account book. This comprehensive planner allows you to plan and track your income, expenses, savings, and financial goals in one convenient place. With its intuitive layout and easy-to-use sections, you can stay organized and make informed decisions to achieve financial success.
- User-Friendly Layout - The budget planner features a user-friendly layout designed for easy navigation and organization. Each month, you'll find dedicated budget pages where you can set financial goals, track your income, and plan your expenses. Additional sections include debt trackers, savings goals, bill payment trackers, and more, making it simple to stay on top of your finances.
- Undated Monthly Calendar & Bonus Stickers - Featuring undated calendar each month, you'll have ample space to mark paydays, bills due, appointments, and important dates. Say goodbye to difficult writing spaces. Plus, we've included 3 cute sticker sheets that allow you to personalize your financial organizer and make budgeting more fun. Dates are not pre-printed and are completed by the user.
- Reliable and Convenient Design - Our monthly budget planner is designed for your convenience and built to last. The elastic band keeps everything securely in place, and the dual-sided pocket provides extra storage. Experience a budget planner that combines practicality and durability.
- Master Budgeting with Ease - Our financial planner includes a complete guidebook that provides valuable insights and instructions for optimal usage. From setting financial goals to tracking expenses, this guidebook offers step-by-step guidance and practical tips. Whether you're new to budgeting or an experienced user, this resource will help you make the most of your budget planner, empowering you to achieve financial success.
Use recent spending to find irregular costs
Review several months of account and card activity or receipts. Include costs that do not arrive every month, such as insurance, medical expenses, gifts, seasonal spending, family support, and travel. Create an irregular-cost category and make a monthly provision for expenses that come due less often. Also list emergency savings and other goals as planned contributions, not as whatever might be left at month’s end. The CFPB’s spending assessment guidance, modified December 12, 2024, recommends tracking spending to understand where money goes.
Add the categories and compare them with take-home income. Check whether the planned leftover is plausible against actual account balances; if it is not, revisit estimates or reduce planned spending before relying on money that may not be there.
Rank #2

- Effective Budget Planning - Take control of your finances with the budget account book. This comprehensive planner allows you to plan and track your income, expenses, savings, and financial goals in one convenient place. With its intuitive layout and easy-to-use sections, you can stay organized and make informed decisions to achieve financial success.
- User-Friendly Layout - The budget planner features a user-friendly layout designed for easy navigation and organization. Each month, you'll find dedicated budget pages where you can set financial goals, track your income, and plan your expenses. Additional sections include debt trackers, savings goals, bill payment trackers, and more, making it simple to stay on top of your finances.
- Undated Monthly Calendar & Bonus Stickers - Featuring undated calendar each month, you'll have ample space to mark paydays, bills due, appointments, and important dates. Say goodbye to difficult writing spaces. Plus, we've included 3 cute sticker sheets that allow you to personalize your financial organizer and make budgeting more fun. Dates are not pre-printed and are completed by the user.
- Reliable and Convenient Design - Our monthly budget planner is designed for your convenience and built to last. The elastic band keeps everything securely in place, and the dual-sided pocket provides extra storage. Experience a budget planner that combines practicality and durability.
- Master Budgeting with Ease - Our financial planner includes a complete guidebook that provides valuable insights and instructions for optimal usage. From setting financial goals to tracking expenses, this guidebook offers step-by-step guidance and practical tips. Whether you're new to budgeting or an experienced user, this resource will help you make the most of your budget planner, empowering you to achieve financial success.
3. Choose a way to divide shared costs
Compare the options on predictability, perceived fairness, administrative work, privacy and account access, resilience if income changes, and how easily the arrangement can be revised or ended. No cited government guidance establishes one universally fair formula.
| Approach | Useful when | Tradeoff to discuss |
|---|---|---|
| Equal split | Everyone agrees that an even division fits the household’s circumstances. | The same dollar amount can represent very different shares of each person’s available income. |
| Income-proportional contributions | Incomes differ and the household wants contributions to reflect each person’s share of combined income. | Agree which income measure to use and revisit the ratio when earnings change. The FDIC gives 60/40 as an illustration when one person earns 60% of combined income; it is an example, not a fairness rule. |
| Assigned bills | Bills are easy to allocate and people want to keep accounts separate. | Bill amounts can vary, making one person’s share uneven unless you periodically balance contributions. |
| Shared-expense account | The household wants a common pool for shared costs while retaining separate personal spending. | Account owners may have broad transaction rights. Review the account contract, access implications, and applicable protections before depositing money. |
| Fully pooled finances | Everyone knowingly wants to combine income and spending. | There is less individual separation; discuss debt, ownership, and how a person could exit or revise the arrangement before pooling funds. |
The FDIC describes bill assignment and income-based sharing in its sharing-finances guidance. The Financial Consumer Agency of Canada’s October 10, 2025 guidance discusses account patterns and recommends deciding contribution amounts and transfer frequency together.
Rank #3
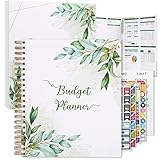
- Keep Track of Your Finances: Manage your personal and family’s finances with this monthly budget planner! Intuitive, comprehensive and fun, this budgeting planner allows you to keep track of your debts, expenses and bills, organize your spending and saving and optimize your budget for achieving your financial goals!
- Large Budgeting Planner: Our budget notebook features a large design of 8.5 x 11-inch that provides enough space for budgeting, financial planning and spending tracking but also for monthly reviews and building strategies for optimizing your budget!
- Well-Organized for Your Convenience: This budget book planner features an easy yet efficient template that includes a monthly budget with customizable categories, a debt tracker, a bill tracker, an expenses tracker as well as a section for financial goals and monthly review that will make things easier when it comes to budget planning!
- 12-Month Budget Management: Our budgeting book features a spiral-bound hardcover design made with high-quality 120gm thick paper and a 12-month undated design that allows you to start budget planning at any time of the year!
- Chic, Practical, Giftable: Featuring a superb boho cover and packed in a matching gift box, this budget book journal makes a lovely gift for a friend, family member or co-worker! The budget journal includes a special pocket for bills, receipts or other documents and comes with 5 stickers that will make your planning more fun and effective!
4. Write down the contribution agreement
Once you choose a method, put the working rules in writing so everyone can check the same plan. Specify:
- Which expenses count as shared and which remain personal.
- How contributions are calculated and when they are transferred.
- Who pays each bill and where receipts or payment records are kept.
- How variable bills, overspending, reimbursements, and unplanned costs are settled.
- When the contribution formula will be reviewed, including after a change in income, employment, household membership, or spending.
A short written agreement is a practical record of expectations, not a substitute for understanding any account contract or legal obligations that apply where you live.
Rank #4
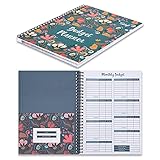
- Customize & Get Budgeted - With blank free of pre-filled categories and months budgeting pages, Soligt undated budget planner gives you complete control of your finances on a daily monthly and annual basis and enable you to manage your personal finance, cash money payment, and budgeting effective without any restrictions.
- Keep you on Track & Organized - The budget book journal provides 12 cute pockets for effortless bill, receipt, envelopes storage, along with a spacious layout perfect for recording and tracking incomes, expenses, savings, debt payoff, bills calendar and paying with ease.
- Achieve Financial Goals - This bill organizer provides a simple yet comprehensive budgeting system that is perfect for home household or small business beginners and encourages celebrating successes while identifying opportunities for improvement, both visually appealing and user-friendly.
- Your perfect companion - The Spiral bound budgeting notebook is the perfect small size, measuring at 9.25 x 6.81" and featuring a durable hardcover and 100 gsm paper. Lightweight and portable, It is easy to take with you wherever you go and built to last throughout the year.
- Bonus Month Tabs - The paycheck Budget Planner Financial Organizer boasts colored sticker labels to aid in simple navigation through your budget pages, ensuring added convenience and ease of use to help locate important information quickly and efficiently.
5. Choose how to hold and pay the money
Common setups range from fully separate accounts with reimbursements, to personal accounts plus a shared-expense account, to fully pooled income and spending. Choose based on privacy, administrative effort, and how much access each person is comfortable granting. Agree on transfer timing, bill responsibility, recordkeeping, and a process for settling reimbursements.
For a U.S. FDIC-insured joint deposit account, the FDIC says co-owners have equal transaction and withdrawal rights, including the ability to withdraw funds independently. Before opening one, confirm the account’s terms and current insurance rules with the bank and the FDIC; do not assume that a shared account is merely a convenient bill-paying tool with restricted access.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Best Value

- Effective Budget Plan Book – Take control of your finances with the SUNEE budget account book. This all-in-one budget planner allows you to plan and track your income, expenses, savings, and financial goals. Its intuitive layout and easy-to-use sections help you stay organized and make smart decisions to reach financial success. Our financial planner also included a comprehensive guidebook with valuable tips and instructions to help you get the most out of your budgeting planner.
- Full-Page Calendars – Each month’s full-page calendar provides plenty of space to track paydays, bills due dates, appointments, and important events. No more cramped boxes or tight writing areas, you can easily plan and organize your schedule at a glance.
- Colorful Pages Layout and Tabs – This vibrant budget planner features a user-friendly design for easy navigation and organization. Each month includes dedicated budget pages to set financial goals, track income, and plan expenses. Additional sections like debt trackers, savings goals, and bill payment trackers make managing your finances a breeze. The colorful backgrounds on each page offer clear, instant visibility.
- Bonus 4 Stickers and Convenient Design – This monthly budget planner is built for convenience and durability. Water-resistant cover protects against spills, while the elastic band keeps everything secure, and the dual-sided pocket offers extra storage. Plus, we’ve included 4 adorable sticker sheets to personalize your planner and make budgeting more enjoyable. Experience a budget planner that combines practicality with lasting quality.
- UNDATED DESIGN & 1 YEAR USE - Undated finance books start with 1 page-financial goals, 1 page-Mind Map, 1 page-Financial Strategy, 1 page-Tactics, 2 pages-Important Dates, 4 pages-Bill Tracker, 4 pages-Saving Tracker, 8 pages-Debt Tracker, followed by 12 Months(10 pages per month, 1 unique color for each month). 2 pages-Christmas Budgeting, 2 pages-Yearly Summary, 2 pages-Check Register and 12 pages-Notes(dotted). It is UNDATED, so you could start at any time, suitable for 1 year use.
Account and legal consequences vary by location and arrangement. The Canadian agency notes that legal implications, taxes, and treatment of property can vary by relationship and jurisdiction. If you are sharing debt, property, or an account with consequential obligations, review the governing contract and seek local legal advice as appropriate.
6. Plan for savings and a drop in income
Make savings visible in the monthly plan. Decide what the household is saving for, how much each person contributes, and where the money will be held. Discuss how you would respond to a job loss, illness, unexpected repair, or temporary reduction in income: which costs would be prioritized, whether contributions would change, and how long a temporary adjustment would last. The Canadian agency specifically recommends agreeing on what happens if income falls and identifies emergency savings as a shared goal.
7. Track spending and review the budget
- At the start of the month: Set the plan for income, shared bills, irregular costs, savings, and personal spending.
- During the month: Record or categorize spending using a notebook, receipts, bank records, a spreadsheet, a free worksheet, or a digital tool. The format matters less than having a consistent record.
- At month’s end: Compare actual spending with the plan. Identify categories that were underestimated, bills that changed, and any difference between the expected and actual leftover.
- For the next month: Adjust categories and contributions based on what happened. Revisit the agreement after changes in employment, income, household costs, or who lives in the home.
This plan-record-compare cycle follows Consumer.gov’s budget approach and the CFPB’s budget steps, modified June 25, 2026. You do not need paid software to keep a household budget: official worksheets, a small notebook, receipts, bank records, or a spreadsheet can all support the process.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.




