Free tools Windows power users keep installed
One-click scans. No signup required.
You can sell some life insurance policies to a third party for cash, but the payment is less than the policy’s death benefit and the buyer may become the owner or beneficiary, take over premiums, and collect the benefit when the insured dies. Before accepting an offer, compare it with options available under your policy, consider the effects on beneficiaries and benefits, and get tax and state-specific advice.
What it means to sell a life insurance policy
The National Association of Insurance Commissioners (NAIC) defines a life settlement as “the sale of a life insurance policy to a third party.” The seller receives less than the full death benefit. Depending on the transaction, the buyer becomes the policy owner and/or beneficiary, pays future premiums, and receives the death benefit when the insured dies. The seller’s beneficiaries may therefore lose the benefit the policy would otherwise have provided. NAIC’s consumer guide explains the basic transaction.


A viatical settlement is related but distinct: it involves a policy associated with an insured person who is terminally or chronically ill. The distinction matters, including for tax treatment; do not assume rules that may apply to a qualifying viatical settlement apply to every life settlement.
Can you sell your policy, and what happens next?
Whether a sale is available and what it means for you depend on the policy, the proposed transaction, and applicable state rules. A sale is not simply an insurer paying you the policy’s cash value. It is a transfer to a third party, with the buyer potentially acquiring ownership or beneficiary rights. Ask the insurer and any proposed settlement provider or broker to explain in writing which rights will transfer, who will pay premiums, and who can receive the death benefit.
#1 Best Overall
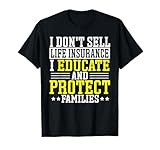
- Life insurance clothes that says: I don't sell life insurance, I educate and protect families.
- Life insurance clothes ideal for any insurance sales agent, medicare broker or salesperson who wants to show off his got life insurance vibe.
- Lightweight, Classic fit, Double-needle sleeve and bottom hem
Before proceeding, confirm whether the buyer can later resell the policy and what the contract says about that possibility. Also ask what fees, commissions, loans, or other deductions affect the amount you would actually receive. There is no universal payout percentage or typical dollar amount established here; compare the written net offers available for your policy rather than relying on a general estimate.
Compare a sale with your policy’s other options
Contact your insurer before signing a settlement agreement. The NAIC recommends asking about policy options and available cash value. Depending on your contract, alternatives may include surrendering for cash value, borrowing against the policy, or using an accelerated death benefit or another policy provision. These options are not available under every contract, and a loan or withdrawal may affect coverage or the amount ultimately paid. Ask the insurer how each option would work for your policy.
Rank #2

- Funny design. Life insurance clothes that says: I am a life insurance agent I solve problems you don't know you have in ways you can't understand.
- Life insurance apparel ideal for any insurance sales agent, medicare broker or salesperson who really enjoys selling insurance.
- Lightweight, Classic fit, Double-needle sleeve and bottom hem
Compare routes using the same practical questions:
- Net cash now: What will you receive after fees, commissions, outstanding loans, and other deductions?
- Coverage and beneficiaries: Does coverage continue, and who would receive any future benefit?
- Ongoing costs or obligations: Who pays premiums, and what responsibilities remain with you or the insured?
- Tax and public benefits: What federal and state tax consequences or means-tested benefit effects could apply?
- Rights and protections: What contract rights, state disclosures, licensing rules, and rescission rights apply?
- Privacy and contact: What personal or medical information is collected, who may receive it, and whether the insured may be contacted later?
Understand the effects on beneficiaries, privacy, and finances
Beneficiaries and policy rights
Because a buyer may become owner or beneficiary, a sale can remove the death benefit from the protection you intended for your beneficiaries. Read the transfer documents carefully and ask who will hold each right after closing. The New Jersey Department of Banking and Insurance’s life settlement guidance is one state example of consumer information; it should not be treated as a statement of the rules in every state.
Medical and personal information
A settlement process can involve medical and other personal information, and it may be shared with additional parties. Before providing records or signing releases, ask what information is collected, who may see or receive it, whether it can be transferred if the policy is resold, how it is protected, and how often the insured may be contacted. The SEC’s investor guidance on life settlements discusses risks and considerations around these transactions.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Creditors and public assistance
NAIC advises policy owners to consider possible creditor claims and effects on public assistance benefits. If you receive, or may need, means-tested assistance, check the rules for the specific program and your circumstances before taking proceeds. A settlement can change financial resources in ways that affect eligibility; do not assume the payment will be disregarded.
Check state rules and the people involved
Settlement licensing, disclosures, privacy protections, rescission rights, and other requirements vary by jurisdiction. Contact your state insurance department to learn the current rules and verify whether the broker and provider are licensed or registered where required. Do not assume that a license or protection in one state establishes compliance in another. The NAIC recommends checking with the state regulator before entering a settlement.
Ask for all offer terms and fees in writing, including any applicable cancellation or rescission period. The sources cited here do not establish one nationwide rescission period, so verify the deadline and procedure under your state’s current law before signing or transferring rights.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Are life settlement proceeds taxable?
Tax treatment depends on the transaction type and individual facts; proceeds should not be assumed to be tax-free or wholly taxable. IRS Publication 559 discusses amounts received on the sale or assignment of a policy to a viatical settlement provider and explains that an exclusion depends on qualifying terminal or chronic illness conditions. The IRS also has separate transfer-for-value and information-reporting rules for reportable policy sales. Read IRS Publication 559 and consult a tax professional before accepting or assigning a policy.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Best Value

- Everybody'S Favorite Insurance Agent
- Celebrate insurance agents, brokers, medicare advisors, and sales agents with this! Perfect for agency workers who appreciate helping clients find the right insurance policies. Show pride in your role with this.
- Dual wall insulated: keeps beverages hot or cold
- Stainless Steel, BPA Free
- Leak proof lid with clear slider
Treasury and IRS final regulations TD 10052 address information reporting and transfer-for-value treatment for specified life insurance transactions; they took effect July 9, 2026. Their application depends on the transaction and the rules’ scope. Ask a qualified tax professional to assess the federal consequences for your situation, and check whether state tax treatment also applies. The IRS’s 2026 Internal Revenue Bulletin contains the final regulations.
Quick Recap
A practical checklist before accepting an offer
- Ask your insurer: Request your policy’s cash value and an explanation of loans, accelerated death benefits, withdrawals, surrender, and other available provisions, including their effects on coverage.
- Compare alternatives: Consider whether another source of cash or a policy option could meet the need while preserving more coverage or beneficiary protection.
- Review written offers: Compare the net cash after fees and deductions, not just the headline amount. Ask whether a broker receives a fee or commission.
- Map the rights being transferred: Confirm who will own the policy, who will be beneficiary, who pays premiums, whether the buyer can resell it, and what happens to your beneficiaries’ interests.
- Check information handling: Identify what records will be collected, who can access or transfer them, and any expected contact with the insured.
- Verify state protections: Contact your state insurance department about current requirements, the parties’ license or registration status, and any rescission deadline.
- Get individual advice: Ask a tax professional about federal and state tax consequences, and check creditor and public-assistance implications before the transaction is final.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




