UK banks are discussing funding and creating DeliveryCo, an industry-led company intended to deliver future retail payment infrastructure. The plan is not a new card scheme ready for consumers: the official goal is to add a way to pay shops and online retailers directly from a bank account, alongside cards. Its rules, protections, costs and launch date have not been settled.
What is being proposed?
The proposal is best understood as an account-to-account (A2A) payment option at checkout. Instead of routing a purchase through a debit- or credit-card scheme, the payment would move directly between the customer’s bank account and the retailer’s account. The Payments Systems Regulator describes A2A in those terms: account-to-account payments.
The National Payments Vision calls for ubiquitous A2A payments in shops and online, but explicitly says cards will continue to play an important role. The aim is an additional choice, not an announced plan to abolish Visa or Mastercard. The UK Government says almost 50 billion payments were made in the year before the Vision was published in 2025; it also reports 29.1 billion credit- and debit-card payments in 2023. National Payments Vision
What has been announced—and what remains undecided?
The Bank of England’s Retail Payments Infrastructure Board (RPIB) is developing a blueprint for next-generation retail payments infrastructure. The Bank said on 25 June 2026 that the RPIB had launched a consultation to inform that blueprint and that an industry-led Delivery Company is expected to deliver the infrastructure. Pay.UK is to continue operating existing retail interbank systems during development. Bank of England announcement, 25 June 2026
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
#1 Best Overall

- With Square Terminal, you can ring up sales, accept payments, and print receipts, all with one device. Use it at the counter or ring up customers anywhere in your store.
- Accept all major credit and debit cards and pay one low rate with no hidden fees and no long-term contracts.
- Process chip cards in just two seconds.
- Get your money as soon as the next business day.
- Use it cordlessly with the built-in battery, designed to last all day.
In a February 2026 speech, Bank of England Deputy Governor Sarah Breeden said the intended option would complement card schemes. She also stressed that infrastructure alone would not be enough: scheme rules, a viable commercial model and appropriate consumer protection would be needed to encourage firms to offer it. Sarah Breeden’s speech, 2 February 2026
The Guardian reported in February 2026 that a first funder meeting for DeliveryCo was chaired by Barclays UK chief executive Vim Maru. The report named Santander UK, NatWest, Nationwide, Lloyds Banking Group, Link and Coventry Building Society among funders, and said Visa and Mastercard were also in the group. It described work on a legal structure, leadership plans and future funding models. That is reporting about discussions, not a final membership list or settled governance. The Guardian also reported a possible 2030 timeframe; it should not be treated as an official launch commitment. The Guardian, February 2026
Rank #2

- Use the, easy-to-use, and customizable POS to get started.
- Accept contactless payments, chip cards, Apple Pay, and Google Pay from anywhere, with improved connectivity, extended battery life, and enhanced security. Pay one low rate for every tap or dip.
- No long-term commitments or contracts, no monthly fees- and with offline payments, keep taking payments for up to 24 hours.
- Safely and securely accepts payments anywhere. Plus, get data security, 24/7 fraud prevention, and payment-dispute management at no extra cost.
- Use the, easy-to-use, and customizable POS to get started.
The available official announcements do not establish the eventual service’s brand, technology, eligibility, merchant acceptance model, fees, scheme rules, protections, final participants, funding arrangements or delivery date. The June consultation response deadline has passed, but the sources cited here do not establish the subsequent decision or blueprint outcome.
How it differs from existing bank transfers and cards
A2A is not new in itself. Faster Payments already moves money between UK accounts: the Government says the system was developed in 2008 and handled 4.9 billion payments in 2023, or 10% of all UK payments that year. But an account transfer is not automatically a complete retail checkout service. A national option would need to make it practical for customers to initiate and confirm a purchase, for merchants to accept it, and for both sides to rely on clear processes if a payment goes wrong.
Rank #3

- 【Universal Compatibility】 - The MDB Payment Device to PC Converter is designed to connect a variety of MDB devices such as acceptors, bill receivers, and card readers effortlessly. It offers seamless integration with any vending equipment compliant with MDB specifications, ensuring versatility in your payment solutions.
- 【User-Friendly Interface】 - This USB adapter features a straightforward setup process. Simply connect it to your computer, and the adapter transforms MDB protocols into RS-232 serial protocols. This allows for easy communication between your vending machine and your PC, simplifying operations while providing reliable performance.
- 【Enhanced Control】 - With capabilities to control up to eight MDB-compatible devices simultaneously, this converter enhances your management efficiency. Whether you’re handling dispensers or bill acceptors, experience effective monitoring and command over your vending machine operations like never before.
- 【Robust Functionality】 - The MDB-PC USB converter supports a variety of interfaces, including cash interfaces (10H and 60H) and USD interfaces (40H). This broad support mechanism ensures compatibility across multiple configurations, making it an ideal solution for complex setups.
- 【Comprehensive Package】 - Each converter comes complete with required cables, a user guide, and a user agreement, providing everything you need for successful installation. Designed for easy implementation, enjoy a plug-and-play experience with reliable support for all essential MDB functions.
| Payment type | What it means | What the cited sources establish |
|---|---|---|
| Card payment | A purchase routed through a card scheme, such as Visa or Mastercard. | Cards remain an important part of the UK payments ecosystem, according to the National Payments Vision. |
| Existing bank transfer or pay-by-bank service | Money moves from one bank account to another; some services use this for payments to businesses. | Faster Payments is an existing UK interbank system. Its existence does not establish card-equivalent merchant acceptance or dispute rights for every transfer. |
| Proposed national retail A2A option | A bank-account payment designed to work as an additional choice at shop and online checkouts. | The infrastructure and blueprint are being developed; final service terms and availability are not established. |
What would make an A2A checkout useful?
The practical test is not simply whether money can move between accounts. The PSR identifies four areas for improvement: functional capability, dispute processes, sufficient access and reliability, and competitive pricing. For a customer or a retailer, those translate into questions about the whole purchase journey.
- Acceptance and availability: Can customers use it at the retailers they visit, and can people with different banks access it?
- Speed and convenience: Is payment confirmation clear, and does checkout work as smoothly as the alternatives?
- Disputes and fraud: What happens if a payment is unauthorised, a product does not arrive, or the service is unavailable?
- Reliability and access: Can the service work consistently, including when a bank or payment provider has an outage?
- Merchant costs: What will businesses pay, and will any savings be reflected in the commercial model?
- Recurring payments: Can customers set up, manage and stop repeat payments under understandable rules?
These are design and policy questions, not features that have already been promised for the proposed service. Breeden said in February 2026 that the average merchant cost of accepting card payments was around 0.6%, and that the smallest merchants paid more than four times the average cost paid by very large merchants. Those figures, cited in her speech, illustrate why cost is part of the discussion; they do not establish what a future A2A service would charge.
Rank #4

- Effortless payments and printing: Accept card payments and print payment receipts on the spot with the built-in 40 mm thermal printer.
- Faster sales processing: Use pre-set menus and catalogs to make transactions faster and smoother for you and your customers.
- Reliable and portable: Featuring a 6.5" HD touchscreen made from Corning Gorilla Glass and a powerful battery that lasts all day.
- Seamless connectivity: Stay connected with free mobile data and WiFi, ensuring uninterrupted transactions.
- Real-time payment tracking: Monitor payments and issue refunds right from your device, so you're always in control.
What is happening before the national infrastructure is ready?
Companies have announced separate A2A initiatives, but these should not be confused with DeliveryCo or taken as proof of universal availability.
Visa’s variable recurring payment demonstration
Visa reported that its first commercial UK variable recurring payment demonstration took place in November 2025 with Kroo Bank, Utilita and Tink. In Visa’s account, Tink initiated the payment, Kroo sent it through Faster Payments, Visa provided an operating model and dispute framework, and Utilita was the merchant. This was a company-reported demonstration involving named participants, not evidence that the proposed national infrastructure is ready or that the service is available at all retailers. Visa announcement, 19 November 2025
Best Value
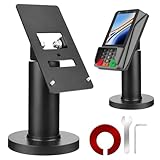
- Compatibility - This POS display stand is compatible for Pax A35, Pax S300. Note: Please carefully confirm the POS machine model before purchasing.
- Easy Installation - Installs quickly using the included type adhesive tape or can be permanently installed to any surface via a drilled hole and bolt mount. And can be removed by heating the area with a hairdryer and using string/thread to detach it if needed.
- Adjustable Card Terminal Mount - The 360-degree swivel allows cashiers to effortlessly turn the device left and right to assist customers without leaving their side, while the 65-degree tilt ensures the terminal is positioned at the optimal angle for various counter heights.
- Commercial Strength - Steel construction gives this universal POS stand durability for use as counter payment terminal in almost any setting.
- Perfect Height - The Pax A35 credit card payment machine stands' ideal height of 4.7" is designed for optimal counter alignment. It provides ample clearance for card insertion and can be adjusted using the tilt feature. Once the perfect tilt angle is set, secure it in place with the included Allen key and wrench to prevent unwanted movement.
Mastercard’s A2A Protect work
Mastercard announced in July 2025 that Monzo, NatWest and Santander were collaborating on a UK A2A service focused on fraud prevention and dispute resolution. The announcement describes Mastercard’s initiative, not the final protections for a future national scheme. In particular, protections against authorised push payment (APP) fraud should not be assumed to cover a faulty purchase or other consumer dispute. Mastercard announcement, July 2025
What should consumers and businesses do now?
There is no need to change how you pay based on the DeliveryCo discussions alone. When using any existing pay-by-bank or bank-transfer option, check the payment provider’s terms and the retailer’s process rather than assuming the transaction has the same acceptance, refund or dispute arrangements as a card purchase. Merchants considering A2A should likewise compare the actual service terms, customer reach, reliability and total costs when those details are available.
The immediate development to watch is the official infrastructure blueprint and the rules that accompany it. A genuinely useful alternative will depend on those details—not just on building new payment rails.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minute



