Use a first credit card only for purchases already in your budget, then pay the full statement balance by the due date whenever possible. Check the card’s grace-period and fee terms, review transactions and statements, and set payment reminders or carefully monitored autopay. If you cannot pay in full, make at least the minimum on time—but expect interest on the unpaid balance.
What a credit card does—and what it can cost
A credit card lets you buy now and repay later, usually with interest. The amount left unpaid affects how much borrowing costs; carrying a balance can make purchases more expensive than their original price. The Federal Trade Commission explains the basic trade-off in its guide to using credit cards and disputing charges.
How to pay your bill
Pay the full statement balance by the due date when possible
The statement balance is the amount billed for that cycle. Paying it in full by the due date can avoid interest on purchases if the card offers a grace period and the account is not already carrying a balance. The Consumer Financial Protection Bureau defines a grace period as “the period between the end of a billing cycle and the date your payment is due.” A grace period is not required on every card, so check the card agreement for its terms and whether they apply to your account. See the CFPB’s grace-period explanation.
If you cannot pay in full
Pay at least the minimum by the due date. The FTC advises: “If you can’t pay your full balance, make at least the minimum payment.” The unpaid amount can accrue interest, and paying only the minimum generally makes credit more expensive over time. A minimum payment keeps you from missing the required payment, but it does not make borrowing interest-free.
Recommended Free Tools
#1 Best Overall

- DOUBLE POCKET & GREAT STORAGE: This phone sleeve with 2 layer, double pocket design, with much more storage than others, you can easily put your credit cards, Debit Cards, Cash etc.
- UNIVERSAL FITMENT: This phone wallet pocket fits almost all smartphones, includeing iPhone X/XS/XS Max/XR /8 /8 Plus /7 /7 Plus /6 /6 Plus, Samsung Galaxy S6/S5/S4/S3, Galaxy Note 5/4/3/2/ 1,ect.
- STRONG ADHESIVE: Sticker makes the card holder strong enough on any smooth surface, such as normal glasses, smooth cell phone cases, leather phone case. Please note: Oil-resistant mobile phone cases and original phone glass back are not suitable for this product, such as Liquid Silicone Gel Rubber Case
- MULTI USE: It can not only be attached to back of phone, it can stick on every smooth surface place. Add a extra pocket in car, computer or on the fridge and have more storage space.
- EASY USE, EASY CARRY: Just peel off the cover of the phone wallet, stick on back of phone, and finish by softly pressing. With it you can carry only one phone out of door but with your card, cash, ear phone all your needs.
Do not assume every transaction gets purchase terms
Cash advances generally begin accruing interest on the transaction date, rather than receiving the purchase grace period. Check the agreement for how the card treats cash advances and other transaction types before using them.
Build a reliable payment routine
- Note the due date. Find it on the statement or issuer account page, and set a calendar alert a few days before it.
- Review the statement each cycle. Check the balance, payment due date, fees, and transactions. Contact the issuer promptly about unfamiliar charges or possible errors; the FTC explains how to review and dispute charges.
- Choose a payment method you can monitor. You can make payments manually or use autopay if the issuer offers it. With autopay, check that the withdrawal occurred and keep enough money in the linked bank account to cover it.
- Confirm the payment posted. Do not assume that scheduling a payment is the same as seeing it credited. Check the account after payment, especially if you are close to the due date.
The FTC’s straightforward rule is: “Make your credit card payments by the due date every month.”
Rank #2
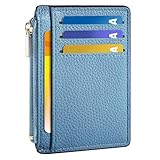
- Ultra Slim and RFID Blocking Wallet: This thin card wallet is equipped with advanced RFID blocking technology. It protects your valuable information like ID and credit cards from unauthorized scans. It also allows you to bring it along in your handbag, backpack, front pocket, or purse
- Functional Front Pocket Wallet: Despite its thin design, this credit card holder has ample space to store your cards: 6 card slots, 1 ID window for easy access to your driver's license or ID card, and 1 side compartment for cash / currency
- Credit Card Holder: Ultra-slim and lightweight, at just 4.4" x 3.14" x 0.11" and 1.05 oz, our card holder is crafted from premium lychee leather. It's the minimalist's choice for carrying essential cards with ease, and it adds no bulk to your pocket or purse
- Front Pocket Design: This slim women's card holder is designed for everyday use. Whether you’re shopping, traveling, or heading to the office, this card holder perfectly adapts to your lifestyle
- Perfect Gifts: This credit card holder with exquisite clear box makes a perfect gift for your loved ones on their Birthday, Anniversary, Mother’s Day, Valentine’s Day or Christmas. It’s the best choice for travel, dating, working, shopping, exploring or daily use, etc
Choose an offer by its terms, not its rewards headline
There is no card choice established here as best for every student, and approval depends on the issuer’s criteria. Compare the offer disclosures and decide whether the terms fit how you will use the account:
- Annual fee: Check whether there is a recurring fee and whether any benefits would be useful enough to justify it.
- APR: Consider the interest rate that could apply if you carry a balance. Rewards do not make interest disappear.
- Grace-period terms: Confirm whether a purchase grace period is offered and what is required to keep or regain it.
- Late-payment consequences: Read the agreement for the fees or other consequences that can follow a late payment.
- Benefits: Value them against your actual spending rather than assuming they offset debt costs.
Terms and availability can change, so verify the current offer and eligibility requirements directly with the issuer before applying.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Rank #3

- Four-slot card holder: The card holder has three card slots for credit, debit or business cards, and a dedicated ID card slot
- RFID Blocking: Equipped with RFID blocking technology, it prevents unauthorized scanning of contactless cards, protecting your sensitive information from digital theft
- Thin and portable: Designed to be thin and portable, it is compact and can be easily put into a pocket or bag without adding bulk
- Long-lasting and Durable: Made of PU leather on the exterior, it is both durable and luxurious in appearance. The smooth surface protects the cards from scratches
- Fashion Design: Combining functionality and style, the stylish and simple appearance is suitable for various occasions, from business meetings to casual outings
Know the protections around student marketing
For the relevant federal marketing rules, Regulation Z defines a college student as a full-time or part-time student at an institution of higher education. It bars tangible gifts intended to induce students to open a credit account at covered campus locations or events, including near campus and institution-related events. Colleges must also publicly disclose agreements with card issuers for marketing credit cards. These rules address specific marketing practices; they do not guarantee that every card promoted to students has favorable terms. The CFPB summarizes the requirements in its Regulation Z page on college credit-card agreements.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.What historical campus-card figures show
The CFPB’s 2024 report describes agreements and student credit-card use in earlier periods, not current 2026 measurements. It reported that 143 college-affiliated credit-card partnerships represented 532,567 open accounts at year-end 2022, and that college partners received more than $19.6 million under those agreements in 2022. Those figures describe reported agreements and payments, not the terms or quality of any individual card.
Rank #4

- PRODUCT INCLUDE: 2*Zippered Pockets+1*ID Window+1*External Pocket+1*Key Ring+1*Lanyard.Smooth zippered pockets can effectively protect the coins and cards in your wallet.The Clear ID window can help you identify information faster.We also provide an external pocket and a ring to hold your cards and keys.You can also use the 14.6 inch lanyard to hang the wallet around your neck to avoid losing it
- PREMIUM MATERIAL: Sturdy Nylon+Smooth Zipper.ZHOMA small wallet is made of nylon which makes it very sturdy,you don't have to worry about tearing it during use.High quality materials and unique design create this fashionable multifunctional wallet
- PRACTICAL DESIGN: Small Size+3 Pockets+Easy Put 8 Cards In.The wallet size is 5.12 x 3.35 inch,making it perfect for storing your ID cards,credit cards, access cards,school cards,coins, cash,bills and so on,you can put up to 8 cards in this wallet.We also add protective measures to each pocket, such as zippers and metal buckles, to effectively protect your cards
- WIDE APPLICATIONS: Multi-function+Lightweight+Easy Clean.The small wallets can also be used as badge lanyard pouch,id case,card holders,coin purse and key case.Our wallet is lightweight, takes up less space, and is very convenient to carry. You can take it with you wherever you go, especially when traveling,it can effectively help you
- PERFECT GIFT: Fashionable+Various Brighten Colors.ZHOMA small wallets are very fashionable, with various bright colors,they are perfect for giving to friends, family, and children as gifts.Come and choose the one you like
The same CFPB report cited Department of Education estimates from the 2019–2020 National Postsecondary Student Aid Study, Undergraduate Collection, accessed in 2023: almost two in three college students had at least one card in their own name, almost one in three used credit cards to pay tuition and fees, and average student credit-card debt exceeded $4,000. These are historical estimates, not a snapshot of students’ finances today. The CFPB’s college credit-card agreements report provides the report context and data periods.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problems



