An interest rate is the price of borrowing money or the return paid for money deposited or lent, expressed as a percentage over a specified period. The percentage alone does not tell you the dollars you will pay or earn: the balance, time, compounding, fees, repayment schedule, and account or loan terms all matter.
What is an interest rate?
Interest is what a borrower pays to use someone else’s money, or what a depositor may earn for letting a financial institution use money in an account. The interest rate is the percentage applied to a balance over a period, usually quoted as an annual rate in U.S. consumer finance.
- Principal: the amount initially borrowed or deposited.
- Interest: the dollars paid or earned for the use of that principal.
- Interest rate: the percentage used to calculate interest. Check whether it is annual, fixed, variable, introductory, or conditional.
A rate is not the same as a dollar cost. To understand an offer, ask what balance the percentage applies to, how long it applies, how often interest is calculated or added, and what fees or payment rules apply.
How do interest rates work?
Simple interest: a basic illustration
For a fixed balance with no payments or compounding, a simple-interest estimate is:
#1 Best Overall

- Profitability calculations; cash flow function Calculates NPV and IRR for uneven cash flows
- Time-value-of-money and Amortization keys solve problems including: pension calculations, loans, mortgages, etc.
- Ideal calculator for students, managers and statisticians
- Built-in functionality : List-based one- and two-variable statistics with four regression options: linear, logarithmic, exponential and power
- The BA II Plus calculator is approved for use on the following professional exams: Chartered Financial Analyst exam. GARP Financial Risk Manager (FRM) exam. Certified Management Accountants exam
Interest = principal × rate × time
The rate and time must use compatible units. For example, $1,000 at 5% per year for one year produces $50 in interest: $1,000 × 0.05 × 1. This is an arithmetic illustration, not a universal estimate of a loan’s cost. Loan payments reduce the balance over time, while fees and other contract terms can change the total amount paid.
How does compound interest work?
With compound interest, interest added to a balance can earn interest in later periods. The Consumer Financial Protection Bureau’s example shows how that works: $1,000 at 5% compounded annually grows to $1,050 after year one. In year two, 5% applies to $1,050, producing $52.50 in interest and a $1,102.50 balance. This is an illustration, not a forecast or a deposit offer. More frequent compounding can affect growth, but fees, rate changes, and account conditions also influence what a saver actually receives.
Rank #2

- PROFESSIONAL FINANCIAL CALCULATOR : Built-in TVM, IRR, NPV. Engineered for business analysts, real estate investors, accountants, and finance students.
- ADVANCED CASH FLOW & AMORTIZATION : Execute time value of money, break-even analysis, depreciation schedules, and bond pricing. Trusted for professional exam prep", MBA coursework, and banking certifications.
- CATIGA CF-300 : Flip-open hard case with a snap-close design for a secure fit. Compact and portable: designed for daily professional use in office, classroom, or on-site.
- ALL-IN-ONE FOR PROFESSIONALS : From NPV/IRR for real estate analysis to statistical calculations for business analysts. Handles probability, linear regression, and complex financial formulas.
- MORTGAGE, LOAN & INVESTMENT CALCULATOR : Covers bond pricing, loan amortization, investment analysis, and exam-level computations. Your go-to accounting calculator, business calculator, and real estate calculator in one device.
What is the difference between a loan interest rate and the APR?
The stated interest rate describes the rate charged on the loan balance. The annual percentage rate (APR) includes the interest rate plus certain applicable loan charges. For mortgages, the CFPB notes that APR may include points, broker fees, and other charges. APR is useful for comparing similar credit offers, but it does not replace checking the loan’s term, payment schedule, variable-rate rules, and total dollars paid.
The CFPB illustrates why annualizing a short-term fee matters: a $15 charge for a two-week, $100 payday loan corresponds to an APR of almost 400%. That is an example of how a modest-looking fee can translate to a high annualized percentage—not a current market average.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Rank #3
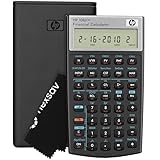
- HP 10BII+ FOR STUDENTS & PROFESSIONALS – This HP calculator is built for business, finance, accounting, and statistics courses. Perfect for learners and professionals who need to solve common financial problems quickly without memorizing formulas or relying on spreadsheets.
- 100+ FUNCTIONS FOR REAL WORLD MATH – Quickly solve time value of money, interest rates, loan payments, NPV, IRR, cash flows, and more. The 10bII+ also includes probability distributions for statistics courses—a feature not often found in financial calculators.
- ALGORITHMIC INPUT WITH DEDICATED KEYS – This high-school/college calculator uses algebraic and chain logic with minimal keystrokes. Layout appears the same as standard calculators for easy learning. Dedicated keys give quick access to commonly used financial and statistical functions
- APPROVED FOR MAJOR EXAMS – The HP 10bII+ algebra calculator is permitted for use on SAT, PSAT/NMSQT, and AP tests. An ideal statistics calculator and business calculator for school finance and accounting students preparing for class, coursework, or standardized exams.
- INCLUDES TRAVEL CASE, CLEANING CLOTH & BATTERIES– Slim, durable, and easy to keep on hand or store in a backpack or locker. Includes a protective case, cleaning cloth, and batteries so it’s ready out of the box. Large screen with clear contrast (non-backlit) is easy to read during exams or lectures.
How to compare loan offers
- Compare APR with APR for the same type of loan, amount, and duration.
- Check fees, payment amount and timing, and total repayment—not just the advertised rate.
- For a variable-rate loan, review when the rate can change and how that affects payments.
For mortgages, APR comparisons can mislead when the products differ: a fixed-rate loan is not directly equivalent to an adjustable-rate mortgage, adjustable loans may have different structures, and closed-end loans differ from home-equity lines of credit. Compare the underlying terms as well as APR.
What is the difference between a mortgage interest rate and an APR?
A mortgage interest rate is the rate applied to the outstanding loan balance. APR adds certain loan charges to the interest-rate picture to help show borrowing cost on an annualized basis. Because fees and loan structure affect APR, it can be a useful comparison measure for similar mortgages, not a complete measure of which mortgage will cost less in every situation.
Rank #4

- Solves time-value-of-money calculations such as annuities, mortgages, leases, savings, and more
- Performs cash-flow analysis for up to 32 uneven cash flows with up to 4-digit frequencies
- Calculates various financial functions: Net Future Value Net present Value Modified Internal Rate of Return Internal Rate of Return Modified Duration Payback Discounted Payback
- The Texas Instruments BAII Plus Professional features an Automatic Power Down (APD) function for extended battery life
- Prompted display guides you through financial calculations showing current variable and label. Ten-digit display
When comparing a fixed-rate and an adjustable-rate mortgage, examine the initial rate, the adjustment schedule, the index and margin if applicable, rate caps, possible payment changes, and cost under plausible scenarios. A fixed rate offers more predictable payments; an adjustable rate may change after its initial fixed period.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How do deposit interest rates and APY differ?
A deposit account’s interest rate is the stated rate applied to the balance. Annual percentage yield (APY) reflects that rate and the frequency of compounding over a 365-day period under deposit-account disclosure rules. APY makes it easier to compare the effect of compounding than a bare nominal rate, so compare APY with APY.
Best Value

- Sold as 1 Each.
- Ideal for students and professionals. Over 100 built-in functions including probability distributions.
- Intuitive keyboard layout with minimal keystrokes required for many common functions.
- Easy-to-read display with adjustable contrast and on-screen labels.
- Permitted for use on SAT, PSAT/NMSQT and College Board AP tests.
APY is not the only consideration. Check balance tiers, fees, minimum-balance requirements, introductory periods, and withdrawal or access terms; these can affect the return you realize.
How do changes in the federal funds rate affect the economy?
The Federal Open Market Committee (FOMC) sets a target range for the federal funds rate, a benchmark for overnight borrowing between banks. The Federal Reserve influences short-term market rates through monetary policy tools. A change in the target range can influence other short-term rates and broader financial conditions, which in turn affect household and business spending and can feed through to economic activity, employment, and inflation.
The effect is indirect and does not happen uniformly: a policy-rate move does not mechanically reset every mortgage, credit-card, auto, or savings rate by the same amount or at the same time. Consumer rates also reflect the product, lender, borrower, market expectations, and fees. A borrower’s creditworthiness can affect the rate offered, but no particular score guarantees a particular rate.
The Federal Reserve describes its mandate as promoting maximum employment and stable prices. Its longer-run inflation objective is 2%, measured by the annual rate of change in the personal consumption expenditures (PCE) price index; the FOMC reaffirmed that objective on January 27, 2026. This is an inflation objective, not an interest rate. In its explanation of monetary policy, the Fed says that a policy rate adjusted for inflation influences other real interest rates and borrowing costs. Tighter policy can slow activity and help restrain inflation, but outcomes take time and also depend on other forces.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Why do interest rates matter?
Rates affect the cost of carrying debt and the return on savings. A higher rate can increase borrowing costs, while a higher deposit yield can increase earnings on savings; the actual effect depends on the balance, timing, and product terms. When deciding whether an offer fits your needs, compare the measures that match the product—APR for similar loans and APY for deposit accounts—and read the terms behind them.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




