Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →CRN’s 2025 Data Center 50 is an editorial list—not a ranking of the 50 largest, best, or most profitable data-center companies. It brings together hyperscale cloud providers, colocation operators, chipmakers, server manufacturers, networking companies, storage vendors, software providers, and power-and-cooling specialists benefiting from the artificial-intelligence infrastructure boom.
The list matters because the data-center market is no longer only about building rooms full of servers. AI workloads are increasing demand for accelerators, high-bandwidth networks, dense racks, liquid cooling, reliable electricity, storage throughput, and interconnection. For buyers and investors, the useful question is not simply which company is “hottest,” but what each company sells, how mature its capacity or products are, and which infrastructure bottleneck it addresses.
What CRN’s Data Center 50 actually means
CRN’s feature, published in 2025, identifies 50 companies it considered influential or notable in the data-center market. The source does not publish a formal scoring system, revenue threshold, weighting model, or numerical ranking. The companies are not listed from No. 1 to No. 50.
Accordingly, the list should be read as a snapshot of market momentum around the 2025 AI-infrastructure investment cycle. It is not a market-share table, valuation ranking, customer-satisfaction survey, technical benchmark, or analyst-certified list of the industry’s top companies. The article also does not represent 50 companies with identical business models: comparing Nvidia with Equinix or Iceotope requires understanding that they operate at different layers of the infrastructure stack.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallCrashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minute#1 Best Overall
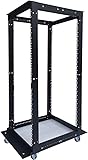
- This 32U open frame server rack features a robust steel frame with an impressive 440 lb weight capacity, ideal for hosting heavy servers, networking equipment, and AV gear. The Open Frame relay is 32U - W21" x H62" X D (24" - 38")
- Perfect for Data Centers & Home Offices: Whether you're outfitting a large-scale data center, upgrading your home server setup, or organizing your networking gear, this versatile rack is a reliable solution for all your equipment storage needs. Optimized Ventilation: The open frame design enhances airflow around your equipment, reducing the risk of overheating and ensuring better performance and longevity of your gear.
- Adjustable & Customizable: The rack features adjustable mounting rails to easily fit various types of server and network hardware. Great for rack-mounted servers, cabling, and other networking components. Easy Assembly: Quick and simple tool-free assembly, so you can get your rack set up and running without hassle. Ideal for IT professionals, network administrators, and hobbyists.
- Rackmount Design: Compatible with most standard 19-inch rackmount servers, network switches, routers, and other IT equipment. Flexible to accommodate 18U, 22U, 27U, 32U, 42U and custom configurations.
- Perfect for Data Centers & Home Offices: Whether you're outfitting a large-scale data center, upgrading your home server setup, or organizing your networking gear, this versatile rack is a reliable solution for all your equipment storage needs. Optimized Ventilation: The open frame design enhances airflow around your equipment, reducing the risk of overheating and ensuring better performance and longevity of your gear.
CRN’s framing reflected a market in which data-center spending was accelerating and electricity, GPU availability, networking, construction, and cooling were becoming strategic constraints. CRN attributed a 34 percent year-over-year increase in data-center spending to Synergy Research Group and discussed more than half a trillion dollars in investment announcements made in January 2025. Those figures describe the market backdrop reported at the time, not guaranteed completed capacity.
Read CRN’s original Data Center 50 feature.
The 50 companies at a glance
The table below reorganizes CRN’s list by commercial role. “Why it appeared” summarizes the source’s emphasis; it should not be interpreted as an independent performance judgment.
| Company | Primary role | Why it appeared on the list | Buyer relevance |
|---|---|---|---|
| Accelsius | Cooling | NeuCool liquid-cooling systems for dense racks | High-density thermal upgrades |
| Aligned Data Centers | Colocation and development | Hyperscale-oriented, power-dense campuses | Large-scale capacity |
| Amazon Web Services | Public cloud | Global cloud and AI infrastructure expansion | Managed compute and AI services |
| AMD | Semiconductors | Data-center CPUs and AI accelerators | Alternative accelerated-computing platform |
| American Tower | Edge infrastructure | Distributed infrastructure relevant to edge computing | Latency-sensitive deployments |
| Applied Digital | Data-center development and computing | AI-focused facilities and water-use claims | Specialized high-density capacity |
| Arista Networks | Networking | High-performance switching for cloud and AI networks | Data-center fabrics |
| Broadcom | Networking and semiconductors | Connectivity components and infrastructure silicon | Switching and custom infrastructure platforms |
| Cato Networks | Secure networking | Cloud-delivered networking and security | Distributed and hybrid connectivity |
| Cisco Systems | Networking | Data-center networking, security, and enterprise infrastructure | Broad network and support portfolio |
| Cloud Software Group | Infrastructure software | Hybrid-cloud and virtualization-related software | Enterprise application infrastructure |
| Cologix | Colocation and interconnection | Network-neutral facilities and planned expansion | Interconnection and regional capacity |
| CyrusOne | Colocation | Enterprise and hyperscale data-center expansion | Large deployments |
| Dell Technologies | Servers and infrastructure | Enterprise AI systems, servers, storage, and services | Private and hybrid infrastructure |
| Digital Realty | Colocation and data centers | Global facilities, hyperscale capacity, and interconnection | Global physical infrastructure |
| Eaton | Power | UPS and energy-management systems | Power protection and resilience |
| EdgeConneX | Colocation and edge | Distributed, hyperscale, and edge-oriented facilities | Regional and low-latency capacity |
| Equinix | Colocation and interconnection | Global footprint, cloud on-ramps, and AI-ready facilities | Hybrid cloud and connectivity |
| Extreme Networks | Networking | Cloud-managed and data-center networking | Enterprise network operations |
| Flexential | Colocation and managed infrastructure | U.S. facilities, connectivity, and AI-related capacity | Colocation plus managed services |
| Google Cloud | Public cloud | Cloud, AI, analytics, and Kubernetes infrastructure | Cloud-native and data-intensive workloads |
| H5 Data Centers | Colocation | Regional facilities and enterprise infrastructure | Colocation and connectivity |
| Hewlett Packard Enterprise | Servers and enterprise infrastructure | Private cloud, AI systems, and GreenLake offerings | On-premises and hybrid environments |
| Hitachi Vantara | Data infrastructure | Storage, data management, and enterprise systems | Data-intensive enterprise workloads |
| IBM | Cloud and enterprise infrastructure | Hybrid cloud, regulated workloads, and enterprise services | Managed and hybrid environments |
| Iceotope | Liquid cooling | Precision cooling for dense compute | AI and high-density thermal management |
| Intel | Semiconductors | Data-center processors and computing platforms | General-purpose and accelerated infrastructure |
| Iron Mountain | Colocation | Global facilities and compliance-oriented infrastructure | Regulated and enterprise workloads |
| JetCool | Liquid cooling | Direct-to-chip cooling and coolant-distribution systems | Dense server and GPU deployments |
| Juniper Networks | Networking | Data-center networking and observability | Network operations and connectivity |
| Lenovo | Servers | Enterprise systems and liquid-cooled infrastructure | Private infrastructure and AI servers |
| LogicMonitor | Monitoring software | Hybrid IT infrastructure visibility | Operations and observability |
| Lumen Technologies | Connectivity | Network and managed-infrastructure services | Inter-site and edge connectivity |
| Microsoft | Public cloud | Azure expansion and AI-focused data-center investment | Microsoft-centric cloud and hybrid workloads |
| NetApp | Storage and data management | Hybrid-cloud storage and AI data services | Data pipelines and enterprise storage |
| NTT Global Data Centers | Colocation | Global data-center development and operations | International capacity |
| Nutanix | Hyperconverged infrastructure | Hybrid multicloud and simplified infrastructure management | Private and hybrid cloud |
| Nvidia | AI compute | GPUs, accelerated systems, and DGX platforms | AI training and inference |
| Oracle | Public cloud | OCI expansion and participation in Stargate | Oracle applications and AI capacity |
| Pure Storage | Storage | High-performance enterprise and AI storage | Fast data access and storage modernization |
| Quantum | Storage | Data storage and management, including unstructured data | Large data repositories and archives |
| Scale Computing | Edge and HCI software | Distributed infrastructure and simplified operations | Remote and edge sites |
| Schneider Electric | Power and cooling | Facility systems and high-density reference designs | Electrical and thermal infrastructure |
| STACK Infrastructure | Colocation and development | Hyperscale-oriented campuses and expansion | Large-scale capacity |
| Supermicro | Servers and rack systems | Dense GPU systems and rapid AI deployment | AI servers and rack-scale infrastructure |
| TierPoint | Colocation and managed services | Colocation, cloud, backup, and disaster recovery | Managed enterprise infrastructure |
| Vantage Data Centers | Colocation and development | International expansion and financing for new capacity | Hyperscale and large enterprise deployments |
| VAST Data | AI storage and data platform | High-performance data infrastructure for AI | Large-scale AI data pipelines |
| Vertiv | Power and cooling | UPS, thermal systems, racks, and AI infrastructure | Facility-level capacity upgrades |
| ZutaCore | Liquid cooling | Direct-to-chip, two-phase or vapor-based cooling | High-density cooling with reduced water dependence |
1. Hyperscalers and cloud platforms
AWS, Google Cloud, Microsoft, Oracle, and IBM represent the cloud side of the list. Customers generally buy virtual machines, accelerated computing, storage, databases, analytics, AI services, networking, and managed operations rather than individual racks.
AWS was highlighted for major infrastructure commitments, including figures reported by CRN of $11 billion for a Georgia project and $8.3 billion in India infrastructure investment. These should be understood as announced investments or commitments, not necessarily commissioned capacity. Microsoft was reported as committing $80 billion in January 2025 to AI-focused data-center campuses and planning at least $35 billion across 14 countries over three years. Again, commitments are not the same as money already spent or capacity already available.
Oracle’s inclusion was tied partly to its role in Stargate, described by CRN as a $500 billion project backed by OpenAI, SoftBank, and Oracle, with $100 billion intended for a Texas build-out. CRN also contains a conflicting reference to $500 million. Because project scope, financing, and deployment schedules can change, the figures should be treated as attributed announcement amounts—not as verified operational capacity.
Cloud is usually the fastest route to compute and managed services, but it can introduce complex usage-based billing, data-transfer charges, architectural dependence, and platform lock-in. IBM is particularly relevant to organizations prioritizing hybrid cloud, bare-metal options, regulated workloads, or IBM-centered environments.
2. Colocation and data-center developers
Aligned, Cologix, CyrusOne, Digital Realty, EdgeConneX, Equinix, Flexential, H5, Iron Mountain, NTT Global Data Centers, STACK, TierPoint, and Vantage provide or develop physical data-center capacity. American Tower contributes an edge-infrastructure angle, while Lumen is more directly a connectivity and managed-infrastructure provider.
Customers in this category usually purchase cabinets, cages, power, private suites, cross-connects, cloud on-ramps, network access, and sometimes managed services. The differentiators are not just square footage. Buyers should examine usable megawatts, delivery dates, rack-density support, carrier neutrality, local permitting, interconnection ecosystems, geographic diversity, redundancy, and the provider’s ability to expand.
Rank #2

- Durable: Wall Mount Rack made from heavy duty cold rolled steel, 60lbs(27kg) weight capacity; Electrostatic powder coat preventing rust and corrosion
- Space-saving: Horizontal or vertical installation; Small footprint without giving up the storage capacity of devices
- Optimized Airflow: Wall Mount Network Rack with four-sided vents to enhance air circulation and prolong the life of equipment
- Considerate Design: Different screw hole combinations enable positions of rack rails to be adjusted according to demands; Bottom passable holes of Wall Mount Rack allow cables to pass freely
- Widely Applicable: EIA/ECA-310-E complaint; Fit 19in racks and cabinets to hold non-rack mountable devices; Multi-scene application like studio, home office, data center and so on
CRN reported that Cologix planned more than $7 billion in investment, including a proposed 154-acre, 800-megawatt facility in Johnstown, Ohio. That is development capacity, not completed capacity. The same distinction applies to Vantage, where CRN reported $13 billion in financing and expansion in Ohio, Ireland, Northern Virginia, Switzerland, Malaysia, and Japan. Financing supports growth but does not prove that all planned megawatts are commissioned or available to customers.
Digital Realty was described as having approximately 300 facilities in 50 cities across six continents. CRN also reported that 11 Illinois facilities were matched with 100 percent clean energy. “Matched” is not necessarily the same as being physically powered by renewable electricity every hour; it may involve renewable-energy certificates, power-purchase agreements, or another accounting method.
Equinix was cited with figures including 10,000 customers, more than 310 Fortune 500 customers, and 260 AI-ready data centers. These are time-sensitive company or source figures and should not be treated as permanently current. Equinix is most strategically important when interconnection, carrier choice, and hybrid-cloud access matter as much as floor space.
Flexential’s association with a proposed lunar data center is an interesting future-facing initiative, but it should not be counted as operating commercial capacity. In general, every buyer should separate announced sites, financed projects, construction, commissioning, and customer-available capacity.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →3. AI chips, servers, and rack-scale systems
AMD, Intel, Nvidia, Dell Technologies, Hewlett Packard Enterprise, Lenovo, Supermicro, and Broadcom sit across the compute and system layers.
Nvidia is the most visible AI-accelerator company in the group, with GPUs and DGX systems forming the basis of many AI deployments. AMD provides competing accelerator and processor options, while Intel remains important across general-purpose data-center computing and related platforms. Broadcom is included primarily as an infrastructure-silicon and networking enabler.
Dell, HPE, Lenovo, and Supermicro turn processors and accelerators into deployable servers, storage systems, and rack-scale platforms. Their value is not limited to the chip inside a server. Buyers must evaluate GPU availability, CPU and accelerator compatibility, memory, local storage, networking, power draw, rack dimensions, firmware, support, warranty, and integration with orchestration software.
A “GPU-ready” facility or server does not necessarily mean GPUs are immediately available. Usable AI capacity requires the complete chain: accelerator supply, servers, power delivery, cooling, high-speed networking, storage throughput, software, and trained operators. A company can have an AI-ready design while still having limited commissioned or customer-available capacity.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #3
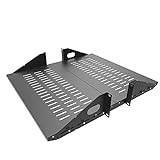
- Compatible with all 19” racks and cabinets to hold various IT, network and other equipment.
- Dimensions: W 19" x D 10" x H 2U per shelf ; 2 Shelves as set
- This Vented Center Weighted Mounting Rack Shelf fits the mounting posts in different deepth from 75 mm to 125mm.
- Max Weight Capacity: 110 Pounds; Center weighted.
- Slotted Venting to Improve Air flow and Help Prevent Overheating of Your Equipment
4. Networking and connectivity
Arista, Cisco, Cato Networks, Extreme Networks, Juniper Networks, Lumen Technologies, and Broadcom address the movement and protection of data.
AI clusters make networking a central performance consideration. Training and inference systems can require large volumes of data to move between accelerators, storage systems, racks, campuses, and cloud regions. Buyers should consider switching capacity, latency, congestion control, optics, routing, network telemetry, security, carrier diversity, and compatibility with the chosen compute platform.
Arista is particularly associated with high-performance data-center switching and AI fabrics. Cisco offers a broad networking and security portfolio with extensive enterprise support. Juniper combines data-center networking with observability, while Extreme Networks emphasizes cloud-managed networking. Cato focuses on cloud-delivered secure networking rather than selling traditional data-center capacity. Lumen provides connectivity and managed infrastructure that can link sites, clouds, and edge locations.
The right choice depends on the topology and operating model. A small enterprise does not need the same network architecture as a hyperscale AI cluster, and a secure branch-to-cloud deployment is not interchangeable with a high-throughput east-west data-center fabric.
Free tools Windows power users keep installed
One-click scans. No signup required.
5. Storage, data management, and infrastructure software
Cloud Software Group, Hitachi Vantara, LogicMonitor, NetApp, Nutanix, Pure Storage, Quantum, Scale Computing, and VAST Data represent the software and data layers that make infrastructure usable.
AI performance depends on more than accelerator count. Data must be collected, cleaned, stored, moved, protected, monitored, and presented to compute systems quickly enough to prevent expensive accelerators from waiting for input. Storage vendors therefore compete on throughput, latency, scalability, data reduction, resilience, file and object support, cloud integration, and operational simplicity.
NetApp focuses on hybrid-cloud storage and data management. Pure Storage is associated with high-performance enterprise and AI storage. VAST Data targets large-scale AI data platforms, while Quantum addresses storage and management for substantial data repositories, including unstructured data. Hitachi Vantara and IBM serve broader enterprise data and hybrid-infrastructure requirements.
Nutanix and Scale Computing simplify infrastructure through hyperconverged or distributed models, which can be useful for private cloud, branch, and edge environments. LogicMonitor provides infrastructure observability across hybrid IT. Cloud Software Group represents enterprise infrastructure and hybrid-cloud software. These products may be less visible than GPUs or new campuses, but poor monitoring, fragmented data, and difficult orchestration can undermine an otherwise powerful data center.
Rank #4

- Space-Saving Design: Measures 19.0"H x 21.7"W x 17.7"D with a 14.2" max mounting depth, our 9U rack fits tight spaces while holding full 19" gear—ideal as a server cabinet or wall mount network cabinet for home offices and small server rooms
- Full Security: Both the lockable glass door and side panels protect your hardware from theft or tampering. This 9U wall mount rack gives you peace of mind in public or shared environments, ensuring your equipment rack stays safe and secure
- Active Cooling: The built-in cooling fan prevents overheating, keeping your wall mount server rack running reliably. Perfect for active networks, this 9U network rack extends the life of switches, routers, and PDUs by maintaining consistent airflow
- Heavy-Duty Build: Cold-rolled steel construction supports up to 110 lbs of 19" IT and A/V devices. Whether you need a wall mount server cabinet for shallow servers or a wall mount network rack for patch panels, this delivers years of reliable use
- Easy Installation: Pre-marked mounting holes and top/bottom cable ports make setup fast. Adjustable rails and numbered U positions allow precise rack mounting of your gear. This turns any wall into a tidy, professional server room in minutes
NetApp and Nutanix separately referenced their inclusion in CRN’s 2025 list. Those first-party references confirm recognition; they do not independently establish that either company is objectively among the 50 most important companies in the sector.
6. Power and cooling specialists
Accelsius, Applied Digital, Eaton, Iceotope, JetCool, Schneider Electric, Vertiv, and ZutaCore address the physical constraints created by higher-density computing.
AI systems can draw substantially more power per rack than conventional enterprise workloads. That increases demand for switchgear, UPS systems, power distribution, energy management, heat removal, plumbing, facility controls, and appropriate rack designs. Eaton, Schneider Electric, and Vertiv operate across facility power and thermal infrastructure; Accelsius, Iceotope, JetCool, and ZutaCore are more specialized cooling names.
CRN described Accelsius’ NeuCool racks, Iceotope’s liquid-cooling technology, JetCool’s coolant-distribution units, Schneider Electric’s Nvidia-linked high-density reference design, and ZutaCore’s direct-to-chip vapor-based approach. Applied Digital was also highlighted for high-density facilities and a company-described “waterless” cooling approach.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsLiquid cooling is not automatically better for every workload. It can support higher rack densities and reduce certain thermal limits, but it may require coolant-distribution units, facility plumbing, compatible servers, leak-management procedures, maintenance training, and retrofit planning. Air cooling remains practical for many conventional enterprise deployments.
Likewise, “waterless” can mean different things. It may refer to zero water consumption, reduced potable-water use, or a particular non-evaporative design. Buyers should request the precise water-use boundary, operating assumptions, and measurement method rather than treating the label as self-explanatory.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How to evaluate a company on the list
The CRN designation is a starting point, not a procurement decision. Use a consistent framework:
- Identify the role. Decide whether you need cloud compute, physical capacity, servers, chips, networking, storage, monitoring, power, cooling, or managed services.
- Separate live capacity from plans. Ask whether figures refer to operational, commissioned, under-construction, financed, announced, or customer-available capacity.
- Test AI readiness. Check accelerator availability, rack density, cooling, networking bandwidth, storage throughput, and orchestration—not just a GPU or AI label.
- Assess geography. Review latency, data sovereignty, local permitting, fiber, power availability, disaster-recovery distance, and regional resilience.
- Review reliability. Examine redundancy, maintenance procedures, service-level commitments, backup power, disaster recovery, and operational track record.
- Measure energy and water claims carefully. Ask about PUE, cooling method, water consumption, renewable-energy accounting, and whether renewable power is physically supplied or matched financially.
- Compare commercial maturity. Distinguish generally available products from pilots, partnerships, proposed facilities, and future designs.
- Calculate total cost. Include energy, network transit, egress, cross-connects, support, licensing, cooling integration, staffing, migration, and exit costs.
- Check interoperability and lock-in. Consider proprietary hardware, software, cloud APIs, network standards, data portability, and switching costs.
Which companies fit which buyers?
| Use case | Likely fit | Key trade-off |
|---|---|---|
| Fast access to managed AI or cloud compute | AWS, Microsoft, Google Cloud, Oracle, IBM | Speed and managed services versus cost complexity and platform lock-in |
| Very large AI deployment | Nvidia, AMD, Dell, HPE, Lenovo, Supermicro, Arista, VAST Data | Performance requires coordinated compute, network, storage, power, and cooling |
| Global colocation and interconnection | Equinix, Digital Realty, NTT, CyrusOne, Vantage | Global reach and connectivity versus quote-based contracts and longer commitments |
| U.S. colocation or regional capacity | Aligned, Cologix, Flexential, H5, STACK, TierPoint | Regional fit may be strong, but geographic uniformity varies |
| Private or hybrid enterprise infrastructure | Dell, HPE, Lenovo, Nutanix, IBM, NetApp, Pure Storage | More control can mean greater responsibility for operations and capital investment |
| High-density retrofit | Accelsius, Iceotope, JetCool, ZutaCore, Vertiv, Schneider Electric | Thermal gains may require plumbing, integration, training, and maintenance changes |
| Power resilience and facility upgrades | Eaton, Schneider Electric, Vertiv | Facility equipment is configuration-specific and normally sales-led |
| Edge and distributed sites | American Tower, EdgeConneX, Lumen, Scale Computing, TierPoint | Lower latency can increase operational complexity across many locations |
| Infrastructure monitoring | LogicMonitor, Juniper, IBM | Visibility improves operations but requires integration with existing tools |
Pricing and procurement reality
Most products represented on the list do not have a single meaningful public price. Cloud services from AWS, Azure, Google Cloud, Oracle Cloud Infrastructure, and IBM Cloud are generally usage-based, with costs varying by region, instance type, storage, data transfer, support, and contract terms. Official pricing resources include AWS pricing, Azure pricing, Google Cloud pricing, Oracle’s cost estimator, and IBM Cloud pricing.
Recommended Free Tools
Best Value

- MULTIPLE DEVICE COMPATIBILITY: This 3 prong AC power cord with NEMA 5-15P to C19 connector is ideal for servers, UPS, PDUs, and monitors. It delivers stable power for high-performance equipment.
- OPTIMAL POWER CONNECTION: This 15ft heavy-duty 5-15P to C19 replacement power cord 3 prong offers flexibility for device setup. It ensures a secure power connection without limited reach.
- HIGH-QUALITY CONNECTOR: This 3 prong power cable with IEC60320-C19 male connector that plugs into an IEC60320-C20 connector, ensuring a stable connection for PDUs, surge protectors, and more.
- INSTANT POWER SUPPLY: This 14AWG power cord delivers stable, immediate power to servers, UPS, PDUs, and monitors. Ideal for high-demand setups needing reliable, uninterrupted performance.
- ROBUST POWER CORD: This 15ft IEC power cord supports 15A/125V. It provides durable, reliable power and a secure connection for office and industrial equipment with C19 to NEMA 5-15P connectors.
Colocation from Equinix, Digital Realty, CyrusOne, Flexential, Cologix, TierPoint, and Iron Mountain is usually quote-based. Pricing depends on market, cabinet or suite size, committed power, cross-connects, connectivity, redundancy, installation, security, and contract duration. A lower rack rate may not be cheaper after power, network, remote hands, and interconnection are included.
Enterprise servers, AI systems, storage, switches, monitoring, UPS equipment, and liquid-cooling systems are also commonly sold through direct enterprise teams, distributors, integrators, or channel partners. Compare complete configurations and five-year total cost rather than isolated list prices. Official buying pages include Dell enterprise infrastructure, HPE compute, Lenovo servers and storage, Nvidia DGX, NetApp buying options, and Nutanix products.
What the list gets right—and where it is limited
The list correctly illustrates that AI infrastructure is an interconnected market. Compute cannot scale without electricity. Electricity cannot become usable capacity without transformers, switchgear, cooling, and permits. Servers require networking, storage, software, and operational visibility. Colocation and cloud providers need land, fiber, power, financing, and construction capacity.
Its main limitation is that “heat” can reflect announcements as much as delivered results. A large investment commitment, financing package, partnership, or proposed campus may be strategically significant while producing no immediately available customer capacity. Readers should ask whether a claim describes a project announcement, financing, construction, commissioning, or live service.
The list also mixes companies with radically different financial and commercial profiles. A chipmaker sells components or systems; a cloud provider sells metered services; a colocation company sells power and space; a cooling specialist sells equipment or integration; and an infrastructure-software company sells licenses or subscriptions. Their revenues, risks, margins, capital requirements, and customer relationships cannot be compared using the same simple measure.
Other constraints may matter more than headline investment totals: grid interconnection, transformer and switchgear shortages, water access, permitting, local opposition, fiber availability, construction timelines, GPU supply, financing costs, skilled labor, and data-sovereignty rules.
Important qualifications for a 2025 snapshot
This article analyzes CRN’s 2025 feature. By September 2026, company leadership, financing, product availability, facility counts, and operational capacity may have changed. Executive names and headquarters from the original feature are therefore omitted rather than presented as current facts.
Environmental claims also require precision. Renewable-energy matching, power-purchase agreements, renewable-energy certificates, and physical electricity supply are different concepts. A claim that a facility is “matched” with 100 percent clean energy does not necessarily mean the facility receives renewable electricity at every hour.
Bottom line: the hottest opportunity is the complete infrastructure chain
CRN’s Data Center 50 is useful as a map of the companies positioned around the AI-driven buildout, but it is not a definitive leaderboard. The strategically important companies are distributed across the entire stack: cloud platforms and accelerators, servers and storage, networking, colocation, power, cooling, monitoring, and edge infrastructure.
For buyers, the best provider depends on the workload and the constraint. Use public cloud for speed and managed services, colocation for hardware control and interconnection, enterprise vendors for private or hybrid environments, specialist cooling and power companies for dense-facility upgrades, and edge providers for latency-sensitive deployments. The decisive question is not which name appears hottest on a 2025 editorial list; it is which provider can deliver usable, resilient, costed capacity in the required location and time frame.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




