The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Reviewing a bank or card statement? Check these 10 kinds of entries, then contact your bank or card issuer promptly if something appears wrong. This is a practical checklist, not a ranking: there is no source here establishing which errors happen most often. A strange merchant name is not proof of fraud, so compare it with receipts and account records before deciding what to report.
10 bank statement entries worth checking
For any entry you do not recognize, note the statement date, transaction date, amount, and description. Compare those details with receipts, merchant records, transfer confirmations, and activity by other authorized account users.
1. An unauthorized debit, ATM withdrawal, or electronic payment
Check the date and amount against your records. If you did not authorize the transaction, notify your bank or payment provider promptly and follow its dispute process. The U.S. Consumer Financial Protection Bureau (CFPB) advises consumers to notify their bank or credit union right away; reporting time can affect protections and liability for covered electronic transfers. CFPB guidance on unauthorized transactions and missing money.
2. A deposit or transfer that never arrived
Check the sender’s confirmation, expected posting date, destination account details, and whether the money reached another account. Ask your bank to trace the transfer and keep the confirmation. For covered U.S. electronic fund transfers (EFTs), missing or incorrect transfers may qualify for the Regulation E error-resolution process; coverage depends on the account and transaction. Regulation E, § 1005.11.
Free tools Windows power users keep installed
One-click scans. No signup required.
#1 Best Overall
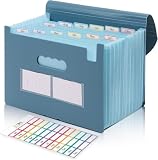
- Large Capacity with 13 Pockets:Designed with 13 expandable pockets, this accordion file folder can hold up to 2000 sheets of A4 or Letter size paper, making it ideal for organizing bills, receipts, invoices, tax documents, medical records, and important files.
- Monthly Tabs & Blank Labels for Easy Organization:Comes with month tabs and blank writable labels, allowing you to organize documents by month or create your own filing system. Easily locate and manage paperwork at a glance.
- Upright Storage Design for Desk, Shelf or Cabinet Use:The structured design allows the file folder to be stored upright on desks, bookshelves, or in filing cabinets, helping keep documents accessible and your workspace organized.
- Expandable Yet Portable:Expands up to 12 inches wide when fully loaded, providing generous storage capacity. When closed, it becomes compact enough to fit into backpacks or briefcases, making it convenient for meetings, school, or travel.
- Durable Waterproof PP Material with Secure Closure:Made from high-quality PP plastic, this file folder is lightweight, waterproof, and durable for long-term use. The adjustable closure design keeps documents secure, even when the folder is fully expanded.
3. A transaction listed twice
Compare both entries’ dates and amounts with your receipt and the merchant’s account history. If they appear to be duplicate charges, contact the bank or card issuer. Bank Negara Malaysia specifically advises customers to contact their bank immediately about a double card transaction. Bank Negara Malaysia’s banking disputes FAQ.
4. A fee that seems incorrect
Check the account’s terms and fee schedule, then ask the bank to explain the charge. If a fee was imposed incorrectly, dispute it through the bank’s process. Bank Negara Malaysia notes that product terms set out fees and charges and that customers may dispute wrongly imposed fees. Bank Negara Malaysia’s banking disputes FAQ.
Rank #2

- Improved Secure Zipper Closure: Unlike folders using elastic bands that can let contents slip out, our expanding file folder features a dependable zipper closure. It's thoughtfully designed to securely store and organize your important documents, including paperwork, bills, taxes, receipts, invoices, and more. Perfect for letter size.
- Large Capacity Monthly Organizer: 12 pockets design works great for monthly organizing and protecting all your essential documents in one place. You can securely store all your important papers without them getting cramped.
- Efficient Organization & Easy Lookup: To enhance your file organization, we provide blank labels along with this folder. You can personalize them to suit your requirements, such as labeling sections by month for effortless file retrieval.
- Additional Zipper Pencil Pouch: The front pocket has a depth of 3.5 inches, making it perfect for use as a pencil pouch to conveniently store pens, highlighters, and other frequently-used writing tools that you may need while working with your documents.
- Portable & Durable: Easily carried in a tote bag or backpack, it makes moving from place to place convenient and reduces the risk of losing items. Made of hard colored plastic with reinforced fabric sides. Waterproof & sturdy enough to keep papers safe. Acid-free, PVC-free, and archival quality for safe storage.
5. A card charge with an unfamiliar merchant name
A billing descriptor may differ from the shop or service name you remember. Check receipts, order history, and whether another authorized user made the purchase. If you still believe the charge was unauthorized, report it to your card issuer. The UK Financial Conduct Authority (FCA) provides guidance for consumers reporting fraudulent payments in the UK. FCA guidance on fraudulent payments.
6. A transaction for the wrong amount
Compare the posted figure with the receipt, order confirmation, or transfer record. Contact the bank or card issuer with the transaction date and both the posted and expected amounts. For covered U.S. credit-card billing errors, the Office of the Comptroller of the Currency (OCC) says written notice should identify the error and provide relevant transaction details. OCC guidance on credit-card charge disputes.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #3

- Check-Size Design: This check-size expanding file is specially designed for coupons organizer. The size of 10" x 5.5" x 1" fits for coupons, receipts or cash size
- Thirteen Pockets: Accordion folder is featuring thirteen pockets with a 6" expansion, that could stands up and expands fully on a desk or counter, contents are easy to access
- Five Colors: Offer five colors for choose, the durable shell and multiple colored pockets make coupons and receipts organized well
- Polypropylene Material: Made of polypropylene material, lightweight and strong, elastic and button closure keeps contents secure, even on the move, perfect for slipping into your purse
- Labels for Organization: Offer adhesive A-Z, Monthly and Blank tab labels to help you locate each pocket for adaptable filing to suit your needs
7. A recurring debit that continued after cancellation
Find your cancellation confirmation and identify each later withdrawal by date and amount. Contact the merchant and your bank promptly to report continued withdrawals you did not authorize. OCC guidance emphasizes prompt reporting of repeated unauthorized electronic charges and checking account-specific terms. OCC guidance on delayed reporting of unauthorized recurring charges.
8. A transfer sent to or from the wrong account, or for the wrong amount
Gather the transfer confirmation and the relevant account details, then tell the institution exactly what differs: destination, amount, or both. Incorrect electronic transfers may fall within Regulation E’s error-resolution framework when the account and transaction are covered. Regulation E, § 1005.11.
Rank #4
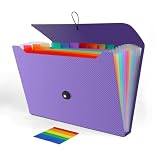
- 【LARGE CAPACITY】With 13 individual pockets and a maximum capacity of 350 sheets of paper, our paper organizer folder is perfect for keeping all your important documents organized and easily accessible.
- 【PREMIUM QUALITY】Made from environmentally friendly PP material, our folder organizer is acid-free, PVC-free, and archival quality, ensuring safe storage for your documents. Plus, it's waterproof and moisture-proof, so your papers stay in great condition.
- 【COLORFUL DESIGN】Our expandable file folder features rainbow-colored inner pages and small colored labels for easy classification, making it both functional and visually appealing
- 【EASY TO USE】The elastic string and button closure to make it easier for you to open and close the folder. This makes your work more relaxed and pleasant, perfect for all people to store all of their loose paperwork.
- 【VERSATILE APPLICATION】Our accordion folders can store invoices, letters, paper, cards, receipts, contracts, and other documents. It's suitable for home, office, school, and travel use. Plus, its stylish and simple design makes it the perfect gift for friends and family.
9. A credit-card billing or calculation error
Identify the specific issue—such as a charge you believe is unauthorized or an incorrect amount—and follow the issuer’s billing-dispute instructions. In the United States, credit-card billing errors are addressed under Regulation Z, a different process from Regulation E disputes involving covered deposit-account EFTs. Regulation Z, § 1026.13; see also the CFPB’s interpretation of § 1026.13.
10. An error that also appeared on an earlier statement
Keep both statements and list every affected transaction by date and amount. Report the issue promptly rather than assuming that a later statement restarts the clock. For covered U.S. EFTs, delay can affect rights; the rules and deadlines depend on the transaction and account.
Best Value

- All-In-One Monthly Organizer: Keep all your important documents in one place with Sooez Accordion File Organizer. 13 pockets design works great for Monthly organizing and protecting all your important paperwork, bills, taxes, receipts, invoices and more. Perfect for letter size.
- Expandable Capacity: The accordion file folder can be stretched up to 12 inches. 13 pockets allow you to store more than 2000 sheets. No matter how many documents you need to store, this folder can accommodate your needs as it can be easily expanded according to your requirements.
- Efficient Organization & Easy Lookup: To enhance your file organization, we provide blank labels along with this folder. You can personalize them to suit your requirements, such as labeling sections by month for effortless file retrieval.
- Stable & Portable: Stand on its own on the desk and not easy to tip over. Designed with portability in mind, allowing you to effortlessly move it between your desk, cabinet, and any other preferred locations.
- Maximum Protection and Durability: Well made, made from durable wipe-clean polypropylene. Waterproof & sturdy. Tear-resistant plastic provides durable structure. Acid-free, PVC-free, and archival quality for safe storage. Adjustable snap closure helps keep contents secure. Use 2 additional front pockets for business cards, project title cards or notes.
How to report a suspected statement error
- Record the details. Note the statement date, transaction date, amount, description, and whether the entry is a deposit, withdrawal, transfer, fee, or card charge.
- Check your own records. Compare the entry with receipts, merchant accounts, transfer confirmations, and activity by other authorized users. Keep copies, and do not send full account credentials in a comment or unsecured message.
- Contact the institution promptly. Use the official app, phone number, or dispute address. For suspected fraud, ask whether your card or account access needs to be secured. Save the report date, any case number, and a record of what the institution says.
- Use the right dispute route. Rules vary by country and by transaction type. In the United States, a covered EFT error and a credit-card billing error follow different frameworks: Regulation E and Regulation Z, respectively. OCC guidance for covered credit-card billing errors calls for written notice with identifying information and relevant transaction details, sent to the issuer’s billing-inquiry address. OCC credit-card dispute guidance.
- Ask about documents and timing. Find out what evidence the institution needs, when it expects to respond, and how to submit additional information. For covered U.S. EFT investigations, CFPB guidance describes a generally applicable initial investigation period of 10 business days, or 20 business days in certain cases involving an account open less than 30 days. If more time is needed, conditional temporary-credit rules may apply. The general resolution period described is 45 days, with listed exceptions that may extend it to 90 days. These U.S.-specific timelines do not apply universally. CFPB guidance on investigation periods.
- Escalate if the issue remains unresolved. Use the institution’s complaint process, then contact the financial regulator or ombudsman that serves your location. The correct channel depends on your country and the product involved.
Which deadline applies?
There is no single deadline for every bank statement dispute. The rules depend on where you live, the account or card, and whether the issue is an unauthorized electronic transfer, an incorrect transfer, or a credit-card billing error. Business accounts, wire transfers, and other arrangements may have different rules from the U.S. consumer guidance cited here.
Covered U.S. electronic fund transfers
For the consumer EFT guidance described by the CFPB, the general notice window for an unauthorized withdrawal is 60 days from the statement being sent that first shows the error. Report suspected unauthorized activity as soon as possible: earlier reporting may matter to liability, including for later transactions. The CFPB guidance, last reviewed August 28, 2026, describes the investigation timelines above. CFPB consumer guidance; Regulation E, § 1005.11.
Covered U.S. credit-card billing errors
OCC guidance last reviewed in April 2021 describes a 60-day period for written notice of a covered credit-card billing error, measured from the first statement showing it and subject to the applicable rules. The notice should include identifying details, what is wrong, and the transaction type, date, and amount, and go to the issuer’s billing-inquiry address. Check the issuer’s current instructions and applicable law. OCC guidance.
Other countries and account types
Do not assume U.S. deadlines or procedures apply elsewhere. Check your account terms and the official guidance for your country; for example, Bank Negara Malaysia’s dispute FAQ and the UK FCA’s fraudulent-payment guidance describe local consumer channels. Bank Negara Malaysia; UK FCA.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




