
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Before taking a laptop to a hilly or mountainous destination, verify that your travel policy covers the trip’s purpose, duration, work activities, planned route, highest altitude and level of remoteness. Then check emergency medical treatment, search and rescue, evacuation and repatriation as separate benefits, including their limits, exclusions and pre-approval rules.
There is no reliable universal price for a mountain rescue. Your financial exposure depends on the country, route, distance to definitive care, rescue provider, transport method, medical needs and the policy’s authorization conditions. A benefit limit is the insurer’s maximum payment under stated terms, not a prediction of the bill.
As an Amazon Associate I earn from qualifying purchases.
Start with an itinerary-specific policy check
A policy that covers ordinary holidays may not cover a remote worker’s actual trip. “Working remotely” can change eligibility, and a hike taken between workdays can activate activity or altitude exclusions. Use the exact itinerary when asking an insurer for a written answer.
Confirm the purpose and duration of travel
Check whether the policy permits leisure travel, overseas work, or a combination. Read the eligibility rules for your country of residence, destination, trip length and the type of work you will perform. Ask specifically whether manual work, field work, carrying equipment or work in an exposed location is classified as hazardous. A policy document titled Working Overseas is still only one insurer’s wording; it cannot establish the terms of another insurer.
#1 Best Overall

- Small, rugged, lightweight satellite communicator enables two-way text messaging even in areas with no cell coverage (Active satellite subscription required. Some jurisdictions regulate or prohibit the use of satellite communication devices)
- Send two-way messages globally; easily text back and forth directly with friends via the Garmin Messenger app, even when you’re out of cellular coverage. (Active satellite subscription required. Some jurisdictions regulate or prohibit the use of satellite communication devices.)
- Group messaging via the Garmin Messenger smartphone app lets you share your adventures with multiple contacts simultaneously — and have group text chats with friends and family
- Check in with contacts directly by using preset messages that do not count toward your allotted text messages (Active satellite subscription required. Some jurisdictions regulate or prohibit the use of satellite communication devices)
- Share your GPS location (Active satellite subscription required. Some jurisdictions regulate or prohibit the use of satellite communication devices)
Write down the route and the highest point
List every planned trail, pass, overnight stop and day with a significant ascent. Record the maximum altitude in metres, not just the name of a region. Also note whether you expect to use ropes, crampons, an ice axe, climbing equipment, oxygen or a guide. These details let the insurer assess the activity rather than relying on a broad label such as “hiking.”
Why activity and altitude wording matters
Insurance definitions can draw lines that are invisible on a travel website. In Southern Cross Travel Insurance’s Working Overseas wording, mountaineering, hiking, trekking or tramping is described as excluded when a reasonable person would use climbing equipment or oxygen above 3,000 metres. The same wording describes an exclusion between 1,500 and 3,000 metres when climbing, or intending to climb, more than 500 metres in a day. Those thresholds apply to that particular policy and version, not to travel insurance generally.
| Example wording | What it means for planning | What to ask |
|---|---|---|
| Above 3,000 metres where climbing equipment or oxygen would reasonably be used | A route described casually as a trek may fall into a mountaineering exclusion. | Is this exact route and equipment covered, and under which activity category? |
| 1,500–3,000 metres with more than 500 metres of ascent in one day | A lower-altitude itinerary can still trigger an ascent-based condition. | How is daily ascent measured, and does the limit apply to planned or actual ascent? |
| Any other stated altitude or activity cap | Another policy may use different numbers or definitions. | Can the insurer confirm the maximum covered altitude in writing? |
Do not infer cover from a destination’s average elevation. A valley hotel, a high pass and a summit attempt can be treated as different risks on the same trip. Keep the policy schedule and full wording together, because a summary page may not show the conditions that apply to altitude, equipment or daily ascent.
Remote areas create a separate communications and medical-access risk
Limited phone service can affect both the practical rescue process and whether a policy responds. The Southern Cross example lists “Any touring in an area with limited or no telecommunications or medical services” under “E.26 Remote touring.” It states an exception for travel as part of a licensed organised tour. This is policy-specific wording, not a market-wide rule, but it shows why the exact location and communications access must be disclosed.
Questions to put to the insurer
- Is the planned base, trail or hut considered a remote area under the policy?
- Does intermittent mobile coverage affect eligibility, or only the method of requesting assistance?
- Is an organised-tour exception available, and what makes a tour “licensed” for this purpose?
- Which assistance number or service should be used when the local network is unavailable?
- What happens if weather or terrain prevents an immediate response?
Ask for answers that refer to your route and dates. A general statement that the policy includes “adventure activities” is not enough if the same contract excludes remote touring or limits evacuation to approved providers.
Separate the emergency benefits instead of looking for one rescue number
Emergency medical treatment, search and rescue, evacuation and repatriation solve different problems. They may have separate limits, definitions and approval requirements.
Rank #2

- SYNC WITH BLUETOOTH: Connect to SpotX to cellphone so you can communicate with family or even search and rescue; Use as a standalone communication device with it's own dedicated US mobile number to receive messages
- PEACE OF MIND: Send S.O.S. to 24/7 Search & Rescue service, message back and forth about the nature of your emergency, receive confirmation when help is on the way; Message any cell number or email address virtually anywhere
- GLOBALSTAR SATELLITE & SPOT products use GPS to determine location and transmit GPS coordinates to others; SPOT users can notify friends, family or emergency rescue their exact GPS coordinates
- WHAT'S IN THE BOX: SpotX Device, strap and carabiner, micro usb data/power cable, quick start guide, SOS mirrored sticker, warranty card and kickstand
- PURCHASE, ACTIVATE, EXPLORE: Grab a Spot X 2-way Satellite Messenger; Activate by selecting your service plan; Get out there and explore the world with peace of mind
| Benefit to check | Typical expense it addresses | Important conditions |
|---|---|---|
| Emergency medical expenses | Doctor visits, hospital treatment, medicines and medically necessary care after an injury or illness. | Check the monetary limit, excess, pre-existing-condition rules and whether treatment must be approved. |
| Search, rescue or recovery | Locating and recovering a person from terrain, including specialist teams where the policy includes them. | Confirm that the benefit is separate from medical cover and applies to the activity and altitude. |
| Emergency evacuation | Transport from the incident or first treatment site to suitable medical care, potentially including a helicopter. | Ask who authorizes evacuation, which providers may be used and whether transport is direct-paid or reimbursed. |
| Onward transfer | Moving from a small clinic or local hospital to a facility able to provide definitive treatment. | Check whether this is included in evacuation or treated as a separate limit. |
| Repatriation | Returning you to your home country when medically necessary. | Look for medical-director approval, escort requirements and destination restrictions. |
| Trip interruption or cancellation | Unused travel costs or extra transport after a covered medical emergency. | Check evidence requirements and whether the triggering event must be an insured emergency. |
The British Mountaineering Council (BMC) publishes an example of specialist cover with £10 million of emergency medical cover and £100,000 of search, rescue and recovery insurance. Those are the BMC’s stated benefit amounts, not a rescue price, a legal minimum or a recommendation for every itinerary.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →How specialist policies divide hill and mountain activities
Specialist insurance may classify activities more precisely than a standard travel policy. The BMC describes separate categories rather than treating every mountain trip alike.
| BMC category description | Activities and altitude described | How to use the information |
|---|---|---|
| Trek | Hill walking, trekking and backpacking up to 5,000 metres. | Check whether your route fits the named activity and stays below the stated ceiling. |
| Rock | Climbing and graded scrambling up to 5,000 metres. | Confirm the grade, equipment and whether solo travel changes eligibility. |
| Alpine and Ski | Trekking above 5,000 metres and specified activities up to 6,500 metres. | Read the specified-activity list; altitude alone does not establish cover. |
| High-altitude and remote | More inaccessible and difficult expeditions. | Ask whether the itinerary requires this category and what rescue arrangements apply. |
These categories illustrate one insurer’s structure. They are not a universal classification system. When comparing another policy, use its own definitions and ask about the highest point, technical equipment, guide arrangements and remoteness.
How to compare policies using the same facts
Obtain quotes or confirmations with identical itinerary information. Changing the description from “trekking” to “holiday” can produce a misleading comparison.
- Describe the trip. State your residence, destination countries, dates, work purpose, accommodation, route, highest altitude and expected daily ascent.
- Name every activity. Include hiking, trekking, scrambling, climbing, skiing, snow travel, cycling or any activity you may try spontaneously.
- Disclose access conditions. Identify sections with no mobile coverage, no local clinic, long vehicle approaches or weather-dependent aircraft access.
- Compare activity and altitude limits. Record exclusions, equipment rules, daily-ascent conditions and whether a guide or organised tour is required.
- Compare each emergency benefit. Put medical treatment, search and rescue, helicopter evacuation, onward transfer and repatriation in separate rows.
- Check the assistance process. Ask whether the insurer must approve a rescue or transport before it begins, how to proceed if contact is impossible and which providers are accepted.
- Review personal eligibility. Confirm trip duration, destination exclusions, pre-existing medical conditions, residence requirements and any age or membership conditions.
- Save evidence. Keep the policy wording, schedule, assistance number, itinerary and written answers offline and with a travel companion.
What “mountain rescue cost” can and cannot mean
The sources available do not establish a comparable price for a specified route and incident. A helicopter extraction in one country cannot be used as a benchmark for a ground recovery in another. Distance, weather, terrain, provider availability, local regulation, medical treatment and the need for onward transport can all change the amount charged.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsPlan for two separate figures: the provider’s possible charge and your policy’s payable amount. The first is unknown until the incident and local arrangements are known. The second is limited by the contract and may be reduced to zero if an exclusion applies, authorization was not obtained where required, or the service used is outside the policy’s approved process.
Rank #3

- Lightweight SOS satellite communicator uses the global Iridium satellite network so you can stay connected without cell coverage (active satellite subscription required; some jurisdictions regulate or prohibit the use of satellite communication devices)
- Explore with peace of mind knowing you can trigger an interactive SOS message with location coordinates to Garmin Response℠, a 24/7-staffed international coordination center, for help in an emergency (active satellite subscription required; some jurisdictions regulate or prohibit the use of satellite communication devices)
- Exchange photos, texts and voice messages without cell service; taking and sending photos requires pairing your inReach device with your compatible smartphone by using the Garmin Messenger app (active satellite subscription required; some jurisdictions regulate or prohibit the use of satellite communication devices)
- Rugged design features a high-resolution and scratch-resistant color touchscreen; can withstand impact, extreme weather and harsh temperatures (IP67 water rating)
- Internal, rechargeable lithium battery supports up to 350 hours with 10-minute inReach tracking and up to 95 hours in performance messaging mode
Questions about payment before departure
- Will the assistance company arrange and pay the provider directly, or must I pay and claim reimbursement?
- Is a deposit or card guarantee required before a helicopter or vehicle is dispatched?
- Which rescue organisations and hospitals are recognised?
- Does the search-and-rescue limit sit inside, or in addition to, the emergency-medical limit?
- What happens when the insurer cannot be reached because there is no signal?
- Can a companion authorize urgent transport if I am incapacitated?
Record the answers. A verbal assurance from a sales representative may not override a written exclusion or an approval condition.
Pre-approval can affect evacuation decisions
The Mountain Company advises trekkers to confirm helicopter evacuation cover and warns that a general policy’s pre-approval process may delay an evacuation decision. This is operator guidance, not a guarantee that another insurer will act the same way. Ask the insurer and assistance service what qualifies as an emergency, who makes the medical decision, and whether a local doctor, pilot or rescue coordinator can start transport when central approval is temporarily unavailable.
If the policy requires prior authorization, learn the exception for situations where delay would endanger life. Also ask how the claim must be documented: names of treating clinicians, incident reports, receipts, GPS records or proof of route may be requested later.
Recommended Free Tools
Communications planning: where a satellite messenger fits
A satellite messenger may be worth investigating for a route with little or no mobile coverage. This is a practical communications option, not evidence that rescue is available, that an insurer will pay, or that a particular device will perform everywhere.
- Check satellite coverage for every country and valley on the itinerary.
- Confirm the subscription, activation period and emergency-service procedure.
- Carry spare power, a charging method and a weather-resistant storage case.
- Tell a trusted person your check-in schedule and escalation plan.
- Learn the local emergency number and the policy’s assistance route; a device does not replace either one.
Test the device before departure and explain its use to companions. In an emergency, provide coordinates, injury details, number of people, weather and visible landmarks, then follow instructions from the responding service.
Build a personal emergency-cost plan
Insurance is one layer of preparation. Before leaving, keep an accessible payment method for unavoidable expenses such as transport to a clinic, food during an unplanned delay, replacement medication or a hotel night while assistance is arranged. Set a realistic card limit, tell your bank that you will travel, and store emergency contacts offline.
Rank #4
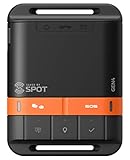
- MEANT FOR ADVENTURE: Spot Gen4 provides critical, life-saving line of communication when you travel beyond cell towers; Let family know you're ok or push the SOS button to send your GPS to emergency responders if you need help
- NO CELL PHONE OR SERVICE-NO PROBLEM: With the Tracking feature Gen4 can transmit location updates when you are moving and when you stop; Keep one in your child's backpack for the walk home
- GLOBALSTAR SATELLITE & SPOT products use GPS to determine location and transmit GPS coordinates to others; SPOT users can notify friends, family or emergency rescue their exact GPS coordinates
- WHAT'S IN THE BOX: SPOT Gen4 device, Strap and Carabiner, USB Cable, Batteries and quick start guide; Subscription required; Two service plans available
- PURCHASE, ACTIVATE, EXPLORE: Grab a Spot Gen4; Activate by selecting your service plan; Get out there and explore the world with peace of mind
Do not assume that an employer’s health plan, credit-card travel cover or local public rescue service will pay for a remote incident. Ask each provider for its territorial limits, activity exclusions and claims process, then treat any overlap as supplemental rather than a substitute for a policy that explicitly covers your itinerary.
A simple pre-departure file
- Policy schedule and full wording, with the relevant activity and altitude sections marked.
- Written confirmation of work, activity, altitude and remote-area eligibility.
- Assistance phone numbers, email addresses and instructions for no-signal situations.
- Passport, visa, emergency-contact and medical-information copies.
- Route map, lodging details, check-in schedule and local rescue contacts.
- Payment cards and an emergency cash reserve stored separately.
Common mistakes and how to correct them
Calling a technical route “just a hike”
Problem: The insurer evaluates the actual equipment, exposure or ascent rather than the casual label. Correction: Describe the hardest day, equipment and maximum altitude in writing.
Checking only the medical limit
Problem: A large medical limit may not include search, recovery or helicopter transport. Correction: Compare each emergency benefit separately and note its own exclusions.
Assuming no phone signal is only an inconvenience
Problem: Some wording treats remote touring with limited telecommunications or medical services as an exclusion. Correction: Ask about the exact area and any organised-tour exception before paying for the trip.
Starting an evacuation without understanding authorization
Problem: The policy may require approval or use of designated providers. Correction: Obtain the emergency procedure and ask what to do when delay or a failed connection makes prior approval impossible.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Using a benefit limit as a budget estimate
Problem: £100,000 of search-and-rescue cover does not mean a rescue will cost £100,000 or that every charge is payable. Correction: Treat the limit as a contractual ceiling and plan for deductibles, exclusions, reimbursement timing and uncovered costs.
Bottom line for a remote worker in the hills
Buy or confirm cover against the itinerary you will actually undertake: remote work, route, activity, equipment, maximum altitude, daily ascent and communications access. Verify emergency medical care, search and rescue, evacuation, onward transfer and repatriation independently, and understand who must authorize transport. No source establishes a universal mountain-rescue price, so the financially sound approach is to reduce uncertainty with written policy confirmation, an assistance plan, backup communications and accessible funds for costs that may arise before an insurer can respond.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




