
Recommended Free Tools
If a mortgage payment appears late, short, credited to the wrong loan, or applied to the wrong part of your account, first preserve your payment proof and compare it with the servicer’s statement and transaction history. Then ask the mortgage servicer to investigate, and send a formal written notice of error if the problem is not corrected.
The company that receives and manages your payments is usually the servicer; it may be different from the lender named in your closing documents. The steps below are designed for a suspected payment-application error without assuming that every posting difference is a legal violation.
As an Amazon Associate I earn from qualifying purchases.
First, determine what actually happened
A payment can look wrong for several reasons. The servicer may have posted it on the wrong date, credited the wrong amount, applied it to a different loan or borrower, or allocated it differently among principal, interest, escrow and permitted charges. A servicing transfer can also put the payment with the wrong company temporarily.
Before disputing the account, assemble the records that show what you instructed and what the servicer recorded.
#1 Best Overall
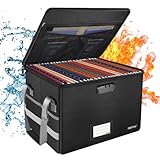
- Fireproof and water-resistant: Fireproof lock box is made of double layered non-itchy silicone coated fiberglass which stands up the temperature up to 2000℉.It has passed the UL94 -V0/5VA flame retardant test.Fireproof file box is not only fireproof but also high water resistant in case it gets wet for any reason.Nothing is completely foolproof, but added protection is always a good idea.
- Anti-static and reflective strip design:Are you still worried about the storage box is often covered with dust? The anti-static material can prevent dust from sticking to the outside of our fireproof box, always keep it neat and tidy.The reflective strip design on the side of the box allows you to immediately find your fireproof box even at night, protecting irreplaceable documents and valuables from fire.
- Portable and secure: High quality combination lock design for added storage security, includes instruction manual for combination lock. Sturdy adjustable handle makes it easy to carry everything you need(You can adjust the carrying handle to the length you want), two zippers make it easier to open and close the box, Side pockets and label slots let you store small items and labels.The file lock box collapses down simply for easier storage when not in use.
- Dimensions: 15.55" x 12.2" x 10".The fireproof lock box fits both letter and legal size files fitting your filing system,it also can protect your important documents,books,CDs, DVDs,USBs,albums,passports, social security cards,birth certificates and other valuables.Combining our fireproof bag and fireproof safe box together is the best solution to offer your documents and valuables a complete protection in any fire accident.
- Trusted after sales service:How can we better protect our valuables from any fire? ENGPOW keep researching and developing on fireproof materials,safety technology.We only wish to present the best to customers,to protect your valuables.If there any quality problem, please feel free to let us know.We promise to arrange a REPLACEMENT or 100% REFUND immediately. Ready to respond within a 24 hour time,your suggestion has a great impact on the upgrade of our products.
- Your bank statement, online-bank confirmation or bill-pay receipt showing the date and amount sent.
- A canceled check, electronic payment confirmation or servicer receipt, if available.
- The mortgage statement for the period in question.
- The payment history or transaction detail available through the servicer’s website or by request.
- Any transfer notice, payment coupon, email or letter that changed where payments should be sent.
Check whether the payment was made through a bill-pay service that mails a check rather than sending an electronic transfer. The date your bank debited the money, the date the servicer received it and the date the servicer posted it can differ. Those dates may explain a discrepancy, but you should ask the servicer to identify the dates it used.
Ask for the account history and a corrected statement
Compare the amount you sent with the amount credited and examine the allocation. A payment may be divided among interest, principal, escrow and charges under the loan documents. Ask the servicer for the transaction history showing each posting and for a corrected statement if the statement remains inaccurate. Consumer Financial Protection Bureau guidance says mortgage statements include account and payment-application information and suggests requesting a corrected statement when a suspected error is not resolved by phone.
Contact the mortgage servicer and create a record
Use the telephone number and mailing address printed on your latest statement or coupon book. Explain the specific transaction: the payment amount, the date you authorized or sent it, the account number, and what the statement shows instead. A phone call can resolve a simple posting mistake quickly, but treat it as an initial step, not your only record.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →During the call, record:
- The date and time.
- The representative’s name or identification number.
- What the representative said happened.
- Any correction promised and when it should appear.
- The call or case reference number.
After the call, save a screenshot or download of the account page if the posting changes. If the representative cannot explain the discrepancy, or the correction does not appear, move to a written notice of error.
Send a formal written notice of error
Regulation X provides a process for notifying a servicer about certain servicing errors, including payment-application problems. The notice should be clear enough for the servicer to identify the account and investigate the exact transaction.
Rank #2

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
What to include
- Your name and enough information to identify the mortgage account, such as the property address and loan number.
- The payment date, amount and method of payment.
- A concise description of the suspected error: for example, “the $2,000 payment sent on May 1 was credited on May 12,” “only $1,500 was credited,” or “the payment was applied to escrow instead of the scheduled installment.”
- Copies, not originals, of relevant proof such as a bank confirmation, canceled check, statement or receipt.
- The correction you are requesting, such as accurate posting, removal of an improper late charge, an updated payment history or a corrected statement.
Do not write the notice on a payment coupon or rely on a message in the ordinary payment portal unless the servicer specifically identifies that channel for notices of error. Look on the statement or the servicer’s website for a separate address for “notices of error” or “qualified written requests.” That address may be different from the address used to send payments.
Send it in a way you can prove
Keep a complete copy of the letter and every enclosure. Use a delivery method that provides a receipt or tracking record, and retain the delivery confirmation. If you send the notice electronically through a designated channel, save the submission confirmation and the exact text sent. A clear timeline—sent date, delivery date, acknowledgment date and response date—will help if you later escalate the matter.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteSample wording
You can adapt this structure to your facts:
Subject: Notice of Error — Mortgage account [account identifier]“I believe the servicer made an error in applying my mortgage payment of $[amount], sent on [date]. The payment was [describe the discrepancy]. Enclosed are copies of [payment proof and statement]. Please investigate, correct the account, remove any resulting improper charge, and provide an updated transaction history and statement. Please send your response to the address below.”
Use the servicer’s designated address and identify the property and account precisely. Do not include accusations you cannot support; describe the records and the correction you seek.
Keep making scheduled payments
Sending a notice of error does not cancel the underlying loan obligation. Continue making the regular payments required by the mortgage, using the instructed payment method and address, while the servicer investigates. Keep proof of every payment.
Rank #3

- High-Quality Materials: Protect your files with ENGPOW fireproof accordion file organizer.It is made of 3-layered non-itchy silicone-coated fiberglass which withstand the temperature up to 2200℉.It has passed the UL94 -V0/5VA flame retardant test.Fireproof File Folder is fireproof&Water-resistant,which can effectively protect your important documents in a fire,flood,and wet weather. They will further keep your files intact.Giving you time to save your important documents when disaster strikes
- Accordion File Organizer: A Safe Enough Folder to Keep Your Files. Say goodbye to cluttered files and disorganization with ENGPOW's file organizer folders. Compared with other folders,our fireproof folders is allows you to neatly store and classify letter/A4 files, receipts, cards, USB drives, pen, passports and more in a safe and orderly way. Perfect for daily file filing and storage.The Non-dusty material can prevent dust from sticking to the outside of our folder,always keep it neat and tidy.
- Large Capacity: 14.2" x 10.4" x 2", Compared with other folders, our Accordian File Organizer adopts a multi-layer design that can meet all your storage needs.These include 13 accordion Pockets with labels(each expanding to 1.2 inches),1 zipper pocket,2 pen slot,6 card slots,4 small mesh bags,4 medium mesh bags,and 1 main pocket. You can securely store all your important documents and other items in this fireproof expanding file folder while effectively classifying and finding your files.
- Innovative Humanized Design: Design with a strong grab handle for carrying everything you needed easily. Featuring a double zipper for convenient opening and closing,you won't have to worry about losing any important documents. The included colorful labels make categorizing your files effortless. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place.
- Trusted after sales service: In the event of an emergency, our fireproof accordion file organizer folders are lighter, easier to carry than fireproof safes and quick to grab and go. We only wish to present the best to customers,to protect your valuables.If there any quality problem, please feel free to let us know.We promise to arrange a REPLACEMENT or 100% REFUND immediately. Ready to respond within a 24 hour time,your suggestion has a great impact on the upgrade of our products.
Regulation X says a servicer may not demand a payment or fee as a condition of responding to a notice of error. The Consumer Financial Protection Bureau’s current language in 12 CFR § 1024.35(h) states: “A servicer shall not charge a fee, or require a borrower to make any payment that may be owed on a borrower’s account, as a condition of responding to a notice of error.” This rule concerns the servicer’s response process; it does not waive scheduled payments or authorize you to stop paying.
Free tools Windows power users keep installed
One-click scans. No signup required.
Know the response deadlines
For a general notice of error, the servicer generally must acknowledge receipt within five business days. For most covered errors, the usual deadline for a substantive response is 30 business days after receipt.
For most errors, the servicer may extend that response period by up to 15 business days only if it sends written notice before the initial 30-business-day period ends and explains the reason for the extension. Some error categories have different rules, so 30 days is not an absolute deadline for every situation. Count from the date the designated address receives your notice, not necessarily the date you place it in the mail.
| Milestone | General timing | What to preserve |
|---|---|---|
| Receipt acknowledgment | Within 5 business days | Servicer acknowledgment and reference number |
| Substantive response for most covered errors | Within 30 business days after receipt | Written findings, correction or explanation |
| Possible extension for most errors | Up to 15 additional business days | Advance written notice and stated reason |
If no acknowledgment arrives after five business days, or no substantive response arrives after the applicable period, organize your delivery proof and contact the servicer again in writing. You may also submit a complaint to the Consumer Financial Protection Bureau.
Understand the limited credit-reporting protection
For 60 days after the servicer receives a qualifying notice of error, the servicer generally may not furnish adverse information to a consumer reporting agency about the payment identified in that notice. This protection is narrow. It applies to the disputed payment, not every account issue, and it does not erase your ordinary duty to make payments or prevent reporting about unrelated matters.
Rank #4

- Expanding file folder in Black with flap and cord closure for organizing and securing 8.5 x 11-inch letter-size documents
- Holds up to 260 sheets; 13 pockets for easy subdividing; each pocket expands to 7/8-inch
- Archival quality, acid free, and PVC free
- Waterproof and tear resistant
- Made of durable poly material
Make the disputed payment unmistakably identifiable in your notice. If you later see adverse information about that same payment, retain the credit-report entry, your notice and delivery evidence when asking the servicer to correct the reporting.
If the error happened during a servicing transfer
Read the transfer notice to determine when the old servicer stopped accepting payments and when the new servicer took over. Identify which company had responsibility when your payment was sent and which company now holds the account history.
For 60 days after a servicing transfer, a new servicer generally may not charge a late fee or treat a payment as late when you sent it to the old servicer on time or within the applicable grace period. This protection concerns qualifying payments sent to the former servicer; it does not mean every transfer-related dispute is automatically resolved.
When a transfer is involved, send an information request or notice of error to the appropriate servicer using its designated address. You may need to contact both companies: the former servicer to document receipt and forwarding, and the new servicer to correct the account history. Include the transfer notice, payment proof and dates each company had servicing responsibility.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Escalate when the account is not corrected
Submit a CFPB complaint
If the servicer does not acknowledge or answer your notice, gives an explanation that conflicts with your records, or leaves the account uncorrected, you can submit a complaint to the Consumer Financial Protection Bureau online or by phone. Attach a concise timeline and copies of the payment proof, statements, notice of error, delivery record and the servicer’s response. Keep the originals.
Best Value

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
Consider a HUD-approved housing counselor
The CFPB also points borrowers to HUD-approved housing counselors. A counselor can help you organize the account history, understand the servicer’s response and identify next steps. Treat counseling as assistance with the process, not as a replacement for making payments or obtaining legal advice when a legal deadline is approaching.
Get legal help for foreclosure or court deadlines
If you have received foreclosure papers, a summons, a complaint, a sale notice or another document with a response deadline, consult a qualified attorney promptly. A generic payment-dispute letter does not substitute for responding to an active court case or foreclosure timetable. Bring the complete payment and servicing file to the consultation.
Choose the right evidence for the payment method
| Payment method | Useful proof | Detail to verify |
|---|---|---|
| Online bank transfer | Bank confirmation and account statement | Authorization date, debit date, amount and destination |
| Bank bill-pay service | Bill-pay confirmation, delivery status and canceled check when available | Whether the bank mailed a check or sent an electronic payment |
| Paper check sent to the servicer | Check image, tracking or delivery receipt and bank statement | Payee, mailing address, amount and date received |
| Servicer payment portal | Confirmation page, email receipt and account screenshot | Confirmation number, posting date and amount credited |
Keep statements, correspondence and delivery records together in a dated folder—digital, paper or both. A simple index listing each payment, the proof you have and the servicer’s posting makes inconsistencies easier to show. File organization is a convenience, not a legal requirement.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchCommon mistakes to avoid
- Sending the dispute to the payment address. A notice sent to the wrong address may not receive the formal handling you expect. Use the special address listed for notices of error or information requests.
- Describing only a general complaint. “My account is wrong” is less useful than identifying the exact payment, date, amount and requested correction.
- Stopping payments. The dispute process does not suspend the mortgage obligation.
- Relying on a phone promise. Record the call, then create a written record when the issue remains unresolved.
- Sending original documents. Keep originals and send copies or secure electronic records.
- Assuming every posting difference proves a violation. First determine whether the difference reflects allocation rules, receipt timing, a transfer or an actual servicing error.
- Waiting during an active foreclosure. Escalate immediately to legal help when court or sale deadlines are involved.
A practical decision path
- Compare your payment proof, statement and transaction history.
- Ask the servicer for an explanation, detailed history and corrected statement if needed.
- Document the call and save the reference number.
- If unresolved, send a specific notice of error to the designated address, with copies of proof and delivery tracking.
- Continue making scheduled payments and preserve proof.
- Calendar five business days for acknowledgment and the applicable response deadline, usually 30 business days for most covered errors.
- If the response is missing or inadequate, file a CFPB complaint and consider a HUD-approved counselor.
- If foreclosure or court papers are involved, obtain legal advice immediately.
The strongest dispute is specific, documented and timely: it identifies one payment, shows what the records establish, uses the servicer’s required address and preserves evidence of every contact.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




