
Recommended Free Tools
If an insurer delays or rejects your claim, first determine whether it is still pending or has been formally denied. Read the policy, plan, explanation of benefits (EOB), estimate, and every letter; record the date you received each notice and the deadline it gives you. Then ask the insurer, in writing, what information is missing, which policy or plan provision supports its position, and when it will make the next decision. Keep a dated record of every contact. If the explanation is wrong or incomplete, use the policy’s appeal or reconsideration process before the deadline. If the insurer does not respond or correct the problem, complain to your state insurance department. Health-plan denials have additional internal and external review routes, with deadlines that differ from those for auto, homeowners, life, disability, or travel policies.
Start by identifying the claim’s exact status
“Delayed” and “denied” require different actions. A pending claim may need a document, inspection, medical record, estimate, or proof of loss. A final denial requires a written challenge under the policy or plan. Do not assume that silence is a denial, and do not let a pending conversation cause you to miss an appeal deadline printed on a notice.
As an Amazon Associate I earn from qualifying purchases.
Collect the controlling documents
- The insurance policy, certificate, or health-plan booklet, including endorsements and amendments.
- The claim number, policy or member number, and date of loss or service.
- Every denial letter, status letter, EOB, bill, estimate, explanation, and appeal instruction.
- Any deadline, address, portal, fax number, or form specified for an appeal or complaint.
Write down the date each notice arrived, not merely the date printed on it. Scan or photograph documents and keep originals unless the insurer specifically requires an original. A free digital folder, paper binder, or accordion file can keep notices, bills, records, photographs, estimates, and call notes together.
Free tools Windows power users keep installed
One-click scans. No signup required.
Ask the insurer for a precise explanation
Use the telephone number or address on the notice or policy. Ask whether the claim is pending, partially paid, or finally denied. Request the answer in writing, even if a representative explains it by phone. Ask these questions:
#1 Best Overall
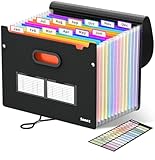
- Superior Durability: Featuring strong 100C thickened cover and reinforced edges, surpassing competitors in durability. Made from PVC-free, acid-free materials, ensuring secure organization of bills and documents while delivering unparalleled durability and reliability
- Deeper Pockets & Unobstructed Tabs: In response to a common issue in accordion folders where papers cover index labels, we've increased pocket height by 0.8 inches (2 cm). This unique enhancement ensures your labels remain visible—a feature unmatched by competitors
- Ample Capacity Monthly Bills Organizer: Our expandable monthly bill organizer can extend up to 14 inches, accommodating over 1500 sheets files while standing stable. With 12 pockets, it's perfect for storing tax records, bills, receipts, invoices and important family files for over a year
- Sticky Labels & 3 Loops Bungee Closure: Colorful monthly tabs and labels help you locate the target object at a glance and manage monthly tasks with ease. The elastic band closure with three loops expands generously to accommodate all your storage needs
- Unlock Versatile Organization: Whether at home, in the office, or on the go, it offers flexible organization for invoices, medical finance records, and identification documents, ensuring efficiency wherever you need it
- What exact information or action is missing?
- What policy, endorsement, exclusion, plan term, or coding rule supports the decision?
- Which documents will satisfy the request, and where should they be sent?
- Who is responsible for the next review, and on what date should I expect a response?
- Is this a final adverse decision with an appeal deadline, or can the claim be corrected administratively?
A simple billing or coding error may be fixed by the provider or insurer without a full dispute, but protect the formal appeal deadline while that correction is being investigated. Use a script such as: “My claim is still pending. What information is missing, and when will you decide?” For a denial, ask the representative to identify the exact sentence in the policy or plan that was applied.
Build a chronology and evidence file
Regulators and appeal reviewers can understand a dispute more quickly when the facts are chronological. For every interaction, record the date, time, channel, representative’s name or identifier, questions asked, answers given, promised next step, and promised date. Save confirmation numbers, portal screenshots, delivery receipts, and copies of anything submitted.
Match evidence to the reason given
- Missing information: send the requested record, invoice, estimate, proof of ownership, or proof of submission and state exactly which request it answers.
- Coverage exclusion: quote the relevant coverage and exclusion language, then explain why the facts do or do not fit it.
- Medical necessity or experimental-treatment decision: obtain a clinician’s letter, treatment notes, test results, and published medical rationale that address the plan’s criteria.
- Amount disputed: provide itemized bills, repair estimates, photographs, receipts, valuations, or evidence of the applicable deductible and limits.
- Late notice or proof of loss: show when you notified the insurer, why any delay occurred, and the documents that establish the loss.
Send copies and retain originals. Put the claim number on each page, use the submission method specified in the notice, and ask for written confirmation that the material was received.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →File a written appeal or reconsideration
For any insurance line, follow the policy’s stated appeal, reconsideration, appraisal, proof-of-loss, or lawsuit limitation provisions. Your letter should identify the policyholder, claim number, date of loss or service, and the decision being challenged. State the result you want, address each reason in the denial point by point, quote the applicable policy or plan wording, and list the attached evidence. Keep a complete copy and proof of timely delivery.
Rank #2

- Expanding file folder in Black with flap and cord closure for organizing and securing 8.5 x 11-inch letter-size documents
- Holds up to 260 sheets; 13 pockets for easy subdividing; each pocket expands to 7/8-inch
- Archival quality, acid free, and PVC free
- Waterproof and tear resistant
- Made of durable poly material
Suggested appeal structure
- Opening: “I request reconsideration of the decision dated [date] for claim [number].”
- Requested outcome: state the payment, coverage, correction, or reprocessing sought.
- Reason-by-reason response: use a separate paragraph or heading for every denial reason.
- Evidence index: identify each attachment and the fact it proves.
- Deadline and contact: note the notice date, appeal deadline, preferred response method, and address.
Do not send an emotional narrative in place of evidence. A short, factual chronology tied to policy language is easier to evaluate and gives a regulator a clear record if the dispute continues.
Health insurance has a separate appeal system
Health-plan denial notices should explain the reason, the internal appeal method, and whether external review is available. The plan’s instructions control how you submit the request. Job-based plan participants can also seek help from the U.S. Department of Labor’s Employee Benefits Security Administration; many states operate Consumer Assistance Programs, and a state insurance department may provide guidance.
Internal appeal deadlines and decision times
HealthCare.gov’s current guidance, issued by the U.S. Centers for Medicare & Medicaid Services and accessed in 2026, generally gives you 180 days after receiving a denial notice to request an internal appeal. Confirm the exact deadline and method in your notice and plan documents.
| Internal review situation | General decision period | Qualification |
|---|---|---|
| Care not yet received | 30 days | HealthCare.gov general guidance; plan and governing rules control. |
| Services already received | 60 days | HealthCare.gov general guidance; verify the notice. |
| Urgent care | As fast as medical circumstances require | Request expedited review when delay could seriously jeopardize life or the ability to regain maximum function. |
Your internal appeal should include the plan and claim identifiers, a clear request for review, the reason coverage should change, and supporting material such as a clinician letter or medical records. Keep the EOB or denial, your submission, attachments, delivery proof, and dated conversation notes.
Rank #3

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
Request expedited handling when delay is dangerous
Tell the plan explicitly that the case is urgent and explain the medical consequence of waiting. HealthCare.gov says eligible urgent decisions are handled as fast as the medical circumstances require. An older 2020 National Association of Insurance Commissioners (NAIC) article describes general periods of 72 hours for urgent-care appeals, 30 days for treatment not yet received, and 60 days for treatment already received; use current plan instructions rather than relying on that older article for a deadline.
Use external review after an upheld denial
If the internal appeal is upheld, an eligible denial may qualify for independent external review. HealthCare.gov identifies medical-judgment decisions, experimental or investigational treatment decisions, and certain coverage rescissions among possible categories. A request generally must be made within four months after the final denial notice. Standard external review is generally due within 45 days; expedited review is generally due within 72 hours. The state or federal process, administrator, eligibility rules, and deadline depend on the plan and location, so follow the final notice. Under the described process, the insurer must accept the external-review decision.
Do not apply health deadlines to other insurance
Auto, homeowners, renters, life, disability, travel, and other policies do not share one nationwide appeal deadline. The controlling rules depend on the state, insurance line, policy wording, and facts. Preserve every deadline in your own policy and denial letter; never assume that the 180-day health-plan period or a health external-review route applies to a property or casualty claim.
State-specific instructions can be narrower
California’s Residential Property Claims Guide, for example, says a property denial must be in writing, state the reasons, and tell the claimant that the California Department of Insurance may review a wrongful-denial concern. It also describes sending a letter and supporting copies to a claims executive at the insurer’s headquarters. Those are California residential-property instructions, not a national rule. Check your own state’s requirements before using them.
Rank #4

- Stable & sturdy construction: Expanding file folder is made from durable wipe-clean polypropylene. Acid-free and high-quality for using trustingly. Waterproof & sturdy enough to keep the file organizer from collapsing. The accordion folder's cord closure and adjustable flap provide additional security. Built-in file separation layers are flexible to ensure the files don't wrinkle.
- Handy organization & Easy lookup: Expandable file folder has 24 pockets designed for keeping our paperwork organized. Accurately classified storage in the specific color slot and labeled with tabs, so it is easier to find the papers what is needed.
- Plentiful storage: Product Size: 13'' L x 9.25'' H. Each pocket fits well for all A4/Letter size paper. Excellent scalability. The accordion file folder can be stretched pretty far, more than 24 inches. 24 pockets allow you to store more than 4000 sheets of paper documents.
- Portable & stylish: Classic lightweight folder organizer can be compressed to a minimum thickness of about 2 inches, so it can be held up great for traveling to and from all different locations for work. Fits perfectly when completely closed in the file cabinet. The dividing sections of the rainbow file folders come in six bright colors, stylish and beautiful. Versatile document organizer for home, office, school, and travel scenarios, compact and light.
- Expandable desktop folder: Folders can be expanded to different widths as the number of files you put into increases. Stand on its own on the desk and not easy to tip over when pulled out to maximum capacity and filled. Each pocket is completely sealed at the bottom to keep small objects do not move.
Complain to your state insurance department
NAIC consumer guidance says, “If you have a problem with your insurer, you should try to resolve it with them first.” Once you have sought an explanation or filed the required appeal, a complaint to your state insurance department (DOI) can address unfair claim delays or denials, failure to honor a policy, violations of insurance law, or a lack of timely communication.
What to submit
- Insurer name, policy and claim numbers, and the type of insurance.
- A concise chronology with dates of loss, notices, calls, submissions, and promised responses.
- The policy, denial or EOB, bills, estimates, photographs, medical records, and appeal materials.
- The specific policy language or conduct you believe was mishandled and the resolution requested.
Use the DOI’s form or instructions and upload copies rather than originals. The department may send the complaint to the insurer and require an explanation; it can require corrective action if it finds improper conduct. Authority, processing methods, and remedies vary by state. A complaint is a regulatory review, not a promise that the claim will be paid, and it does not automatically replace an appeal or extend a policy deadline.
Choose the next step by decision branch
- Pending and information is missing: obtain the exact request, submit it with proof, and calendar the promised response date.
- Administrative or coding error: ask the provider or adjuster to correct and reprocess it while preserving the formal deadline.
- Final denial with time remaining: file the written appeal point by point and attach evidence.
- Urgent health treatment: request expedited internal review and ask the notice whether expedited external review is available before completing internal review.
- Internal health appeal upheld: check eligibility and the four-month external-review window immediately.
- No response or suspected legal violation: submit a factual DOI complaint after documenting your efforts with the insurer.
Common mistakes that weaken a claim
- Waiting for a phone promise instead of obtaining the reason and deadline in writing.
- Sending a large file without an index that connects each document to a denial reason.
- Missing an appeal deadline while trying to negotiate an informal correction.
- Assuming a regulator complaint automatically orders payment or pauses contractual deadlines.
- Sending original receipts, records, or photographs without retaining copies and delivery proof.
- Using a health-insurance deadline for a property, auto, life, disability, or travel dispute.
A practical claim-file checklist
- Create one folder labeled with the insurer, claim number, and date of loss or service.
- Add the policy or plan and a one-page chronology.
- Save every notice, EOB, bill, estimate, record, photograph, and submission receipt.
- Maintain a contact log with representative identifiers and promised dates.
- Calendar the earliest appeal, external-review, proof-of-loss, and response deadlines.
- Before sending an appeal, verify that every denial reason has a matching explanation and attachment.
- After submission, request written acknowledgment and follow up on the date promised.
The governing document and jurisdiction determine the remedy. A careful record, a precise written question, and a timely appeal give you the strongest position whether the claim is ultimately corrected by the insurer, reviewed by an independent health reviewer, or examined by your state DOI.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




