
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →A higher homeowners insurance renewal bill is a reason to investigate, not an automatic reason to cancel coverage. Put your current and prior declarations pages side by side, identify every changed limit, deductible and endorsement, ask the insurer what caused the increase, and obtain several quotes that match your existing protection. Then decide whether a deductible or coverage change is affordable without leaving important risks uninsured. Rates, notice requirements and available remedies depend on your state and policy.
Why a homeowners insurance premium can increase
Your premium reflects the insurer’s estimate of future claims and the cost of paying them. Some drivers are specific to your property; others affect nearly every policyholder in a region or market. An increase does not necessarily mean you filed a claim or that something is wrong with your home.
| # | Preview | Product | Price | |
|---|---|---|---|---|
| 1 |

|
First Alert Battery Smoke Alarm | $51.42 | Buy on Amazon |
| 2 |

|
First Alert Battery Smoke Alarm | $16.99 | Buy on Amazon |
| 3 |
|
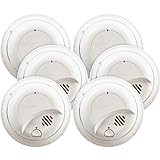
First Alert BRK SMI100-AC Hardwired Smoke Detector with Battery Backup, 6-Pack | $102.29 | Buy on Amazon |
| 4 |

|
First Alert Battery Smoke Alarm | $29.99 | Buy on Amazon |
| 5 |

|
First Alert Hardwire Smoke Alarm | $101.47 | Buy on Amazon |
As an Amazon Associate I earn from qualifying purchases.
Property-specific risk
- Age and condition of the home: Older roofs, wiring, plumbing or heating systems can increase the expected cost of a loss. Deferred maintenance can also affect underwriting decisions.
- Fire protection: The distance to a fire station, the available water supply and local fire-protection resources can affect pricing.
- Changes in insured limits: Your dwelling limit may have been adjusted to reflect a higher estimated cost to rebuild. A higher limit generally produces a higher premium even if the home’s market sale price has not changed.
- Property or policy changes: A renovation, newly added structure, new valuable property, an endorsement or a change in occupancy can alter the policy’s risk and price.
Broad market and catastrophe costs
Insurers also price for conditions outside one household’s control. Catastrophe losses, higher construction and repair costs, inflation, litigation expenses and reinsurance costs can all put upward pressure on premiums. A company may change its rates for an entire territory after reviewing those costs.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Maryland Insurance Administration guidance explains that an increase not attributed to a claim is usually a general rate increase. The same guidance notes that dwelling coverage can rise as home values and rebuilding costs increase. “General” does not mean the charge is arbitrary; it means the insurer is applying a broader approved or filed pricing change rather than billing you for a particular loss.
#1 Best Overall
- First Alert's Precision Detection advanced sensing technology complies with new industry standards to reduce cooking nuisance alarms and provides early warning in the event of a home fire emergency
- Battery-operated alarm allows for easy installation and maintenance
- Front access battery compartment makes for easy battery replacements
- End-of-life warning lets you know when it’s time to replace the alarm
- Test/silence button for efficient testing to ensure alarm is working properly
Start with the renewal declarations page
The declarations page is the quickest way to distinguish a pure rate change from a coverage change. Print or download the prior policy and the renewal, then mark every difference before calling the insurer.
- Dwelling coverage: Compare the limit and ask whether it is based on an updated estimated rebuilding cost.
- Other structures: Check limits for detached garages, sheds, fences and similar property.
- Personal property: Confirm the contents limit and whether high-value items have scheduled coverage or special limits.
- Liability and medical payments: Note any changes to personal-liability or medical-payments limits.
- Deductible: Record the amount and whether it is a fixed dollar deductible or a percentage of the insured value.
- Endorsements: Look for added, removed or changed protection, such as equipment breakdown, water backup or replacement-cost endorsements.
- Premium and billing: Separate the policy premium from installment fees or other charges shown on the bill.
Save the pages and your written questions. A clear before-and-after record helps if the insurer’s first explanation does not match the documents.
Questions to ask the insurer or agent
Call before the renewal date, allowing time to correct an error or obtain other quotes. Ask for a line-by-line explanation rather than accepting “rates went up” as the only answer.
- “What exact change produced the new premium?” Ask the representative to separate a general rate change, a claim-related charge, a revised dwelling limit and any policy or endorsement change.
- “Was my dwelling limit recalculated from an estimated rebuilding cost?” Rebuilding cost is different from the home’s market value and can change as labor and material prices move.
- “Did my deductible, valuation method or covered perils change?” A lower premium can conceal a higher deductible or narrower protection.
- “Which discounts are available for this policy and what documentation is required?” Ask specifically about bundling and safety devices such as smoke detectors; eligibility and savings vary by insurer.
- “Is there anything I can repair, document or update that would affect underwriting?” Request the requirement in writing and ask when a change would take effect.
- “What are my renewal and cancellation deadlines?” State notice periods and procedures differ, so confirm them rather than relying on a general rule.
Ask for the explanation by email or in a letter when possible. If the answer changes after a second call, you will have a useful record of what was represented.
Rank #2
- First Alert's Precision Detection advanced sensing technology complies with new industry standards to reduce cooking nuisance alarms and provides early warning in the event of a home fire emergency.
- Battery-operated alarm allows for easy installation and maintenance
- Front access battery compartment makes for easy battery replacements
- End-of-life warning lets you know when it’s time to replace the alarm
- Test/silence button for efficient testing to ensure alarm is working properly
Shop around before the renewal date
Get quotes from multiple insurers early enough to compare them while your current policy is still in force. A lower number is meaningful only when the underlying protection is equivalent. North Carolina Department of Insurance guidance, published August 19, 2026, advises consumers to compare equivalent coverage, limits and deductibles rather than price alone.
Give each insurer the same information: construction details, roof age, updates, occupancy, claims history, desired limits and deductible. Incomplete or inconsistent applications can make quotes look artificially different and may create problems if a claim occurs.
Quote-comparison checklist
| Item | What to compare | Why it matters |
|---|---|---|
| Dwelling limit | Limit and the rebuilding assumptions behind it | A limit that is too low can leave a rebuilding shortfall; a higher limit can raise the premium. |
| Personal property | Limit, sublimits and whether settlement is replacement cost or actual cash value | Actual cash value generally accounts for depreciation, while replacement-cost terms can provide a different claim payment. |
| Liability | Personal-liability and medical-payments limits | These limits protect against different types of claims and should not be compared only by the total premium. |
| Deductible | Dollar amount, percentage basis and any separate catastrophe deductible | A percentage deductible can create a much larger bill after a major loss. |
| Covered perils and exclusions | Risks covered, excluded or subject to special limits | Two policies with similar limits can provide materially different protection. |
| Endorsements | Added protections and their limits | Important household exposures may require an endorsement rather than standard coverage. |
| Discounts | Discount type, qualification and whether it is already included | A quoted discount is useful only if you qualify and can maintain the requirement. |
| Total premium | Full policy cost for the same term and billing arrangement | Installment fees or different payment schedules can distort a headline comparison. |
Request the quote and endorsements in writing. Read exclusions and claims-settlement language, not just the declarations page. If an agent proposes a lower limit or a different valuation basis, have the change identified explicitly.
Decide whether changing the deductible makes sense
Increasing the deductible can reduce the premium, but it transfers more loss cost to you. First determine the largest amount your household could pay promptly after a covered loss without using high-cost debt or abandoning necessary repairs.
Rank #3
- 6 pack of hardwired smoke alarms, includes battery backup for power outages
- Tamper resistant locking pins, single button silence/test and loud 85Db alarm
- 120-Volt AC power with 9-volt battery backup (included) to keep alarm functioning during power outage
- Open mounting design for easy installation with side load battery compartment for quick replacement and interconnect able up to 18 units (12 smoke, 6 co/heat/relay)
- 10-Year limited
Check whether the deductible is fixed or percentage-based. A fixed deductible is stated as a dollar amount. A percentage deductible is applied to an insured value, often the dwelling limit, so the dollar cost rises when that limit rises. For example, a hypothetical 2% deductible on a $300,000 dwelling limit would be $6,000; the policy documents control the actual calculation and any separate deductibles.
- Keep the current deductible if the higher amount would require borrowing, selling investments at a bad time or delaying essential repairs.
- Consider a higher deductible only when you have liquid funds reserved for that specific risk and the premium reduction is material enough to justify it.
- Ask whether wind, hail, hurricane or other catastrophe losses use a separate deductible. A quote that lists one general deductible may not describe every claim scenario.
- Do not choose a deductible you could pay only by counting on an insurance payment that would arrive later.
Compare the premium savings over a year with the additional amount you would owe on a claim. The insurer or agent should show both figures; you do not need to accept a change simply because it is the fastest way to lower the bill.
Use discounts without weakening protection
Ask what discounts the insurer actually offers, rather than assuming a device or bundle qualifies everywhere. Bundling home and other policies may qualify with some insurers. Safety measures, including smoke detectors, may also qualify with some insurers, according to Utah Insurance Department guidance. No universal qualification rule or savings amount applies.
Confirm four details before spending money to qualify:
Rank #4
- First Alert's Precision Detection advanced sensing technology complies with new industry standards to reduce cooking nuisance alarms and provides early warning in the event of a home fire emergency
- Battery-operated alarm allows for easy installation and maintenance
- Front access battery compartment makes for easy battery replacements
- End-of-life warning lets you know when it’s time to replace the alarm
- Test/silence button for efficient testing to ensure alarm is working properly
- Which exact device, installation method or policy bundle is eligible?
- What proof must you provide, such as receipts, photographs or an inspection?
- Does the discount apply immediately, at the next renewal or only after underwriting approval?
- Will the discount continue if you change another policy, remove the device or stop a monitoring service?
A safety improvement can be worthwhile because it reduces the chance or severity of a loss, but do not buy equipment solely for an assumed discount. Ask the insurer for the expected premium effect first.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Check exclusions, especially flood and earthquake damage
A cheaper quote may omit protection your household needs. North Carolina Department of Insurance consumer guidance states that standard homeowners policies do not cover flood or earthquake damage. Those exposures may require separate coverage, subject to the terms available in your area.
Review how the policy treats water entering from outside, sewer or drain backup, earth movement, wind or hail, mold, roofs and high-value property. The exact wording and endorsements matter. If your location or property makes a particular exposure plausible, ask the insurer what separate policy or endorsement is available and what deductible applies.
Recommended Free Tools
Do not cancel the existing policy until replacement coverage is confirmed in writing, the effective date is set, and the new insurer has accepted the application. A quote is not the same as an issued policy.
Best Value
- First Alert's Precision Detection advanced sensing technology complies with new industry standards to reduce cooking nuisance alarms and provides early warning in the event of a home fire emergency
- Through early warning interconnect, when one alarm sounds, all compatible alarms will soun
- Battery backup provides continuous protection during power outages
- Alarm indicator visually identifies the unit that initiated the alarm
- Quick Connect Plug included allows for easy installation with no need to rewire
When the explanation or process is not satisfactory
First ask the insurer for a supervisor or a written underwriting explanation. Compare that response with the renewal documents and your state’s consumer guidance. Keep copies of notices, emails, call dates and the names of representatives.
If you believe the insurer misapplied the policy, failed to provide required notice or is not following the state’s rules, contact your state insurance department. State rules govern rate review, renewal notices, complaint procedures and available consumer remedies, so the correct agency and deadlines depend on where the property is located. A regulator can explain the complaint process; it does not guarantee that a premium will be reduced.
A practical timeline for the renewal
As soon as the renewal arrives
- Save the renewal declarations and the prior policy.
- Mark changes in limits, deductibles, endorsements and premium.
- Check the renewal effective date and any response deadline.
Within the next few days
- Ask the insurer for a written explanation and updated rebuilding-cost assumptions.
- Confirm available discounts and required documentation.
- Calculate the maximum deductible your household could pay from liquid funds.
Before the renewal date
- Obtain several quotes using identical limits, deductibles and valuation terms.
- Review exclusions and endorsements, including flood and earthquake protection where relevant.
- Choose whether to renew, change the deductible or switch only after confirming the replacement policy’s effective date.
After the decision
- Keep the final declarations page, endorsements and payment confirmation.
- Record the next review date and update the insurer after material renovations or household changes.
Common mistakes to avoid
- Comparing premiums alone: A lower price may reflect lower limits, a percentage deductible, actual-cash-value settlement or more exclusions.
- Assuming the increase is a claim surcharge: Ask whether it is a general rate change or a coverage revision; Maryland guidance says non-claim increases are usually general rate increases.
- Using the home’s sale value as the dwelling limit: Insurers generally discuss estimated rebuilding cost, which is a different measure.
- Choosing an unaffordable deductible: The premium savings do not help if you cannot fund the claim payment.
- Assuming standard coverage includes every disaster: Flood and earthquake damage are excluded from standard homeowners policies under the North Carolina guidance cited above.
- Letting coverage lapse while shopping: Secure written replacement coverage before cancelling the old policy.
- Paying for a safety product without checking eligibility: Discounts are insurer-specific and may require proof or approval.
What a sound decision looks like
The right response is not always to find the lowest renewal premium. It is to understand what changed, keep limits and claim terms appropriate for the home, and select a deductible the household can actually pay. If another insurer offers a genuinely equivalent policy for less, switching can be reasonable. If every comparable quote is higher, the increase may reflect broader construction, catastrophe or reinsurance costs rather than an error in your account. In either case, the declarations comparison and written explanations give you the information needed to make a deliberate choice.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




