
After your final mortgage payment, do four things in order: obtain written payoff confirmation, verify that the lien is released in the county or state property record, preserve the key loan and home documents, and take over any property-tax or homeowners-insurance bills that were previously paid from escrow. Then rebuild your budget around those direct bills and check tax questions against current IRS guidance.
This checklist is for U.S. homeowners. Recording procedures, office names and update times vary by jurisdiction, and tax, insurance and title results depend on your circumstances.
As an Amazon Associate I earn from qualifying purchases.
1. Get written confirmation that the loan is paid
A zero balance in an online account is useful, but keep a formal record from the servicer showing that the obligation was paid in full. Save the final payoff confirmation, the last account statement and any closing or payoff correspondence together.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Ask for the exact release process
Contact the mortgage servicer and ask three specific questions:
#1 Best Overall
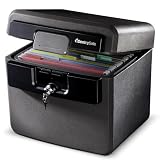
- FIRE AND FLOOD PROTECTION FOR ESSENTIAL PAPERS: UL Classified to withstand high temperatures for up to thirty minutes and ETL Verified to protect contents during water exposure, helping safeguard critical paperwork during common home emergencies
- DESIGNED FOR IMPORTANT DOCUMENT STORAGE: Spacious interior fits hanging file folders and is ideal for organizing passports, birth certificates, insurance records, and legal paperwork
- KEY LOCK SECURITY YOU CONTROL: Durable key lock helps prevent unauthorized access and keeps the lid securely closed during fire events. Two keys are included for backup access
- HOME FRIENDLY SIZE WITH PORTABLE DESIGN: Compact footprint fits easily in closets, offices, or under desks while remaining portable enough to relocate when needed
- BUILT FOR EVERYDAY PEACE OF MIND: Black exterior offers a clean, neutral look that blends into home or office spaces while providing dependable document protection year round
- What document will show that the mortgage lien has been released?
- Will the servicer send that document directly to the county or state recording office?
- If the servicer sends it to you, what action, fee or filing instruction applies in your jurisdiction?
The answer can depend on the loan instrument and local practice. Do not assume that the release is already visible in public records on the day the balance reaches zero. The Consumer Financial Protection Bureau (CFPB) warns that a delay may occur between payoff and recording.
Keep the final numbers with the confirmation
Retain the payoff statement or final account statement that identifies the date paid, the amount applied and the resulting balance. If you paid by wire, cashier’s check or another method that generated a receipt, keep that proof with the servicer’s confirmation. These records give you a clear starting point if a later record search or account question does not match your expectation.
2. Verify that the lien was released in the public record
Paying the debt and seeing the lien released are separate milestones. The public property record—not the servicer’s website—is where you confirm the recorded status.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Find the office that maintains your property record
Use your state’s property-record system if it provides one, or contact the county recorder, register of deeds or equivalent office for the property’s location. The office may offer an online search, an in-person terminal or a request process by mail. Have the property address, parcel information and the names shown on the mortgage available.
Search for the release
Look for an entry showing that the mortgage lien has been released under the terminology used in your jurisdiction. Compare the property description and borrower names with your original closing documents. Save a copy of the recorded entry, image or confirmation number if the office provides one, and note the date you checked.
If the release is not recorded yet
There is no single nationwide recording deadline established by the sources used for this checklist. If your search does not show a release:
- Ask the servicer whether it has prepared and transmitted the document, and request the date and destination of any submission.
- Ask the recorder what status, indexing delay or follow-up it can identify for your property.
- Give both offices the payoff confirmation and the property-record details they need to locate the transaction.
- Keep a dated log of calls, messages, names and documents sent.
Do not file a substitute document or assume that a new deed is required merely because the mortgage was paid. If the record remains unresolved after you have checked with both offices, a title professional or local attorney can help analyze a concrete title problem; the appropriate remedy depends on the jurisdiction and the instrument involved.
3. Create a permanent mortgage and home-record file
The CFPB recommends retaining the complete closing file. Its guidance puts it plainly: “Save the whole stack or electronic file.” Keep paper originals in a secure place and maintain usable digital copies where appropriate.
Documents to retain
| Document | Why it matters after payoff | What to do |
|---|---|---|
| Closing Disclosure | Records the final closing terms, amounts and parties. | Keep the signed paper or a complete electronic copy. |
| Promissory note | Shows the debt agreement that has been satisfied. | Retain the original if returned by the lender, plus a readable digital copy. |
| Mortgage, security instrument or deed of trust | Identifies the lien instrument tied to the property. | Store it with the closing file and the eventual release record. |
| Deed | Shows the ownership conveyance for the property. | Keep it with your permanent home records. |
| Recorded lien-release record | Provides the public-record evidence that the mortgage lien was released. | Save the recorded image, instrument number or official confirmation. |
| Final payoff confirmation and account statement | Shows the servicer’s payoff and the account’s zero balance. | Keep the final statement, payoff letter and payment proof together. |
Use a file structure you can find years later
Create one paper folder or safe-deposit arrangement and one digital folder with the same naming convention. Include the property address, the payoff date and a short index. Scan legible copies rather than relying on photographs that omit pages or signatures. Protect digital files with a backup and access controls, and make sure a trusted person knows how to locate the records if you become unavailable.
A document safe is an optional storage aid. The CFPB’s recommendation is to keep the records in a safe place; it does not require buying a particular container or claim that any specific construction is necessary.
4. Move property-tax and insurance payments out of escrow
Escrow can hide the timing and size of recurring ownership bills because the servicer collects part of the monthly mortgage payment and pays the bills. Once the mortgage is paid off, only the bills that were actually handled through escrow need a payment-handling transition.
Recommended Free Tools
Rank #2

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
Identify which bills were escrowed
Review your final mortgage statement and prior escrow history. Separate these two groups:
- Formerly escrowed: property taxes or homeowners-insurance premiums the servicer paid for you.
- Already paid directly: utilities, association dues, supplemental policies or other costs you were paying outside the mortgage payment.
The first group requires new billing instructions and a personal payment system. The second group does not change simply because the mortgage ended.
Confirm property-tax billing
Contact the tax authority for the property and ask where future bills will be sent, which payment methods it accepts, the due dates and whether your mailing address or electronic-delivery preference is current. Keep confirmation of any address change. A servicer’s prior payment does not guarantee that the tax office will automatically redirect notices to you.
Set up homeowners-insurance billing
Call the insurer or agency and confirm that the policy remains active, that it has your correct contact information and that future premiums will be billed to you rather than to a mortgage servicer. Ask for the premium amount, due dates, payment options and any automatic-payment settings. Keep the declarations page and payment receipts with your home file.
Build a bill calendar before the next due date
Write each tax installment and insurance premium on a calendar with its amount, due date and funding source. Set aside money before the bill arrives instead of treating the old escrow portion of your monthly payment as immediately spendable. If a bill is annual or semiannual, divide the expected amount by the number of months until it is due and transfer that amount to a dedicated savings balance.
The CFPB notes that property taxes may increase over time. Review the tax authority’s actual bill each cycle rather than assuming last year’s amount will remain adequate.
5. Keep the homeowners-insurance policy working after payoff
Mortgage payoff changes who pays the premium, not the need to protect the property. Confirm that the policy is active through the next renewal and that the insurer is no longer waiting for an escrow payment from the former servicer.
Check the account details
- Verify the insured property address and your mailing and email addresses.
- Confirm the next premium amount and every installment due date.
- Confirm whether automatic payment is enabled and which account or card it uses.
- Save proof of payment and the current policy documents.
Do not assume payoff changes the premium or coverage
The sources reviewed do not establish that paying off a mortgage automatically lowers insurance premiums, nor do they identify a coverage amount that fits every homeowner. Ask the insurer how your policy is billed and discuss coverage changes only in light of your property, risks and finances. Removing a mortgagee from the policy may be an administrative update; it is not a reason by itself to cancel coverage or reduce limits.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errors6. Rebuild your monthly cash-flow plan
The former mortgage payment combined principal, interest and—often—escrow. After payoff, principal and interest disappear, but property taxes, insurance, maintenance and other ownership costs remain. Build the new budget from actual bills rather than declaring the entire old payment available for spending.
Create sinking funds for irregular bills
Use separate savings categories for property taxes, homeowners insurance and major maintenance. For each category, record the next due date and the amount currently known. Divide an annual bill into monthly transfers; for a bill that may change, add a cushion based on your own history and the latest notice. Revisit the transfers when a new tax assessment, renewal notice or repair need arrives.
Keep a maintenance reserve distinct from taxes and insurance
Taxes and insurance are obligations with invoices and due dates. Maintenance is a variable reserve for work such as systems, appliances or exterior repairs. Keeping the categories separate prevents a large repair from consuming money earmarked for a tax installment and makes it easier to see which costs are contractual versus discretionary.
Rank #3

- FIREPROOF: The safe is UL Classified to endure 1/2 hour at 1550°F to protect irreplaceable documents, small valuables, DVDs, and USBs from fire
- WATERPROOF: The safe is ETL Verified for 72 hours of water submersion offering peace of mind in the event of a flood
- COLOR: Dark Gray Color offers a sleek and professional appearance
- MEASUREMENTS: Exterior: 16. 6 in. W x 13. 8 in. D x 14. 1 in. H; Interior: 12 in. W x 8. 1 in. H x 11. 6 in. H; large capacity 0. 66 cubic feet; weighs 41 pounds
- DURABLE: Fireproof lock box features a flat key lock to prevent the lid from opening in the event of a fire; includes two keys
Direct the remaining cash deliberately
After funding known property bills and an emergency reserve, decide where any remaining monthly cash should go according to your broader plan: other high-cost debt, retirement savings, education funding or another documented goal. The decision is personal; the essential step is to make it after accounting for direct homeownership costs, not before.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
7. Check federal tax questions using current IRS guidance
Mortgage payoff does not settle your tax filing. The Internal Revenue Service’s Publication 530, Tax Information for Homeowners (2025), discusses federal treatment of mortgage interest, property taxes and escrow. Use the publication and the instructions for the tax year you are filing, because rules and personal eligibility can differ.
Mortgage interest
Once the loan is paid, there may be no future mortgage-interest payments to report. Whether you can claim any interest or other homeowner deduction for a particular year depends on the payments made, the property’s use, your filing situation and current federal rules. Keep the final interest statement and closing records rather than estimating from the old monthly payment.
Property taxes
Keep receipts, cancelled payments and tax bills for amounts you actually paid. Publication 530 addresses property-tax treatment, but the amount that is useful on your return depends on current limits and your circumstances. A tax bill being placed in escrow is not the same as a deduction for every dollar deposited.
Escrow contributions
The IRS publication says homeowners may not be able to deduct the total amount contributed to an escrow account. Track the tax and insurance payments that were actually made and use the tax-year instructions that apply to you. If the timing, property use or filing status makes the answer unclear, consult a qualified tax professional rather than relying on the former escrow contribution as a shortcut.
8. Troubleshoot common post-payoff problems
The servicer has not sent confirmation
Request the final payoff letter and account statement in writing. Include the property address, loan number, payoff date and the payment reference. Keep the request and any response with your payment proof. If the servicer identifies a remaining balance or an unapplied payment, ask for a transaction-level explanation before treating the account as closed.
The public record still shows the mortgage
First determine whether the servicer submitted the release and whether the recorder has indexed it. Provide the recorder with the instrument information and the servicer with the official property-record details. Because local timelines and document names vary, follow the instructions of those offices rather than applying a deadline from another state.
A tax or insurance bill goes to the old servicer
Contact the tax authority or insurer immediately, update the mailing and electronic-delivery details, and confirm whether a bill is unpaid or merely misdirected. Pay by the method and date the bill requires, then retain the receipt. Do not assume that a notice sent to the former servicer has been paid.
You discover a title question unrelated to the payoff
Keep the issue separate from the routine checklist. Gather the deed, mortgage instrument, recorded release, payoff confirmation and any other document that describes the disputed interest. A title professional or local attorney may be appropriate when a concrete defect, unreleased interest or ownership question remains; the correct analysis is jurisdiction-specific.
9. Know when the transition is complete
You have finished the administrative transition when your file contains the servicer’s written payoff confirmation, the public record shows the lien release, the original and electronic home documents are preserved, and every formerly escrowed bill has a confirmed payee, due date and funding plan. Keep monitoring the tax and insurance accounts on their normal cycles, because ending the mortgage does not end those ownership responsibilities.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




