
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Hospital indemnity insurance is supplemental coverage that pays you a fixed cash benefit when a policy-defined hospitalization event occurs. For example, a policy might pay $1,000 for a qualifying hospital admission plus $100 for each covered day. The payment is generally based on the event—not on the size of your hospital bill—and may be used for deductibles, transportation, childcare, rent, groceries, or other expenses.
It is not comprehensive health insurance and does not pay all of your medical bills. Its value is mainly in helping with the cash-flow disruption that can accompany a hospital stay, particularly when you have a high-deductible health plan or significant Medicare cost sharing.


As an Amazon Associate I earn from qualifying purchases.
How hospital indemnity insurance works
A hospital indemnity policy, also called fixed-indemnity or hospital insurance in some documents, contains a schedule of predetermined benefits. You receive a payment when you meet the contract’s definition of a covered event.
The insurer does not generally calculate the payment by adding up your actual treatment costs. Federal guidance describes fixed-indemnity benefits as predetermined payments made without regard to the amount of health-care costs incurred. The benefit is traditionally paid directly to the policyholder, who can use it for medical or nonmedical expenses. CMS explains the distinction between fixed-indemnity and comprehensive coverage.
A hypothetical benefit schedule could look like this:
| Covered event | Example benefit |
|---|---|
| Qualifying hospital admission | $1,000 lump sum |
| Covered inpatient confinement | $100 per day, up to the policy limit |
| Intensive-care confinement | An additional daily amount, if included |
| Emergency-room treatment, ambulance, surgery, testing, or rehabilitation | Separate fixed amounts, if included in the plan |
These dollar amounts are only an illustration. Benefits, definitions, exclusions, waiting periods, and limits vary by insurer, state, employer plan, and policy form. The certificate of insurance and benefit schedule—not a sales summary—control whether a claim is payable. The National Association of Insurance Commissioners (NAIC) glossary describes hospital indemnity coverage as a predetermined fixed benefit or daily indemnity based on a stay at a hospital or intensive-care facility.
What can the cash benefit pay for?
Unlike a medical plan that pays providers according to covered services, a hospital indemnity payment is generally flexible cash. Depending on the policy and applicable tax rules, you might use it for:
- a health-insurance deductible, copayment, or coinsurance;
- transportation, parking, meals, or lodging for the patient or family;
- childcare or elder-care expenses;
- rent, mortgage payments, utilities, and groceries;
- lost household cash flow while someone is recovering; or
- medical expenses that the primary plan does not cover.
The payment is not a promise to make you financially whole. A hospital bill may be far higher than the fixed benefit, and a claim may be denied if the stay does not meet the policy’s definition of admission or confinement.
What hospital indemnity insurance is not
It is not major medical insurance
Hospital indemnity insurance is usually designed to supplement, not replace, comprehensive health coverage. It generally does not provide a broad provider network, pay for routine doctor visits and prescriptions comprehensively, or insure the full cost of treatment. CMS describes fixed-indemnity coverage as limited coverage and warns that it is not a substitute for comprehensive health insurance. See CMS’s consumer guidance.
Do not buy it instead of an ACA-compliant Marketplace plan, an employer medical plan, or other comprehensive coverage unless you have independently evaluated how your primary health-care costs would be covered.
It is not the same as a traditional indemnity medical plan
A traditional medical indemnity plan generally reimburses eligible health-care expenses under its terms. Hospital indemnity insurance pays a fixed amount after a specified event. The word “indemnity” by itself does not tell you which type of product you are considering.
It is not Medigap
Medigap is Medicare supplemental insurance that helps pay certain out-of-pocket costs associated with Original Medicare. Hospital indemnity insurance pays a separate fixed cash benefit under its own contract. It does not satisfy the role of Medigap or change Medicare’s coverage and billing rules. Medicare explains the role of supplemental coverage.
Who might consider hospital indemnity insurance?
The strongest use case is a household that could handle the medical treatment but would struggle with the immediate financial consequences of a hospitalization. It may be worth comparing if:
Rank #2
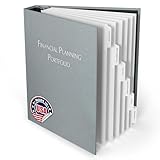
- EVERY FINANCIAL DOCUMENT IN ONE PLACE — This financial records organizer includes six pre-labeled tab dividers — Investments, Bank Statements, Insurance, Legal Documents, Taxes, and Retirement — so every important paper has a clear home. No more hunting through file boxes, drawers, and shoeboxes when you need a tax return or insurance policy.
- PEACE OF MIND FOR YOU, CLARITY FOR THE PEOPLE YOU LOVE — Whether it is a CPA appointment, a tax filing, a retirement decision, or a family member stepping in to help, every account number, policy, and statement is in one clearly-labeled financial binder — accessible in minutes, not hours. Designed to hold the financial records you actually need at hand — current policies, recent tax returns, key statements, beneficiary forms — not a replacement for your full file cabinet.
- PREMIUM LINEN CONSTRUCTION, MADE IN THE USA — Refined linen cover with silver foil detailing, rigid hardcover, and a 1.5-inch D-Ring that holds up to 350 sheets of standard 8.5 x 11 paper. Includes a heavyweight water-resistant document pocket, media sleeve for USB drive backups, and a business card holder for your CPA or financial advisor.
- A THOUGHTFUL GIFT WITH LASTING PURPOSE — Getting financial records organized is something most people mean to do one day. This portfolio makes starting easier — an ideal gift for aging parents, newly retired couples, adult children managing household finances, or anyone preparing for tax season, a financial advisor meeting, or retirement.
- FOR THE WAY HOUSEHOLDS ACTUALLY ORGANIZE — Built for the household record-keeper getting financial papers in one place, the adult child helping aging parents centralize accounts and policies, and anyone preparing a spouse, executor, or financial advisor with everything they would need to step in and find what matters.
- your primary health plan has a high deductible or substantial coinsurance;
- you have limited emergency savings;
- a hospitalization could interrupt your income or create childcare and transportation costs;
- you want an additional cash reserve for a planned risk, subject to the policy’s exclusions and waiting periods; or
- you have Medicare cost sharing that a fixed benefit could help offset.
It may be less attractive if you have a low deductible, a strong emergency fund, little likelihood of using the benefit, or a premium that takes money away from more important coverage and savings goals. There is no universal answer to whether it is “worth it.” Compare the actual premium and benefit schedule with the financial gap you are trying to cover.
Hospital admission versus observation: a critical distinction
Spending the night in a hospital does not necessarily mean you were formally admitted as an inpatient. Medicare explains that a patient can remain overnight while receiving outpatient observation services if a doctor has not formally admitted the patient. Medicare’s inpatient-versus-outpatient explanation describes why the distinction matters.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Private hospital indemnity policies may define covered confinement differently. One contract may require formal inpatient admission; another may include observation only after a minimum number of continuous hours in a qualifying area. Before buying, find the definitions of:
- hospital;
- admission;
- confinement;
- observation;
- intensive care; and
- covered sickness or injury.
Never assume that an overnight stay automatically triggers an admission benefit. Ask the insurer how the policy treats observation, emergency-room treatment followed by discharge, and a transfer between facilities.
Important limitations to inspect
Preexisting conditions and waiting periods
A policy may limit or exclude benefits for a preexisting condition, treatment received before the effective date, or claims occurring during an initial waiting period. “Guaranteed acceptance” or “no medical questions” does not necessarily mean every event is covered immediately. Product disclosures from insurers such as Aflac and MetLife illustrate why the actual certificate matters.
Benefit caps and repeat admissions
Check the maximum payable days, annual and lifetime limits, admission-frequency rules, treatment-specific limits, and readmission language. A readmission within a stated period may be treated as a continuation of the original confinement. A transfer from one hospital to another—or a move from a hospital bed to intensive care—may not create a second admission payment.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteFacility exclusions
Everyday language uses “hospital” broadly; contracts may not. Review how the policy treats or excludes:
- rehabilitation facilities;
- skilled-nursing facilities;
- nursing homes and custodial care;
- hospice;
- psychiatric facilities; and
- outpatient or other nonhospital settings.
Age reductions and termination rules
Some policies reduce benefits at specified ages or end coverage under stated conditions. Employer coverage may be portable, but portability depends on the particular plan and conversion rules. For example, Cigna says portability is available under most of its plans, while MetLife materials warn that benefits may be reduced beginning at age 65 and that availability varies by state and policy form. Treat those statements as insurer- and plan-specific examples, not universal rules. Cigna’s employer hospital-care information and MetLife’s hospital indemnity information show the types of terms to investigate.
Claim paperwork
Find out whether you must provide an admission record, discharge papers, itemized bills, physician certification, or other medical documentation. Also ask who must certify the event and how the claim is submitted. Some insurers offer online or app-based claim initiation and document uploads, but that is not an industry-wide guarantee. MetLife’s benefit overview provides an example of an insurer-specific claims process.
How hospital indemnity insurance relates to federal rules
Hospital indemnity and other fixed-indemnity coverage can qualify as an “excepted benefit” under federal law only when applicable statutory and regulatory conditions are met. Those conditions generally include separate coverage, no prohibited coordination with comprehensive coverage, and fixed benefits paid independently of actual medical expenses.
Federal agencies emphasize that excepted-benefit coverage is limited and is not subject to every federal protection that applies to major medical insurance. A federal final rule was published on April 3, 2024, and the related regulatory material lists an effective date of June 17, 2024. The exact application can depend on the policy’s issue date, market segment, state law, product form, and other provisions. IRS guidance and the published federal rule provide the technical detail.
For consumers, the practical rule is simple: treat hospital indemnity insurance as limited supplemental coverage to evaluate alongside comprehensive insurance—not as a replacement for it.
How it fits with Medicare
Original Medicare Part A generally covers inpatient hospital care, but beneficiaries may still owe deductibles and daily coinsurance depending on the benefit period and length of stay. Medicare’s current 2026 cost information lists a Part A inpatient deductible of $1,736 per benefit period, with additional daily amounts after the first 60 days. Part B generally covers 80% of the Medicare-approved amount for physicians’ services after applicable cost sharing. Confirm current amounts directly with Medicare because they can change.
A hospital indemnity payment could be used toward those costs or toward nonmedical expenses. It does not alter Medicare’s inpatient-status decision, provider billing, coverage rules, or your obligations under the indemnity policy. Compare it with your Medicare Advantage or Medigap coverage rather than assuming it provides equivalent protection. Medicare’s inpatient hospital-care page contains the current coverage and cost-sharing information.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Tax questions and premium payment method
Do not assume that every hospital indemnity payment is tax-free. Tax treatment can depend on who paid the premium, whether the premium was paid after tax or through a salary-reduction arrangement, and whether the benefit relates to medical expenses incurred.
For employer plans, IRS materials distinguish hospital indemnity or specified-illness coverage paid after tax from coverage paid through pre-tax salary reduction or by the employer. W-2 reporting—or the absence of reporting—does not by itself answer whether a particular claim payment is taxable. Review the premium-payment method with your benefits administrator and ask a tax professional about your circumstances. The IRS W-2 reporting guidance and IRS Internal Revenue Bulletin material are useful starting points.
If you use a health savings account, also ask how the specific policy interacts with your HSA eligibility and plan design. Do not rely on the label “supplemental” alone to answer that question.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Hospital indemnity insurance comparison checklist
Use the policy certificate, summary of benefits, exclusions, enrollment material, and premium schedule to answer each question:
Recommended Free Tools
- Premium: What is the monthly or payroll-deduction cost, and can it change?
- Admission benefit: Is it paid for every qualifying admission, once per year, or subject to a waiting or repeat-admission rule?
- Daily benefit: How much is paid per day, for how many days, and is intensive care paid separately?
- Observation: Does the contract pay for observation, and what minimum duration applies?
- Facilities: Are rehabilitation, skilled nursing, psychiatric care, hospice, or outpatient facilities excluded?
- Preexisting conditions: Is there a limitation, exclusion, or waiting period?
- Other triggers: Are emergency-room care, ambulance services, surgery, diagnostic tests, rehabilitation, maternity, or wellness benefits included?
- Caps: What are the per-event, annual, lifetime, day-count, and age-based limits?
- Portability: Can coverage continue after leaving an employer, and at what premium?
- Claims: What documents are required, who certifies the event, and how is the claim submitted?
- Taxes and HSA effects: How are premiums paid, and could that payment method affect taxation or account eligibility?
- State availability: Is this exact policy form approved and available where you live?
Insurer examples can help you recognize the terminology, but they are not interchangeable policies. For instance, a MetLife certificate illustrates how admission, confinement, transfers, and limits can be defined in detailed contract language. Employer plans from Cigna and other insurers can use different schedules.
Rank #4

- 100-pack of EKG medical chart index tabs with red edge color, each measuring 1.25 x 0.5 inch for consistent patient chart section labeling
- Self-adhesive tab inserts attach to divider sheets to help medical, dental, therapy, hospital, insurance, and records teams organize paper charts faster
- Titles are printed on both sides for side or bottom application, helping staff identify chart sections quickly when folders are reviewed, routed, or filed
- Tabs grip both sides of the divider sheet for a secure hold in active patient records, front desk files, billing folders, and clinical documentation workflows
- Use with compatible Tabbies medical chart divider sheets to build clean, standardized sections for patient information, records management, and office filing
State regulation and employer coverage
Availability, definitions, disclosures, and approved policy forms can vary by state. State insurance departments generally oversee fully insured products. Self-funded employer health plans are generally regulated under federal benefits law rather than state insurance law, so the route for checking a product or resolving a question may differ.
The NAIC provides health-insurance shopping resources and directs consumers to their state insurance departments. If you are buying individually, verify that the insurer and exact form are authorized or available in your state. If you are enrolling through work, ask the benefits administrator for the governing certificate, portability terms, and premium after employment ends.
A simple way to decide whether it fits
Start with the financial problem, not the advertised benefit. Estimate:
- your primary plan’s deductible and likely coinsurance;
- the cash expenses a hospitalization could create;
- the amount of emergency savings available immediately; and
- the annual premium for the indemnity policy.
Then compare that exposure with the policy’s realistic benefit after accounting for admission definitions, observation rules, waiting periods, exclusions, caps, and taxes. A policy that pays $1,000 for admission may be useful if it fills a genuine short-term cash gap. It is less useful if you are expecting it to cover a large medical bill, a nonqualifying observation stay, or every day of a lengthy recovery.
Frequently Asked Questions
Does hospital indemnity insurance pay the hospital directly?
Usually, the benefit is paid directly to the policyholder rather than calculated as reimbursement of the hospital’s bill. The policy’s claim and payment terms control, so confirm the arrangement before enrolling.
Can hospital indemnity insurance replace health insurance?
No. It is limited supplemental coverage that pays a fixed benefit after specified events. It generally does not provide comprehensive coverage for doctors, prescriptions, preventive care, and hospital bills.
Does an overnight hospital stay qualify for a benefit?
Not necessarily. A patient may remain overnight under outpatient observation rather than formal inpatient admission. Read the policy definitions and ask specifically how observation is treated.
Free tools Windows power users keep installed
One-click scans. No signup required.
Is hospital indemnity insurance worth it?
It may be useful when a hospitalization would create a significant cash-flow problem, especially with a high-deductible plan or Medicare cost sharing. Compare the premium, actual benefit schedule, restrictions, and your emergency savings rather than assuming it is valuable for everyone.
Is a hospital indemnity payout taxable?
Tax treatment depends on factors such as who paid the premium, whether it was paid after tax or through salary reduction, and whether the benefit relates to medical expenses. Ask your benefits administrator or tax professional instead of assuming the payment is tax-free.
The Bottom Line
Bottom line: Hospital indemnity insurance pays a contract-defined fixed cash benefit when a covered hospitalization event occurs. It can cushion deductibles and household expenses, but it does not insure the full cost of medical care. Before buying, confirm admission and observation rules, preexisting-condition limits, facility exclusions, benefit caps, portability, claim requirements, taxes, and state availability—and keep comprehensive health coverage in place.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




