
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Bring documents that establish five things: who you are, how you earn money, what you own, what you owe, and which property or transaction you are financing. A typical packet includes photo identification, address and employment history, recent income records, asset and down-payment statements, debt details, and property documents if you have already chosen a home.
There is no universal mortgage-broker checklist. Requirements vary by country, lender, loan program, borrower and stage of the process. Ask the broker for the current, secure submission checklist before sending sensitive information.
As an Amazon Associate I earn from qualifying purchases.
Start by confirming what meeting you are preparing for
A first conversation, a pre-approval, a formal application, a refinance and a mortgage renewal can require different evidence. A broker may only need a high-level picture at an introductory meeting, while a lender verifying an application may request complete statements, tax records and explanations for unusual transactions.
Ask these questions before assembling files:
- Is this meeting for general advice, a rate discussion, a pre-approval, a purchase application, a refinance or a renewal?
- Which date ranges does the lender require for pay stubs, bank statements and tax returns?
- Should documents be uploaded through a named portal, sent by encrypted email or delivered another way?
- Do you need every page of each statement, including pages marked blank?
- Which documents are needed from every borrower, guarantor or co-signer?
Providers can require different documentation. Ontario’s Financial Services Regulatory Authority expressly advises consumers to confirm details with their mortgage provider at its mortgage application guidance.
#1 Best Overall
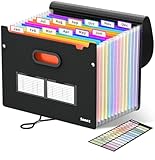
- Superior Durability: Featuring strong 100C thickened cover and reinforced edges, surpassing competitors in durability. Made from PVC-free, acid-free materials, ensuring secure organization of bills and documents while delivering unparalleled durability and reliability
- Deeper Pockets & Unobstructed Tabs: In response to a common issue in accordion folders where papers cover index labels, we've increased pocket height by 0.8 inches (2 cm). This unique enhancement ensures your labels remain visible—a feature unmatched by competitors
- Ample Capacity Monthly Bills Organizer: Our expandable monthly bill organizer can extend up to 14 inches, accommodating over 1500 sheets files while standing stable. With 12 pockets, it's perfect for storing tax records, bills, receipts, invoices and important family files for over a year
- Sticky Labels & 3 Loops Bungee Closure: Colorful monthly tabs and labels help you locate the target object at a glance and manage monthly tasks with ease. The elastic band closure with three loops expands generously to accommodate all your storage needs
- Unlock Versatile Organization: Whether at home, in the office, or on the go, it offers flexible organization for invoices, medical finance records, and identification documents, ensuring efficiency wherever you need it
The core mortgage-document packet
1. Identity and personal history
Prepare a current government-issued photo ID, such as a passport or driver’s licence, and any additional identity information the broker requests. You may also need:
- Your current address and recent address history.
- Names, addresses and dates for current and previous employers.
- Your Social Security number in the United States, or the local equivalent where requested.
- Legal name-change documents, such as a marriage certificate or court order, when your records use different names.
Identity requirements differ between US and Canadian applications and among lenders. Do not email an identification document to an unverified address; use the broker’s prescribed secure channel.
2. Income and employment evidence
For salaried employment, gather recent pay stubs or other salary confirmation and the employer’s name, address and contact details. In the United States, a lender may ask for W-2 forms or equivalent wage records. In Canada, the lender may request employment letters, pay statements or notices of assessment.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Income that is not a straightforward salary often needs a longer paper trail:
- Commission, bonus or overtime income: pay records and the history the lender specifies.
- Contract or freelance income: tax returns, business records and current profit evidence.
- Self-employment: personal tax returns, notices of assessment, business returns and profit-and-loss statements when requested.
- Pension, government benefits or other recurring income: award letters, statements or payment records.
- Rental income: leases, tax records or other proof of the amount and continuity.
Ask exactly which years and forms apply. Fannie Mae’s US educational checklist, for example, lists pay stubs from the most recent two months, W-2s for the last two years and two years of returns for self-employment, rental and commission income. Those are examples for its lending context, not a rule for every borrower. See Fannie Mae’s document list.
Rank #2

- Expanding file folder in Black with flap and cord closure for organizing and securing 8.5 x 11-inch letter-size documents
- Holds up to 260 sheets; 13 pockets for easy subdividing; each pocket expands to 7/8-inch
- Archival quality, acid free, and PVC free
- Waterproof and tear resistant
- Made of durable poly material
3. Assets and the source of your down payment
Bring recent statements for checking and savings accounts, investments, retirement accounts and any other assets you will use for the down payment, closing costs or required reserves. Statements should show the account holder, institution, account number or identifying portion, statement period and balance.
The lender also needs to understand how the money was accumulated and where it came from. Be ready to document:
Recommended Free Tools
- Personal savings and regular transfers between accounts.
- Proceeds from selling a property or another asset.
- Transfers from an investment or retirement account.
- Gift funds, usually with a signed gift letter or statement identifying the donor, amount and confirmation that repayment is not expected, subject to the loan program’s rules.
- Large recent deposits, with evidence explaining their source.
Never assume that a high account balance alone proves acceptable funds. The lender may trace the money’s path and ask for additional statements or sale documents.
4. Debts and recurring obligations
Create a complete list of liabilities, even if a balance is small or another person makes the payment. Include credit cards, student and personal loans, auto loans or leases, lines of credit, support payments, existing mortgages and other recurring obligations. The broker may request current statements, payment amounts, maturity dates and balances.
Accuracy matters because the lender uses your obligations to assess affordability. Tell the broker about debts opened, paid off or transferred since you last checked your credit report.
Rank #3

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
5. Property and transaction documents
If you have identified a home, bring the property address and listing, plus any signed purchase agreement and evidence of the deposit. Depending on the property and jurisdiction, useful records include property-tax information, heating costs, condominium or homeowners’ association fees, and plans or specifications for a new build.
For a refinance, renewal or lender switch, prepare your current mortgage statement or balance information. Ontario guidance also identifies a current mortgage statement or proof of clear title as relevant when changing lenders or renegotiating. Read the regulator’s examples at FSRA’s mortgage application process page.
6. Documents for special circumstances
Tell the broker early about facts that can change underwriting. Supporting records may be needed for self-employment, irregular or seasonal income, rental property, gifted funds, divorce or support obligations, bankruptcy, benefits, a recent job change or a co-borrower who lives elsewhere. These are situation-dependent examples, not a universal list.
How requirements change by borrower and transaction
| Situation | Documents commonly added or emphasized | What to clarify |
|---|---|---|
| Purchase | Property address, listing, offer or signed purchase agreement, deposit evidence and property-cost details | Whether the broker needs these before an initial assessment or only after an offer |
| Refinance or renewal | Current mortgage statement, outstanding balance, payment history and, for some lender changes, proof of clear title | Whether an appraisal, payout statement or discharge information will follow |
| Salaried borrower | Recent pay stubs, employer details and wage records such as W-2s or local equivalents | Required pay-stub period and treatment of bonus, commission or overtime |
| Self-employed or irregular-income borrower | Personal and business tax returns, notices of assessment, business statements, contracts and profit-and-loss records | Which tax years and whether interim accounts are acceptable |
| Personal savings | Recent bank and investment statements showing balances and transfers | How many months of history and how to explain large deposits |
| Gift or sale proceeds | Gift letter or donor confirmation; sale agreement and closing statement for asset-sale proceeds | Whether the specific loan program permits the source and what tracing is required |
| Initial estimate | Basic identity, income, assets, debts and transaction facts may be enough to start | What can be supplied later and what is needed for a formal application |
| Full application | Complete, current verification documents and explanations for inconsistencies | Refresh dates, page-completeness rules and the secure upload process |
US examples: checklist periods and the Loan Estimate rule
The Consumer Financial Protection Bureau’s US application-packet examples include a pay stub covering the last 30 days, W-2 forms and signed federal tax returns for the last two years, two recent bank statements, evidence of the down-payment source, identity documents and a Social Security number. The CFPB presents these as preparation guidance; a lender can request different or additional evidence for your circumstances. Its current checklist is at Create a loan application packet.
Fannie Mae’s educational list uses a different pay-stub example—two most recent months—and adds conditional items such as gift letters, bankruptcy papers, lease or rent proof and a sales contract. The difference illustrates why you should use the broker’s checklist rather than combine date ranges from several websites.
Free tools Windows power users keep installed
One-click scans. No signup required.
Rank #4

- Stable & sturdy construction: Expanding file folder is made from durable wipe-clean polypropylene. Acid-free and high-quality for using trustingly. Waterproof & sturdy enough to keep the file organizer from collapsing. The accordion folder's cord closure and adjustable flap provide additional security. Built-in file separation layers are flexible to ensure the files don't wrinkle.
- Handy organization & Easy lookup: Expandable file folder has 24 pockets designed for keeping our paperwork organized. Accurately classified storage in the specific color slot and labeled with tabs, so it is easier to find the papers what is needed.
- Plentiful storage: Product Size: 13'' L x 9.25'' H. Each pocket fits well for all A4/Letter size paper. Excellent scalability. The accordion file folder can be stretched pretty far, more than 24 inches. 24 pockets allow you to store more than 4000 sheets of paper documents.
- Portable & stylish: Classic lightweight folder organizer can be compressed to a minimum thickness of about 2 inches, so it can be held up great for traveling to and from all different locations for work. Fits perfectly when completely closed in the file cabinet. The dividing sections of the rainbow file folders come in six bright colors, stylish and beautiful. Versatile document organizer for home, office, school, and travel scenarios, compact and light.
- Expandable desktop folder: Folders can be expanded to different widths as the number of files you put into increases. Stand on its own on the desk and not easy to tip over when pulled out to maximum capacity and filled. Each pocket is completely sealed at the bottom to keep small objects do not move.
There is also an important US process distinction. Under CFPB guidance, a lender or mortgage broker cannot require documents such as a W-2 or pay stub as a condition of providing a Loan Estimate. Six pieces of information are sufficient to trigger that estimate. If you proceed with an application, the lender may request documents to verify what you reported. This rule is US-specific and does not establish what a broker in another country must do. See the CFPB’s Loan Estimate explanation.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Canadian examples: ask what the professional needs at the first interview
Canada Mortgage and Housing Corporation’s checklist covers government identification, address and employment information, income proof, down-payment sources, recent financial statements, current debts and property details when available. CMHC advises borrowers to ask the mortgage professional what to bring to the initial interview.
CMHC also states: “The most common reason for delays in getting approved for a mortgage is missing or incomplete information.” Read the guidance at CMHC’s mortgage application tips. The statement supports a complete packet, not a claim that every Canadian lender uses identical forms.
Assemble and submit the packet without creating delays
- Get the checklist first. Request the broker’s list in writing, including required date ranges, file formats, naming conventions and deadlines.
- Create a document inventory. Make a folder for identity, income, assets, debts, property and special circumstances. Record the statement period beside each file.
- Download complete records. Include every page of multi-page statements, even pages intentionally marked blank. Keep the originals and an untouched copy of everything submitted.
- Reconcile names and numbers. Check that names match across identification, tax records, bank accounts and purchase documents. Flag differences instead of altering a document.
- Explain unusual activity. Prepare a short, evidence-backed explanation for large deposits, transfers, employment gaps, gifted funds or recently paid debts.
- Check freshness before sending. Pay stubs and statements can become stale while a file is being reviewed. Ask when refreshed versions will be required.
- Use the prescribed secure channel. Confirm the upload portal or encrypted method, verify the recipient and retain submission confirmations.
- Track follow-up requests. Keep a dated list of every item sent and every outstanding question so that a replacement file does not omit a page.
The CFPB’s guidance on responding to lender requests is available at Submit documents and answer requests from the lender. If digital collection is offered, ask what service is used, what account data it can access and whether you can choose manual submission. Sharing financial data is your choice.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Common preparation mistakes and fixes
- Sending only the first page: download the full statement, including blank pages and transaction details.
- Using an old balance: ask whether the lender needs a newly issued statement or a current transaction printout.
- Ignoring a deposit: collect the transfer record, sale document or gift confirmation before underwriting asks.
- Leaving out a debt: disclose every recurring obligation, including support payments and leases.
- Mixing jurisdictions: do not apply a US document rule to a Canadian file, or vice versa, without confirmation.
- Uploading insecurely: avoid unverified links and ordinary email attachments when the broker provides a secure portal.
A paper accordion file can help organize copies for an in-person appointment, but it is optional and does not accelerate approval. Many lenders collect documents digitally; follow their secure-submission procedure instead.
Quick Recap
A practical day-before checklist
- Photo ID and any name-change records are current.
- Employer and address history is complete.
- Required pay stubs, tax forms and other income evidence are within the requested date range.
- Bank, investment and retirement statements show the funds you will use.
- Gift, sale-proceeds and large-deposit explanations are documented.
- Every debt and recurring payment is listed with accurate balances.
- Property, offer, deposit or current-mortgage documents are attached when relevant.
- Files are complete, legible, named clearly and ready for the broker’s secure channel.
- Originals remain in your possession.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




