
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →A mortgage servicing transfer changes the company that collects and administers your loan, not usually the loan itself. To avoid a missed payment, find the transfer’s effective date, identify the last day the old servicer will accept payments and the first day the new servicer will, then change every automatic or manual payment instruction. Keep both notices and verify the next statement. Federal rules also provide a limited 60-day protection: when the former servicer receives an on-time payment during that period, the payment cannot be treated as late or charged a late fee because it went to the old company.
What a mortgage servicing transfer changes—and what it does not
Mortgage servicing is the day-to-day administration of a loan. The servicer collects principal, interest and escrow, maintains the payment account, answers account questions and handles related records. A lender or loan owner can transfer those servicing rights to another company while the loan remains in place.
As an Amazon Associate I earn from qualifying purchases.
In the ordinary case, your interest rate, principal balance, maturity date, payment schedule, escrow obligations and other loan terms remain unchanged. The CFPB’s model notice expresses this plainly: “Nothing else about your mortgage loan will change.” Terms directly connected to servicing—such as where and how you pay—can change.
Free tools Windows power users keep installed
One-click scans. No signup required.
Read the letter as an operational handoff, not as a new loan offer. Your immediate job is to establish the handoff date, route the next payment correctly and preserve evidence of what you did.
#1 Best Overall

- Keep important documents safe: A document organizer designed to protect papers from getting lost. Store birth certificates, social security cards, wills, tax forms, insurance policies, titles & more in one secure place.
- Easy to organize and find: Folders with pockets and a table of contents help track where documents live, while 33 hand-illustrated labels show what to save. Acid-free materials protect your papers for years to come.
- Fits documents of various sizes: This document binder includes 3 vertical and 3 horizontal envelopes for 8.5 x 11 inch papers, plus 4 half-size envelopes for smaller keepsakes and important details.
- Practical and easy to use: An important document folder organizer with a front pouch that provides a quick landing space for papers before filing, making it easy to stay organized as documents come in.
- Premium quality, timeless style: Made with custom-dyed cloth, reinforced edges, and acid-free paper for long-term durability. An elegant file organizer designed to beautifully complement your office or living room décor.
Use this checklist while reading the notice
Put the notice beside your most recent mortgage statement. Confirm each item before changing payment instructions.
| Item to verify | What the notice should tell you | Why it matters |
|---|---|---|
| Effective transfer date | The date responsibility moves from the former servicer to the new servicer. | It controls when payment instructions change and when the 60-day transition protection begins. |
| Former servicer’s final acceptance date | The last date the old company will accept a payment for normal processing. | A check or electronic payment sent near the changeover can otherwise be routed incorrectly. |
| New servicer’s first acceptance date | The first date payments should be sent to the new company. | This is the destination for your next payment after the handoff. |
| New servicer identity and address | Legal or business name, payment or correspondence address and a toll-free or collect-call transfer-help number. | Use the address and account format in the notice, not an address copied from an old statement. |
| Former servicer identity and address | Name, address and a toll-free or collect-call number for transfer questions. | You may need the former company to trace a payment or forward it. |
| Optional insurance instructions | Whether mortgage life, disability or other optional coverage is affected and what you must do to keep it. | A servicing change can require a new payment or confirmation even when the mortgage payment itself is unchanged. |
| Unchanged-loan statement | A statement that the transfer does not change other loan terms or conditions. | It distinguishes a servicing handoff from a modification, refinance or sale of the loan terms. |
If a letter omits a required detail or conflicts with your statement, call both companies using numbers from their official correspondence. Do not infer a payment destination from an unfamiliar logo, a search result or a forwarded email.
Understand the dates and notice timing
Effective date
The effective date is the anchor for every other instruction. It is the date the new servicer assumes servicing responsibility. Write it on a calendar and save a copy of the notice with the envelope or electronic delivery record.
Old and new payment-acceptance dates
The former servicer’s final acceptance date and the new servicer’s first acceptance date must be the same day or consecutive days. For example, an old-servicer final date of June 30 and a new-servicer first date of July 1 is a normal sequence. A gap of several days, or overlapping instructions that do not explain how payments are handled, deserves clarification before you send money.
General notice windows
In the general case, the former servicer sends its notice at least 15 days before the effective date. The new servicer sends its notice within 15 days after that date. The companies may instead send one combined notice at least 15 days before the transfer.
That schedule is not universal. Different timing can apply when servicing is terminated for cause, during bankruptcy proceedings or in specified Federal Deposit Insurance Corporation or National Credit Union Administration actions. If your letter cites one of those situations, follow the specific dates in the notice and ask the servicer to explain any unusual schedule.
Rank #2
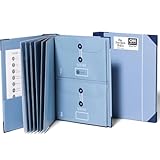
- Keep important documents safe: A document organizer designed to protect papers from getting lost. Store birth certificates, social security cards, wills, tax forms, insurance policies, titles & more in one secure place.
- Easy to organize and find: Folders with pockets and a table of contents help track where documents live, while 33 hand-illustrated labels show what to save. Acid-free materials protect your papers for years to come.
- Fits documents of various sizes: This document binder includes 3 vertical and 3 horizontal envelopes for 8.5 x 11 inch papers, plus 4 half-size envelopes for smaller keepsakes and important details.
- Practical and easy to use: An important document folder organizer with a front pouch that provides a quick landing space for papers before filing, making it easy to stay organized as documents come in.
- Premium quality, timeless style: Made with custom-dyed cloth, reinforced edges, and acid-free paper for long-term durability. An elegant file organizer designed to beautifully complement your office or living room décor.
Where a mailed notice is sent
A mailed notice generally goes to the address in your mortgage documents unless you properly notified the servicer of a new address. If you moved and did not update the account, contact both servicers immediately and request duplicate notices and confirmation of the address on file.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteChange payment instructions without creating a gap
- Mark the changeover on your calendar. Record the effective date, the old servicer’s final acceptance date, the new servicer’s first acceptance date and your contractual due date and grace period.
- Wait for usable new-account information. The new notice should provide the account number or payment reference, payment address and electronic-payment instructions. If the new account number differs, do not assume the old number will work indefinitely.
- Update bank or credit-union bill pay. Edit the payee name, mailing address, account number and delivery date. A bank’s “send on” date is not the same as the date the servicer receives a check, so allow mailing time.
- Replace recurring electronic debits. If the old servicer pulls payments automatically, follow the new servicer’s enrollment process. Do not leave both authorizations active unless each company confirms which one will be used; duplicate debits can create an avoidable overpayment.
- Schedule the next payment conservatively. Send it to the new servicer on the normal due date or earlier, using the notice’s method. Do not delay simply because the 60-day protection exists.
- Save proof. Keep confirmation numbers, screenshots, bank transaction records, check images, postal tracking and copies of correspondence. Note the date, time, representative’s name and case number for every call.
- Inspect the next monthly statement. Confirm that the payment was credited to the correct loan, principal, interest and escrow fields, and check for an unexplained late fee, suspense balance or returned-payment charge.
If the new servicer has not provided a way to pay by the time a payment is due, contact it and the former servicer promptly. Ask for written instructions and document that you attempted to pay on time.
Know the 60-day protection for payments sent to the former servicer
For 60 days beginning on the effective transfer date, a payment that the former servicer receives on or before its due date—including any grace period in your loan documents—cannot be treated as late for any purpose. The CFPB’s official interpretation says this prohibition includes imposing a late fee. The model notice states: “Under Federal law, during the 60-day period following the effective date of the transfer of the loan servicing, a loan payment received by your old servicer on or before its due date may not be treated by the new servicer as late, and a late fee may not be imposed on you.”
This is a narrow transition rule, not a payment holiday. Pay on time, use the new instructions and keep delivery evidence. The protection applies when the former servicer receives the payment on time; it does not excuse a late payment, a missed payment or a payment sent to an unrelated account.
When the former servicer receives a payment that should go to the new servicer after the transfer, the regulation requires the former servicer to act promptly: it must either forward the payment for account application or return it and tell you who should receive it.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →If a payment is missing, late-coded or misapplied
Start with a two-servicer trace
Call the former and new servicers as soon as the statement looks wrong. Give each company the payment date, amount, method, confirmation or check number, destination, delivery evidence and the loan account number used. Ask whether the payment is being held in suspense, returned, forwarded or posted under a different account number.
Rank #3

- Store (Family) Papers Safe & Sound: Keep all your essential papers safely in one spot with ZICOTOs’ important document organizer. Swiftly locate anything from legal to medical papers for the whole family. Ditch the paper chaos, embrace order & enjoy the simplicity with the Zicoto expanding file folder
- Organize It Like a Pro: Get super organized with 8 large, numbered envelopes (9.5x12”), each holding 40+ letter-sized sheets. Perfect for documents, passports, photos, and more. The document folder organizer transforms your paper clutter into a masterpiece of order!
- Customize to Your Needs: The important document folder organizer binder lets you label each section your way with a customizable table of contents, numbered envelopes and a sticker sheet with blank & pre-named stickers. Your Binder, your way - organizing has never been this easy!
- Ample Space for Everything: The 13x11.22” document organizer folio is perfect for your 8.5x11" letter size or A4 papers. Need more room? No worries, the life binder includes a handy back pocket for extra documents, notes and more. Keep everything neatly stored and easily accessible
- Stylish & Practical Premium Design: Featuring a chic striped cover in modern sage with elegant gold foil text and classy golden edges, the expanding file folder looks as good as it functions. An elastic band keeps everything in place - no more loose papers flying around!
Send a written information request or notice of error
CFPB consumer guidance says a borrower experiencing a transfer-related problem may send both servicers an information request or a notice of error. Send the correspondence to the address designated for those requests—not necessarily the payment address shown on a coupon. Describe the specific payment, explain why the posting is wrong or information is missing, attach copies rather than originals and request correction and an account history. Use a trackable delivery method and retain the receipt.
Protect the next payment while the dispute is reviewed
Continue making the next undisputed payment according to the current instructions. A dispute about one transaction does not suspend future obligations. If a servicer tells you to send a replacement payment, ask in writing how the first payment will be credited or returned so you do not pay twice.
Escalate with a complete record
If the account is not corrected, organize the notices, statements, payment confirmations, call log and written correspondence in date order. You can submit a complaint to the Consumer Financial Protection Bureau and provide that record. Keep communicating with the servicers while the complaint is pending.
How to compare two notices
Sometimes the former and new companies send separate letters, or a corrected notice arrives. Compare them line by line rather than choosing the most convenient address.
| Comparison point | Questions to ask | Action when they differ |
|---|---|---|
| Effective date | Do both notices identify the same transfer date? | Call both servicers and request written confirmation before scheduling a payment. |
| Payment acceptance dates | Are the old final date and new first date the same or consecutive? | Ask which company will receive a payment mailed during the disputed window. |
| Servicer names and addresses | Are the legal names, payment addresses and account references consistent? | Use only an address confirmed by the servicer handling your account for that date. |
| Telephone numbers | Does each notice provide a toll-free or collect-call transfer number? | Call both numbers and record the case numbers and instructions. |
| Insurance | Do the notices agree about optional coverage? | Contact the insurance provider and servicer before canceling or redirecting premiums. |
| Loan terms | Does each notice say terms and conditions remain unchanged? | Ask for an explanation if a letter claims a rate, balance or due date has changed. |
Optional insurance needs its own check
Mortgage life, disability and other optional insurance may be billed or administered alongside servicing. Look for a specific statement about whether coverage is affected. If action is required, follow the stated deadline and obtain confirmation that coverage continues. Do not stop an insurance premium merely because the mortgage payment address changed, and do not assume the servicer can answer policy questions that belong to the insurer.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Common mistakes and practical fixes
- Changing the payee but not the delivery date: A bill-pay check may still arrive after the due date. Move the send date early enough for delivery.
- Using a web address found independently: A similar name can lead to an incorrect account. Use the payment portal or address identified in the notice and verify it by phone.
- Paying both servicers: Duplicate payments can complicate escrow and principal accounting. Ask for written instructions before sending a second payment.
- Relying on the 60-day rule to pay late: The protection covers a qualifying payment received on time by the former servicer; it is not permission to wait.
- Discarding the old statement: The former statement helps prove the balance, due date and payment history. Keep it with the transfer notice.
- Ignoring a suspense balance: A payment can be received but not fully applied. Ask how much is held, why it is held and what action will release it.
- Assuming unchanged terms means unchanged contact details: Loan terms generally stay the same, but the payment address, portal and customer-service process can change immediately.
A simple transfer timeline
Before the effective date
Read both notices, verify the dates and contact details, update bill pay or automatic debit instructions, and schedule the next payment with delivery time.
Rank #4

- Fireproof & Water‑Resistant:ZOOPIP fireproof 3-ring binder is made of anti-static, double-layered, non-itchy silicone-coated fiberglass that has passed the UL94 VTM-0/5VA flame-retardant test. The rigid hard shell protects birth certificates, passports, and vehicle titles from crushing and bending, while the fiberglass outer layer resists splashes and rain. A double zipper keeps the case closed so documents stay organized and nothing falls out. Splash-resistant only — do not submerge in water
- Heavyweight Pocket Folders :Designed for durability and organization, these letter-sized (8.5” x 11”) folders feature three-hole punches for easy binder integration and a generous capacity for extensive documents. Made of sturdy, acid-free polypropylene, each side-opening pocket with hook-and-loop tabs holds several sheets securely. External label slots let you sort tax, medical, and warranty documents at a glance. Available in 6 colors
- Security & Portability Combined: Made for Estate Planning, Family Records and Grab-and-Go Emergencies – One place for the paperwork you can never replace: deeds, wills, Social Security cards, insurance policies and passports. The built-in 3-digit combination lock keeps casual eyes out, and the carrying handle lets you grab the whole case and go when you need to evacuate fast
- Large Binder Organizer:(14.5"×12.4"×3.1") Works as your complete storage organizer. Its built-in zippered pouch safely stores small-sized necessities like pens, USB flash drives, and charging cords. The spacious interior easily fits over 400 sheets of paper, keeping your paperwork, stationery, charts, invoices, and photos neatly organized
- After-Sale Service: ZOOPIP stands behind every fireproof product we make. Please note: This flame retardant test does not mean the product is designed to withstand prolonged, direct exposure to fire indefinitely. If you encounter any quality issues, please contact us — we'll make it right
On and immediately after the effective date
Use the new servicer’s payment channel, save confirmation and watch for the first statement. If the former servicer receives a payment intended for the new company, it must forward it or return it with directions.
Recommended Free Tools
During the following 60 days
Monitor statements and bank records closely. If the former servicer received an on-time payment, preserve proof and invoke the transition protection if the new account shows a late status or fee.
After the first statement is correct
Keep the notice, statement and payment confirmation with your loan records. Continue checking statements under the new servicer; the transfer protection ends after the 60-day period.
What to keep in your mortgage file
An expanding file or digital folder is sufficient; no special product is required. Store the transfer notice, envelope or delivery record, recent statements, updated payment instructions, bank confirmations, check images, call notes and written requests. A chronological file lets you show exactly when notice arrived, where you sent money and how each servicer responded.
Primary rules behind the notice
The requirements described here come from the CFPB’s current text of 12 CFR § 1024.33, “Mortgage servicing transfers,” Appendix MS-2 to Part 1024 (the model Notice of Servicing Transfer), the CFPB consumer guidance “What happens if the company that I send my mortgage payments to changes?” last reviewed April 3, 2024, and the CFPB’s official interpretation of § 1024.33. Those materials establish the notice contents, general timing, payment-forwarding duty and 60-day no-late-treatment and no-late-fee protection.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




