
Prepare complete, bank-generated statements for every account the lender asks about, then document the true source and destination of any deposit or transfer that could affect your down payment, closing costs, or reserves. Ask your loan officer or processor which accounts and statement periods apply to your loan, because requirements differ by lender, loan program, purchase versus refinance, and underwriting channel. Send documents promptly, keep copies, and never alter, redact, backdate, or recreate a financial record.
What to gather before submitting your statements
Start with the lender’s document request rather than assuming every mortgage uses the same checklist. The Consumer Financial Protection Bureau (CFPB) says requirements vary and advises borrowers to respond quickly when the lender requests information. Confirm:
As an Amazon Associate I earn from qualifying purchases.
- Which checking, savings, brokerage, retirement, or other asset accounts must be documented.
- How many statement periods are required and the lender’s cutoff date.
- Whether electronic PDFs, secure uploads, or another format is accepted.
- Whether the lender wants statements for accounts used for the down payment, closing costs, earnest money, or reserves.
- How the lender wants explanations and supporting records submitted.
Download statements directly from the financial institution. Save the original PDF files and, if requested, provide every page, including pages that contain no transactions. Do not submit screenshots or edited files when a complete bank-generated statement is available.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
What a complete bank statement should contain
Fannie Mae’s Selling Guide identifies the elements its underwriting process expects on bank or investment statements:
#1 Best Overall

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
- The financial institution’s name.
- The borrower as the account holder.
- At least the last four digits of the account number.
- The statement’s covered period.
- Transaction activity for that period.
- The ending balance.
Fannie Mae says statements typically cover the most recent two months. Its guide also says that when the latest statement is more than 45 days old at application, the lender should request a more recent, bank-generated supplemental form showing at least the last four account digits, balance, and date. That is a Fannie Mae guideline, not a universal rule. Your lender may request a different period or additional activity.
Use the statement exactly as issued
Do not crop out deposits, transfers, overdrafts, account identifiers, or pages that appear irrelevant. Do not change a PDF, move money between accounts solely to make activity look simpler, or remove a transaction because it seems embarrassing. Underwriters need an authentic record to determine whether the funds are available, acceptable, and connected to any debt obligation.
Review your statements for items likely to prompt questions
Before uploading anything, mark transactions that need a clear explanation. Review each statement line by line and make a short inventory containing the date, amount, account, description, actual source, and final destination of the money.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11- Large one-time deposits.
- Transfers between your own accounts.
- Money from another person.
- Proceeds from selling a vehicle, jewelry, securities, or another personal asset.
- Earnest-money payments.
- Cash deposits, third-party checks, or deposits with vague descriptions.
- Recent funds that do not have an obvious paper trail.
- Unusual statement dates, gaps, or out-of-sequence statements.
- Payments or deposits suggesting borrowed funds or a new liability.
Fannie Mae describes a large deposit as a single deposit greater than 50% of total monthly qualifying income. For a purchase, when those funds are needed for the down payment, closing costs, or reserves, the lender must document an acceptable source under its guidance. This threshold is a Fannie Mae policy definition, not a general rule for every mortgage.
A deposit is not automatically unacceptable because it is large. The key questions are where it came from, whether it is permitted for the transaction, and whether it was borrowed. A loan that must be repaid can affect debt-to-income calculations and must not be disguised as savings or a gift.
Rank #2

- Zipper Closure for True Security: Unlike folders using elastic bands that can let contents slip out, our expanding file folder features a dependable zipper closure, ensures everything stay safely secured inside, safe and sound. No more worries about losing small items.
- Sleek Design with Fresh Colors: 4 assorted pastels colored add a soft, delicate touch (purple, pink, sky blue, green). The black and gray hues present you a professional image. The tactile pattern exterior enhances and enriches the bright on trend colour-way.
- Unrivaled Durability: Say hello to an excellent all-rounder for secure and long-lasting storage. Made of PP tough shell (42% thickness upgraded) that endures daily handling and wear, and never tears. Acid-free, PVC-free. The metal zipper pull and reinforced edge construction offer reliable usage over time.
- Truly Large Capacity: 14 x 11.2 inches. Fit A4/letter size. This portable file organizer with expandable spine design is more stretchy to fit over 400 sheets without bulking up too much. Convenient size to carry around. Easily take your paperwork to a meeting or school.
- Monthly labels for Quick Retrieval: Customizable pastels stickers and 13 tabbed pockets allow you to sort by subject or task, bonus monthly labels increase its ease of locate and access.
Fannie Mae and Freddie Mac do not use identical rules
Mortgage underwriting rules depend on the channel handling your loan. Fannie Mae’s purchase guidance uses the more-than-50%-of-monthly-qualifying-income definition described above. Freddie Mac’s cited purchase guidance uses a different calculation based on qualifying income and, where applicable, an asset-calculation amount. Do not combine the agencies’ formulas or tell a borrower that Fannie Mae’s threshold applies to every loan.
The distinction also matters because Fannie Mae treats purchase and refinance transactions differently when evaluating large-deposit explanations, while still requiring the lender to consider borrowed funds. Ask which agency and loan program apply to your file before deciding that a transaction needs no documentation.
Free tools Windows power users keep installed
One-click scans. No signup required.
Match each transaction to the right evidence
Transfer between your own accounts
Provide statements or lender-approved records showing the money leaving the first verified account and arriving in the second. The dates and amounts should reconcile, allowing for any clearly documented processing delay. If the incoming statement clearly identifies a transfer between verified accounts, Fannie Mae says additional explanation may not be needed under its guidance; the lender can still request proof if the description is incomplete or borrowing is a concern.
Gift from a relative or another donor
State who provided the money, when it was provided, and whether it is a gift that does not require repayment. Ask the lender for its required gift letter and transfer documentation. A wedding invitation or similar evidence can provide context in a case where the borrower lacks usual documentation, but it does not replace the lender’s required records. Never call borrowed money a gift.
Sale of a personal asset
Explain what you sold, when ownership transferred, the sale price, and when you received the proceeds. Fannie Mae says personal-asset proceeds can be an acceptable source when the buyer is not involved in the property sale or mortgage transaction. Depending on the circumstances, the lender may document ownership, value, transfer of ownership, and receipt of proceeds. Possible records include a bill of sale, purchaser statement, deposit record, bank statement, or canceled check.
Rank #3

- High-Quality Materials: Protect your files with ENGPOW fireproof accordion file organizer.It is made of 3-layered non-itchy silicone-coated fiberglass which withstand the temperature up to 2200℉.It has passed the UL94 -V0/5VA flame retardant test.Fireproof File Folder is fireproof&Water-resistant,which can effectively protect your important documents in a fire,flood,and wet weather. They will further keep your files intact.Giving you time to save your important documents when disaster strikes
- Accordion File Organizer: A Safe Enough Folder to Keep Your Files. Say goodbye to cluttered files and disorganization with ENGPOW's file organizer folders. Compared with other folders,our fireproof folders is allows you to neatly store and classify letter/A4 files, receipts, cards, USB drives, pen, passports and more in a safe and orderly way. Perfect for daily file filing and storage.The Non-dusty material can prevent dust from sticking to the outside of our folder,always keep it neat and tidy.
- Large Capacity: 14.2" x 10.4" x 2", Compared with other folders, our Accordian File Organizer adopts a multi-layer design that can meet all your storage needs.These include 13 accordion Pockets with labels(each expanding to 1.2 inches),1 zipper pocket,2 pen slot,6 card slots,4 small mesh bags,4 medium mesh bags,and 1 main pocket. You can securely store all your important documents and other items in this fireproof expanding file folder while effectively classifying and finding your files.
- Innovative Humanized Design: Design with a strong grab handle for carrying everything you needed easily. Featuring a double zipper for convenient opening and closing,you won't have to worry about losing any important documents. The included colorful labels make categorizing your files effortless. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place.
- Trusted after sales service: In the event of an emergency, our fireproof accordion file organizer folders are lighter, easier to carry than fireproof safes and quick to grab and go. We only wish to present the best to customers,to protect your valuables.If there any quality problem, please feel free to let us know.We promise to arrange a REPLACEMENT or 100% REFUND immediately. Ready to respond within a 24 hour time,your suggestion has a great impact on the upgrade of our products.
Earnest-money deposit
Identify the amount, date, and account used to pay the deposit. Fannie Mae identifies a sales-contract deposit as an acceptable source for down payment and closing costs. The lender may need evidence that the money came from your account and proof that the escrow holder or seller received it, such as a canceled check or the holder’s written statement. An unusually high earnest-money amount should receive especially careful review.
Recommended Free Tools
Payroll deposit or tax refund
Point to the statement entry and, if requested, provide the matching pay record, employer record, tax return, or refund notice. Under Fannie Mae guidance, a readily identifiable payroll or tax-refund deposit printed on the statement may not need additional source documentation. The lender can still ask for confirmation if the description is unclear or the funds appear borrowed.
Cash, third-party, or unclear deposit
Describe only what you can prove. Tell the lender that the source is unclear or that a record is missing, and ask what alternative evidence it will accept. Do not relabel cash as a gift, a transfer, or reimbursement merely because that explanation would be easier to document.
How to write an explanation of deposit or transaction
There is no single universal borrower-letter form. A concise explanation should let an underwriter reconcile the statement entry with the supporting records without searching through unrelated material.
- Identify the account. Use the account holder’s name and only the account-identifying details the lender requests, such as the last four digits.
- Quote the statement entry. Give the transaction date, amount, and description exactly as shown.
- State the true source. Explain whether the money was payroll, a tax refund, a transfer, a gift, sale proceeds, earnest money, or another source.
- Explain the purpose. Say why the money was received and whether it is being used for the down payment, closing costs, reserves, or another expense.
- Address repayment. State whether the money was borrowed. If it was borrowed, disclose the obligation and ask the lender how it must be documented.
- List attachments. Name each supporting file and, where useful, identify the page containing the matching entry.
- Disclose gaps. If a record is unavailable, say so plainly and ask what substitute the lender will consider.
Practical example
Account ending 4821 — deposit dated June 12, 2026 — $8,500. “This deposit is the proceeds from the sale of my 2018 vehicle to an unrelated buyer. The vehicle was owned by me, the bill of sale was signed June 10, and the buyer paid by check. The funds were deposited into this account on June 12 and will be used toward closing costs. Attached are the bill of sale, the canceled check, and the statement page showing the deposit.”
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Clear out junk files and repair common Windows errors3Fix the driver behind crashes, sound loss and screen glitchesRank #4
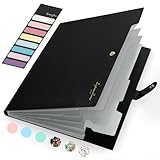
- Eye-Catching Colors: Designed to stand out, this folder combines fresh, vibrant hues with sleek patterns, making organization not just functional but stylish. Perfect for adding a touch of charm and energy to your workspace
- Upgraded Spine for Larger Capacity: Our accordion file organizer with expandable spine design is more stretchy to fit over 250 sheets without bulking up too much. Unlike regular spines that can easily get dented, our spine is made for quality and not easy to deform in transit
- Easy Organization: This expanding file folder makes sorting and organizing your papers a breeze. Featuring 5 pockets with tabs and colorful labels for quick sorting and retrieval
- Made to Last: Reinforced plastic document folders resists tearing and creasing, with a secure snap closure to keep papers in place
- Portable & Lightweight: 13 x 9.5 inches. Fit A4/letter size documents. Compact and lightweight for easy carrying. Easily take your paperwork to a meeting or school
Use the example’s structure, not its facts. Your explanation must describe your actual transaction and attach records that genuinely support it.
Submission workflow: a reliable step-by-step process
- Get the request in writing. Ask the loan officer or processor for the accounts, periods, file format, and upload channel required for your loan.
- Download complete statements. Obtain bank-generated PDFs or other lender-approved records directly from each institution. Include all pages and transaction activity.
- Check freshness. Compare the statement ending date with the lender’s application date and ask whether a newer supplemental statement is required.
- Reconcile the funds. Match the balance and transactions to the amount you intend to use. Trace transfers from the original account to the receiving account.
- Build a transaction index. Record each date, amount, source, destination, and supporting filename.
- Collect source records. Gather transfer statements, gift documents, sale records, canceled checks, escrow receipts, payroll records, or tax documents as applicable.
- Write separate explanations. Keep each explanation focused on one transaction and use the same dates and amounts shown on the statements.
- Upload through the requested channel. Use the lender’s secure portal or other specified method. Do not email sensitive records unless the lender directs you to do so.
- Keep a submission copy. Retain the exact files and explanations you sent, plus the date of submission.
- Answer follow-ups promptly. If the processor asks for another page or clarification, respond quickly and consistently with the original records.
Common problems and how to fix them
A statement is missing a page
Download it again from the institution or request an official copy. Tell the processor that the page was unavailable rather than submitting an incomplete file without explanation.
The latest statement is too old
Ask whether the lender needs a newer bank-generated statement or supplemental form. Fannie Mae’s guide references a more-than-45-day freshness issue in its process, but your lender may apply a different timing rule.
The transfer amount does not match
Check for partial transfers, fees, multiple transactions, or posting-date differences. Provide both account records and explain the reconciliation instead of submitting only the receiving account.
You cannot obtain the original source record
State what is missing, explain what you do know, and ask which alternative evidence is acceptable. Do not create a replacement document after the fact.
Best Value

- Stable & sturdy construction: Expanding file folder is made from durable wipe-clean polypropylene. Acid-free and high-quality for using trustingly. Waterproof & sturdy enough to keep the file organizer from collapsing. The accordion folder's cord closure and adjustable flap provide additional security. Built-in file separation layers are flexible to ensure the files don't wrinkle.
- Handy organization & Easy lookup: Expandable file folder has 24 pockets designed for keeping our paperwork organized. Accurately classified storage in the specific color slot and labeled with tabs, so it is easier to find the papers what is needed.
- Plentiful storage: Product Size: 13'' L x 9.25'' H. Each pocket fits well for all A4/Letter size paper. Excellent scalability. The accordion file folder can be stretched pretty far, more than 24 inches. 24 pockets allow you to store more than 4000 sheets of paper documents.
- Portable & stylish: Classic lightweight folder organizer can be compressed to a minimum thickness of about 2 inches, so it can be held up great for traveling to and from all different locations for work. Fits perfectly when completely closed in the file cabinet. The dividing sections of the rainbow file folders come in six bright colors, stylish and beautiful. Versatile document organizer for home, office, school, and travel scenarios, compact and light.
- Expandable desktop folder: Folders can be expanded to different widths as the number of files you put into increases. Stand on its own on the desk and not easy to tip over when pulled out to maximum capacity and filled. Each pocket is completely sealed at the bottom to keep small objects do not move.
The deposit came from cash or an unrelated person
Do not guess at its classification. Identify the facts you can establish and ask the lender whether the funds can be used and what documentation is required.
The lender’s request conflicts with advice found online
Follow the instructions for your actual loan file. CFPB information is borrower-facing, while Fannie Mae and Freddie Mac Selling Guide provisions apply to their respective underwriting channels and are not universal rules for every mortgage.
What underwriters are trying to establish
The review is designed to establish that the assets are real, available, and acceptable for the transaction, and that any liability connected to the money has been accounted for. Fannie Mae flags unusual statement dates or sequences and recent funds without a plausible paper trail or explanation as issues warranting attention. Complete, authentic records address those concerns better than a polished but incomplete narrative.
Keep the focus on traceability: the original account, the movement of funds, the final account, and the documents that explain why the transaction occurred. A clear explanation cannot make an ineligible source acceptable, but it can prevent an ordinary, well-supported transaction from becoming an avoidable underwriting delay.
Final submission checklist
- Every requested account is included.
- Each statement is bank-generated, complete, legible, and unedited.
- The institution, account holder, covered period, transaction activity, and ending balance are visible.
- Statement dates meet the lender’s freshness requirement.
- Large deposits and unusual transactions are indexed.
- Transfers are supported by records from both accounts when needed.
- Gifts, asset sales, earnest money, payroll, and refunds have the appropriate evidence.
- Borrowed funds and related liabilities are disclosed.
- Explanations use exact dates and amounts and identify attachments.
- Missing records are disclosed, with an alternative requested from the lender.
- You retained copies of everything submitted.
Frequently Asked Questions
How many months of bank statements do mortgage lenders require?
The period varies by lender and loan program. Fannie Mae says bank statements typically cover the most recent two months, but your processor may request a different period or newer supplemental documentation.
What is a large deposit for a mortgage?
Fannie Mae defines one as a single deposit greater than 50% of total monthly qualifying income. Freddie Mac uses a different calculation, and neither definition is universal across all mortgages.
Do I need to explain a transfer between my own accounts?
Provide records showing the money leaving one verified account and arriving in the other when the source is not already clear. An incoming statement that clearly identifies a transfer between verified accounts may need no further explanation under Fannie Mae guidance.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




