
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteThe strongest mortgage applications are accurate, explainable and affordable. Before you apply, review your credit reports, correct errors, calculate a housing budget that includes ownership costs, collect complete income and asset records, document every source of down-payment money, avoid unnecessary new credit and compare several lenders on the same assumptions.
This guide is for U.S. borrowers. Mortgage requirements differ by loan program, lender and borrower circumstances, so use these steps to prepare and then ask a loan officer for a current, situation-specific checklist.
As an Amazon Associate I earn from qualifying purchases.
1. Start with your credit reports
Credit information can affect whether you qualify and the interest rate a lender offers. Pull your reports from each major credit-reporting bureau well before submitting an application, then inspect every account, balance, payment history and personal detail.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Dispute errors early
Look for accounts you do not recognize, payments shown as late when you paid on time, incorrect balances, duplicate debts, outdated negative information and identity details that belong to someone else. File disputes with the appropriate bureau and the company that supplied the information, and keep copies of your dispute and supporting records. Resolving an error can take time, so do not wait until underwriting is underway.
#1 Best Overall
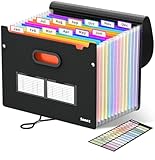
- Superior Durability: Featuring strong 100C thickened cover and reinforced edges, surpassing competitors in durability. Made from PVC-free, acid-free materials, ensuring secure organization of bills and documents while delivering unparalleled durability and reliability
- Deeper Pockets & Unobstructed Tabs: In response to a common issue in accordion folders where papers cover index labels, we've increased pocket height by 0.8 inches (2 cm). This unique enhancement ensures your labels remain visible—a feature unmatched by competitors
- Ample Capacity Monthly Bills Organizer: Our expandable monthly bill organizer can extend up to 14 inches, accommodating over 1500 sheets files while standing stable. With 12 pockets, it's perfect for storing tax records, bills, receipts, invoices and important family files for over a year
- Sticky Labels & 3 Loops Bungee Closure: Colorful monthly tabs and labels help you locate the target object at a glance and manage monthly tasks with ease. The elastic band closure with three loops expands generously to accommodate all your storage needs
- Unlock Versatile Organization: Whether at home, in the office, or on the go, it offers flexible organization for invoices, medical finance records, and identification documents, ensuring efficiency wherever you need it
A self-check does not lower your score
Checking your own credit report is a consumer-initiated review and does not hurt your credit score. A lender’s credit review is different: it creates an inquiry that can be visible on your report and may be considered by scoring models.
Do not chase a universal score target
There is no single credit-score minimum that applies to every mortgage. Loan type, lender policy, the rest of your application and the strength of your verified finances all matter. Use your report to find and fix problems rather than treating one advertised number as a guarantee of approval or a particular rate.
2. Keep mortgage shopping inquiries in context
Do not apply for unrelated credit cards, personal loans or auto financing shortly before or during the mortgage process unless a lender tells you it is necessary. Opening accounts can change your credit profile, add monthly obligations and create documentation questions.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11The Consumer Financial Protection Bureau says multiple mortgage-lender credit checks made within a 45-day window are recorded on the credit report as a single inquiry. That is a rule for mortgage shopping during that window, not a promise that all inquiries or all scoring effects are identical. Ask lenders to pull credit for the mortgage purpose and keep your applications within a deliberate shopping period.
3. Build a realistic housing budget
Approval and affordability are different decisions. A lender evaluates whether your documented finances support repayment; you must decide whether the proposed home fits your life after the loan closes.
Count the full cost of ownership
Start with the expected principal-and-interest payment, then add property taxes, homeowners insurance and any applicable mortgage insurance, association dues or other recurring charges. Set aside room for utilities, maintenance, repairs, moving expenses and closing costs. These costs can make a home that appears affordable from the mortgage payment alone uncomfortable in practice.
List existing obligations
Write down every recurring debt payment, including credit cards, student loans, auto loans, personal loans, support obligations and other commitments. Include minimum required payments rather than optimistic assumptions about paying balances down later. Compare the resulting monthly total with stable household income and the cash you need to keep after closing.
Protect a cash reserve
Do not commit every available dollar to the down payment and closing. A reserve helps absorb an insurance increase, repair, job interruption or other bill without immediately relying on new credit. The amount you need depends on your circumstances; your lender can explain what assets must remain available for the selected loan.
Rank #2

- Expanding file folder in Black with flap and cord closure for organizing and securing 8.5 x 11-inch letter-size documents
- Holds up to 260 sheets; 13 pockets for easy subdividing; each pocket expands to 7/8-inch
- Archival quality, acid free, and PVC free
- Waterproof and tear resistant
- Made of durable poly material
4. Understand what lenders verify
Lenders generally assess verified ability to repay. CFPB consumer guidance identifies current income or assets, employment status, credit history, the proposed mortgage payment and related expenses, other debts, and debt-to-income ratio or residual income among the considerations. The lender’s calculation is not a substitute for your own budget.
Expect questions when income is variable, employment has changed, deposits are unusual or an obligation is missing from an initial application. Provide a consistent explanation and documentary support instead of estimating or omitting information. A complete, accurate file is easier to underwrite than one that must be repeatedly corrected.
5. Assemble a complete application packet
Gather records before you apply and keep them current. CFPB guidance emphasizes that documents should be accurate and complete:
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
| Category | Typical records to prepare | Important qualification |
|---|---|---|
| Employment and wages | Recent pay stub and two years of W-2 forms | The lender may request a different period or additional verification. |
| Tax filings | Signed federal tax returns when applicable | Self-employed or variable-income borrowers may need schedules and extra years or records. |
| Bank and investment assets | Recent bank statements and relevant investment-account statements | Include every page, including pages that appear blank, and be ready to provide updated statements. |
| Down-payment funds | Records showing where the money came from and how it moved into the account | Large deposits, transfers and gifts require an explanation and supporting evidence. |
| Identity and property | Government identification and information about the property and requested loan | Your lender will specify acceptable documents and secure submission methods. |
Retain original records and submit copies through the lender’s requested secure channel. A digital folder with clearly named files works as well as a paper file organizer; the goal is a complete, retrievable packet.
Include every page
Do not remove blank or advertisement pages from a multipage statement. Omissions can make a document look incomplete and trigger a re-request. Save the full PDF or scan, including the statement date and account holder information.
Expect updates
Documents can become stale while you shop or wait for underwriting. Keep obtaining new pay stubs and statements, and do not assume the first packet will be sufficient. Your lender may ask for clarification or a more recent version after you choose to proceed.
6. Explain income that is not a simple salary
If you are self-employed or rely on commission, bonuses, rental income, benefits, support payments or another non-wage source, ask the lender exactly what evidence it uses to establish the amount and continuity of that income.
Self-employment
Have business and personal tax records, relevant schedules and statements available if requested. Be prepared to explain changes in revenue, ownership, business expenses or transfers between business and personal accounts. The lender, not a generic checklist, determines which records establish qualifying income.
Rank #3

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
Rental, commission and benefit income
Keep leases, payment histories, award or benefit letters and other records that show both the source and expected continuation of the income when applicable. Do not assume that every dollar received will count in the same way for underwriting.
Employment changes
Tell the lender about a new employer, a gap, a change from salary to commission or a planned reduction in hours. Concealing a change can create a larger problem when verification returns a different picture.
7. Make every down-payment dollar traceable
Lenders generally verify not only how much you have but where it came from. Keep account statements, transfer confirmations and sale records that connect the money shown in your application to its source.
Large deposits
Mark unusual deposits before submitting statements. Write down the date, amount, source and reason, then save the evidence that supports it. A transfer from another account may require statements for both accounts; proceeds from an asset sale may require the sale document and proof of receipt.
Gift funds
If someone will give you money, ask whether gifts are permitted under the loan program you are considering and which records are required. The lender may need a signed gift letter, evidence of the donor’s ability to provide the funds, proof of transfer and confirmation that no repayment is expected. Do not move gifted money before you understand the lender’s process.
Do not mix undocumented cash into the plan
Cash that cannot be sourced may not be usable for the transaction. Deposit and document funds through a traceable account rather than relying on a last-minute explanation.
8. Choose a loan program that fits your situation
Ask lenders which programs you may qualify for and what each would require. CFPB shopping guidance identifies conventional, FHA, VA, USDA and state housing-finance-agency options as examples of programs serving different circumstances. Eligibility, mortgage insurance, fees, documentation and terms are program-specific; the names alone do not tell you which option is cheapest or suitable.
Free tools Windows power users keep installed
One-click scans. No signup required.
Discuss how the program treats your income type, available funds, property, credit history and plans for the home. A program with a lower upfront requirement can still have higher ongoing costs or conditions. Have the lender explain trade-offs in writing rather than relying on a verbal summary.
Rank #4

- Stable & sturdy construction: Expanding file folder is made from durable wipe-clean polypropylene. Acid-free and high-quality for using trustingly. Waterproof & sturdy enough to keep the file organizer from collapsing. The accordion folder's cord closure and adjustable flap provide additional security. Built-in file separation layers are flexible to ensure the files don't wrinkle.
- Handy organization & Easy lookup: Expandable file folder has 24 pockets designed for keeping our paperwork organized. Accurately classified storage in the specific color slot and labeled with tabs, so it is easier to find the papers what is needed.
- Plentiful storage: Product Size: 13'' L x 9.25'' H. Each pocket fits well for all A4/Letter size paper. Excellent scalability. The accordion file folder can be stretched pretty far, more than 24 inches. 24 pockets allow you to store more than 4000 sheets of paper documents.
- Portable & stylish: Classic lightweight folder organizer can be compressed to a minimum thickness of about 2 inches, so it can be held up great for traveling to and from all different locations for work. Fits perfectly when completely closed in the file cabinet. The dividing sections of the rainbow file folders come in six bright colors, stylish and beautiful. Versatile document organizer for home, office, school, and travel scenarios, compact and light.
- Expandable desktop folder: Folders can be expanded to different widths as the number of files you put into increases. Stand on its own on the desk and not easy to tip over when pulled out to maximum capacity and filled. Each pocket is completely sealed at the bottom to keep small objects do not move.
9. Get Loan Estimates from multiple lenders
Comparing lenders before choosing one can reveal differences in rates, fees, service and program fit. Ask several lenders for a Loan Estimate and give each the same basic assumptions so the numbers are comparable.
The six pieces of information that start the Loan Estimate process
For the CFPB’s consumer explanation, a lender has enough information to provide a Loan Estimate for a covered mortgage when you provide:
- Your name
- Your income
- Your Social Security number, so the lender can obtain a credit report
- The property address
- An estimate of the property’s value
- The requested loan amount
You do not have to submit a full document packet merely to receive a Loan Estimate. A lender may request verification after you decide to proceed, and fuller information can improve the accuracy of an estimate. The six-item rule governs the Loan Estimate process; it is not a complete underwriting checklist.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Compare the same assumptions
When requesting estimates, specify the same purchase price, down payment, loan term, occupancy, property type and desired lock assumptions whenever possible. Otherwise, a lower payment may simply reflect a smaller loan, a different term or costs shifted into another part of the estimate.
Read the costs that matter
| Comparison | Question to ask |
|---|---|
| Program and eligibility | What program is this, and do its requirements fit my income, assets, property and intended occupancy? |
| Rate structure | Is the rate fixed or adjustable, and what assumptions or points produce it? |
| Monthly payment | What is the projected payment including principal, interest, taxes, insurance and applicable mortgage insurance or association charges? |
| Upfront charges | Which origination, underwriting, appraisal, credit, recording and other fees are included, and which are paid by someone else? |
| Cash to close | How much money must I bring, and how do credits, deposits and prepaid items affect that figure? |
| Long-term fit | How does this offer fit my budget and the length of time I expect to keep the home? |
Use the Loan Estimate to compare costs and terms, then ask each lender about material differences. A slightly lower rate may not be better if it requires substantial points or creates a payment your budget cannot sustain.
10. Keep your financial picture stable during underwriting
After applying, continue behaving as though the lender may need to verify every material change. Avoid large credit-funded purchases, co-signing for someone else, closing an established account without advice, moving money between accounts without records or changing jobs without telling the lender.
If a change is unavoidable, contact the loan officer promptly and ask what documentation is needed. Hiding a new debt or unexplained transfer can delay approval or change the terms. Keep pay records, statements and transfer confirmations in the same organized system you used for the initial packet.
11. A practical preparation sequence
- Review credit. Obtain all reports, identify errors and submit disputes early.
- Map the budget. List income, recurring debts, savings, down-payment funds, taxes, insurance, closing costs, repairs and other ownership expenses.
- Identify documentation risks. Note self-employment, variable pay, rental or benefit income, job changes, large deposits and gift funds.
- Collect records. Save pay stubs, W-2s, applicable tax returns, statements, identification and source-of-funds evidence in complete form.
- Ask targeted questions. Request the lender’s current checklist for your loan program and income profile.
- Request estimates. Give multiple lenders the six required pieces of information and consistent assumptions.
- Compare offers. Review program, rate structure, payment, total costs, fees, cash to close and budget fit.
- Preserve stability. Avoid unnecessary new credit and keep all account activity explainable through closing.
12. Common preparation mistakes and fixes
| Mistake | Why it causes trouble | Better approach |
|---|---|---|
| Waiting to check credit until application day | Errors may remain unresolved when the lender reviews the file. | Review reports early and retain dispute records. |
| Budgeting only for principal and interest | Taxes, insurance, closing, repairs and other costs can make the payment unaffordable. | Build a full ownership budget before choosing a price range. |
| Submitting partial statements | Missing pages can prompt re-requests and questions about omitted activity. | Send complete statements, including blank pages. |
| Depositing gift or transferred money without a paper trail | The lender may be unable to verify the source or terms. | Ask about gift rules first and preserve transfer evidence. |
| Applying for unrelated credit | New inquiries, accounts and payments can change the application. | Delay nonessential credit until the mortgage process is complete. |
| Comparing payment quotes with different assumptions | The apparent winner may simply use a different loan size, term or cost structure. | Request Loan Estimates using consistent information. |
| Treating a checklist as universal | Requirements vary by lender, program and borrower. | Confirm the current list with the loan officer handling your file. |
13. Questions to ask your loan officer
- Which documents do you need for my employment and income type, and how current must they be?
- How will you document a large deposit, transfer, gift or asset sale?
- Are gifts allowed for the program I am considering, and what must the donor provide?
- Which conventional, FHA, VA, USDA or state housing-finance-agency options fit my circumstances?
- What expenses should I include beyond the payment shown in an estimate?
- What changes in employment, debt, assets or credit activity should I report immediately?
- What assumptions are included in this Loan Estimate, and which costs could change?
- How much cash must remain after closing, if the program or your underwriting policy requires reserves?
14. What a well-prepared application looks like
A ready file tells one consistent story: the credit report is reviewed, known errors are being addressed, income and employment are supported by current records, assets match the account statements, down-payment money has a documented source, debts are fully listed and the proposed payment fits a budget that includes ownership costs.
That preparation cannot guarantee approval, a particular rate or a specific closing date. It does reduce avoidable surprises and gives lenders the information needed to evaluate the application under the rules of the selected program. Before you submit, verify your checklist with the loan officer and keep your records accurate through closing.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




