
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11A financial safety plan is a shared, current record of your money, obligations, account access, bill process, legal authority and emergency contacts. Build it before the wedding if possible, then update it after marriage and after every major change. The goal is continuity: either spouse should be able to keep essential bills, insurance and records under control if the other is unavailable, while each person’s privacy and safety remain protected.
What a financial safety plan covers
A marriage does not automatically create one universal system for bank accounts, property, debts or decision-making. A workable plan combines seven parts:
As an Amazon Associate I earn from qualifying purchases.
- A complete, honest inventory of income, assets, debts, recurring bills, insurance and financial obligations.
- An agreed method for holding money and paying shared expenses.
- A secure emergency reference file that both spouses can locate.
- Instructions for illness, incapacity and death, including appropriate legal documents.
- Beneficiary and ownership reviews after marriage and other major life events.
- State-specific legal and tax advice when the consequences are significant.
- A safety-first response if one partner may be experiencing financial abuse.
The Consumer Financial Protection Bureau (CFPB) says it is common for couples to share their financial lives without sharing responsibility for managing household finances. Your plan should therefore make responsibilities explicit rather than assuming that one spouse will always know what to do.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Step 1: Have a complete money conversation
Before combining anything, each partner should prepare a private inventory and then review it together. The purpose is informed consent and continuity, not permission to monitor or control the other person’s spending.
#1 Best Overall
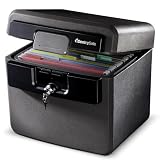
- FIRE AND FLOOD PROTECTION FOR ESSENTIAL PAPERS: UL Classified to withstand high temperatures for up to thirty minutes and ETL Verified to protect contents during water exposure, helping safeguard critical paperwork during common home emergencies
- DESIGNED FOR IMPORTANT DOCUMENT STORAGE: Spacious interior fits hanging file folders and is ideal for organizing passports, birth certificates, insurance records, and legal paperwork
- KEY LOCK SECURITY YOU CONTROL: Durable key lock helps prevent unauthorized access and keeps the lid securely closed during fire events. Two keys are included for backup access
- HOME FRIENDLY SIZE WITH PORTABLE DESIGN: Compact footprint fits easily in closets, offices, or under desks while remaining portable enough to relocate when needed
- BUILT FOR EVERYDAY PEACE OF MIND: Black exterior offers a clean, neutral look that blends into home or office spaces while providing dependable document protection year round
Inventory income and resources
- List salary, hourly pay, bonuses, commissions, self-employment income, pensions, benefits and other recurring or irregular income.
- Record where each payment is deposited and whether the amount or timing changes during the year.
- List checking and savings accounts, investments, retirement plans, pensions, real estate, vehicles, business interests and valuable personal property.
- Note account ownership, authorized users and current beneficiary designations.
Inventory debts and obligations
- Include mortgages or rent, auto loans, student loans, credit cards, personal loans, medical balances and tax obligations.
- Identify co-signed or guaranteed debt and any obligation to support children, parents or other relatives.
- Record minimum payments, interest rates, due dates, automatic-payment accounts and whether a balance is in collection or subject to a legal dispute.
List the household’s recurring costs
The CFPB checklist specifically calls out utilities, cell phones, property taxes, insurance, loan payments and credit cards. Add subscriptions, childcare, transportation, professional dues and any annual or quarterly bill that could be missed during an emergency. Mark which expenses are essential, which are discretionary and which are paid from a particular account.
Discuss goals and boundaries
Talk about housing, children, caregiving, career breaks, education, debt repayment, saving and support for family members. Ask how much information each person would need to manage the household for a month if the other could not respond. Agree that disclosure does not confer a right to demand passwords, restrict lawful spending or take money without permission.
Put the agreed facts in writing. A simple spreadsheet or document can be enough if it is protected and kept current. Each partner should be able to explain the overall system without needing the other person’s memory.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Step 2: Choose an account arrangement deliberately
There is no single correct structure. A 2024 Connecticut Department of Banking guide describes three common approaches, and notes that the arrangement can change with careers, parenthood, caregiving or other milestones.
| Arrangement | Shared-bill convenience | Autonomy and privacy | Withdrawal authority | Handling different incomes | Exposure and continuity considerations |
|---|---|---|---|---|---|
| One joint account | High: income and shared expenses can flow through one account. | Lower: routine transactions are visible to both owners. | Each owner usually can withdraw funds while both owners are alive; confirm the institution’s terms. | Requires an agreed contribution method or a decision to pool all income. | Both owners have broad access. Understand how overdrafts, debts, disputes and an owner’s unavailability are handled. |
| Separate accounts with assigned bills | Moderate: each spouse pays designated expenses. | Higher, subject to the information needed to manage shared obligations. | Each person controls their own account; access to the other account is not automatic. | Contributions can be equal, proportional to income or another agreed formula. | Requires accurate coordination and a backup way to pay bills if one spouse is unavailable. Separate accounts do not by themselves determine legal ownership of property or debts. |
| Mixed system: household account plus individual accounts | High for listed household costs. | Balances shared visibility with personal discretionary space. | Both owners access the household account; individual accounts remain separately controlled. | Each spouse contributes an agreed amount or percentage to the household account. | Define what counts as a household expense, how shortfalls are covered and how the system changes during unpaid leave or caregiving. |
Set contribution and access rules
Write down which account pays each bill, who checks balances, who receives alerts and what happens if one income stops. If earnings differ, choose equal dollar contributions, contributions proportional to income or another method you both regard as fair. Decide whether bonuses, tax refunds and irregular freelance income are pooled or retained by the earner.
Review the arrangement when someone changes jobs, takes unpaid leave, becomes a caregiver, starts a business, receives an inheritance or takes on significant debt. A system that worked while both partners earned regular pay may fail when one person’s income becomes unpredictable.
Understand what adding a joint owner means
According to CFPB joint-account guidance last reviewed April 15, 2024, joint bank accounts generally allow each account holder to withdraw money while both owners are alive. Adding a person is therefore a grant of meaningful authority, not merely a convenience. Read the bank agreement before adding an owner, and ask how the account handles overdrafts, creditor claims, death and disputes.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #2

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
If someone is helping with bill payment, do not assume that person needs to become an owner. CFPB notes that a financial professional generally does not need to be added as a joint owner. Ask the institution about narrower options, such as authorized access or other safeguards, and obtain legal advice when the amount or risk is substantial.
Step 3: Build a bill-paying process that survives interruptions
A safety plan fails if it lists accounts but does not explain what must be paid and when. Create a bill calendar with the following fields:
- Creditor or service provider name and the account’s last four digits or another safe identifier.
- Amount or formula used to calculate the bill, due date and grace period if known.
- Payment method, the account used and whether autopay is active.
- Contact method, insurance policy number or employer contact where relevant.
- The person who normally monitors the bill and the backup person.
Use calendar reminders for annual renewals, property taxes, insurance premiums and registration fees. Decide how to handle a disputed charge, a missed payment or a sudden drop in the household account. Keep a small written procedure for stopping or changing autopay; do not rely on one spouse’s email inbox or phone.
Both partners should know how to reach the bank, insurer, employer benefits office, mortgage servicer and utility providers. Share enough information to act, but store full passwords and security answers only in a secure system that you have agreed to use.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Repair Windows errors before they cause bigger problems3Fix the driver behind crashes, sound loss and screen glitchesStep 4: Create a secure emergency reference file
The CFPB recommends that couples maintain a secure list of accounts and keep it current. The list can be stored in password-protected digital storage or as a printed copy in a locked, fire-resistant box. A physical box is optional; no container should be treated as a guarantee against every fire, flood or theft scenario.
Include these categories
- Bank, credit-union, brokerage, retirement and payment-app institutions, with safe account identifiers.
- Mortgage, rent, auto-loan, student-loan, credit-card and other debt contacts.
- Employer payroll and benefits contacts, including life, health and disability insurance.
- Insurance policies, renewal dates and claims contacts.
- Bill due dates, payment accounts and the location of the bill calendar.
- Deeds, titles, tax returns, loan documents, wills, trusts, powers of attorney and any prenup or marital agreement.
- Names and contact details for the attorney, tax professional, financial planner or nonprofit counselor who is authorized to help.
- Instructions for accessing the secure password manager or other credential-recovery method.
Protect the file
Do not put passwords, full account numbers or security answers in an unsecured email, public cloud folder or document that can be forwarded casually. Limit access to people who genuinely need it. Test the retrieval process twice a year: both spouses should be able to find the file and understand the account map without guessing.
Step 5: Plan for illness, incapacity and death
Marriage alone may not give a spouse authority to access every account or make every financial decision if the other spouse becomes incapacitated. Ask a local attorney what documents and witnessing or notarization rules apply in your state.
Rank #3

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
Financial power of attorney
CFPB explains that a financial power of attorney (POA) can authorize an agent to make financial decisions. A durable POA generally remains effective after the principal becomes incapacitated, but the exact document and state rules matter. The authority can be broad, so choose an agent carefully and consider safeguards such as requiring the agent to provide reports to another trusted person.
Store the signed original and any certified copies where the emergency reference file says they are located. Tell the relevant institution how to verify the document before an emergency. A POA designation can generally be changed or revoked while the principal has the required capacity, subject to applicable law. Do not sign a form you do not understand or name an agent because someone is pressuring you.
Beneficiaries and ownership
Review beneficiaries on retirement plans, life insurance, payable-on-death accounts and transfer-on-death registrations after marriage and after divorce, birth, adoption or death in the family. Check whether ownership matches your wishes; a beneficiary form and a will may address different assets. Ask an attorney to coordinate the documents rather than assuming one automatically overrides another.
Medical and practical continuity
Alongside financial documents, record where health-insurance cards, identification, medication information and employer leave forms are kept. Decide who should contact employers, insurers and lenders if one spouse is hospitalized. Keep this operational information separate from passwords when that improves safety.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Step 6: Address legal and tax questions before the wedding
State law and individual facts determine how property, debts, support and agreements are treated. The Office on Women’s Health notes that marital-finance rules vary by state. Do not assume marriage automatically transfers every debt to a spouse, or that keeping an account separate guarantees that an asset remains separate.
Recommended Free Tools
When a prenup deserves discussion
A prenuptial agreement may be worth exploring when either partner has substantial prior assets or debt, owns a business, has children from an earlier relationship, expects an inheritance, or has different expectations about property and support. The Connecticut Department of Banking describes a prenup as a contract that lists assets and liabilities and addresses division in the event of divorce. It recommends an experienced attorney; that state guidance is not a nationwide guarantee of enforceability.
Begin early enough for complete disclosure and meaningful review. Each partner should have an opportunity to obtain independent legal advice where appropriate. Never treat a last-minute signature, incomplete inventory or pressure to waive review as a sound process.
Rank #4

- 5200°F Fireproof & Water-resistant Safe: The upgraded important document organizer is made of thickened silicone-coated fireproof cotton material and aluminum foil (double safe protection). Its 8 fireproof layers can withstand temperatures up to approximately 5200°F. The aluminum foil lining does not easily melt at high temperatures. The main material has passed the 5VA flame retardant test. The bag is fireproof & water-resistant, which can protect your important files in a fire&wet weather
- Soft Box: Large-capacity(15"x11"x4.1"),Compared with other bags,our fireproof file organizer adopts a multi-layer design that can meet all your storage needs. These include 8 passport mesh bags,16 card slots, 4 U Disk pockets, 7 folder layers and one main pocket with a large space. It can store your important documents,files,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way.Great way to organize your files easy for you to find whatever files you looking for quickly
- Combination Lock Protection: Compared with other bags,our 5200°F fireproof document organizer can lock files and items inside the bag for safety. High-quality password lock provides maximum security for your valuables such as contracts, cards, certificates, conference materials, passports, etc. More wider strap handle design on the back allows you to insert a suitcase handle. Fireproof bag for files is sealed with professional waterproof zippers that can withstand high speed spray of fire hose
- Innovative Humanized Design: Design with a strong handle for carrying everything you needed easily.Not only can you put it in your home, office, car,storage cabinet, you can also take it to camping, travel and various outdoor activities. Of course, giving it as a Christmas gift to your family, customers or employees is also a good choice.The newly designed fireproof bag is lighter,easier to carry than a fireproof safe, and easy to fold
- Trusted after sales service: The Upgraded Non-dusty material can prevent dust and pet hair from sticking to the outside of our bag,always keep it neat and tidy. In the event of an emergency, our fireproof file bags are lighter, easier to carry than fireproof safes and quick to grab and go. We only wish to present the best to customers,to protect your valuables. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately
Property, mortgages and unmarried partners
If you are buying a home before the wedding, CFPB says unmarried applicants may apply jointly for a mortgage. Discuss each person’s financial status, title and ownership percentages, down-payment credits, repairs, taxes, sale rights and what happens if the relationship ends. A cohabitation agreement may address issues a mortgage or deed does not; have local counsel draft or review it.
For loans secured by property, a lender may consider marital status as it affects access to collateral. Federal mortgage-lending rules prohibit discrimination based on sex or marital status, but the underwriting and ownership consequences of a particular transaction still require professional advice.
Taxes
Filing status, ownership changes, gifts, business income and retirement transactions can create tax consequences. The information here does not establish a filing recommendation or a particular tax result. Ask a qualified tax professional about your facts before transferring property, changing withholding or choosing a filing status.
Step 7: Update the plan after marriage and major changes
Use a short review after the ceremony and a fuller review at least annually. Also review immediately after any event that changes income, residence, family structure or legal authority.
- Update names and addresses with employers, financial institutions, insurers and government agencies where appropriate. The Connecticut guide identifies account and name updates as part of starting married financial life.
- Confirm account ownership, authorized users, beneficiaries and emergency contacts.
- Replace the bill calendar with current amounts, due dates and autopay instructions.
- Reconcile the emergency file with the latest wills, POAs, insurance policies, tax records and property documents.
- Revisit contribution percentages and discretionary spending after a job change, parental leave, caregiving period or return to work.
- Check credit reports separately and together when appropriate, especially after a move, name change, identity theft concern or new joint application.
- Record decisions and the date of the next review.
Recognize financial abuse and put safety first
Financial abuse is not simply a disagreement about budgeting. The Office on Women’s Health lists warning signs including preventing a partner from working, hiding assets, withholding account access, limiting spending, making financial decisions without consultation, misusing identity information and forcing someone to open or use credit.
Safer steps when abuse may be present
- Protect personal identification, account credentials, phone access and email recovery information. Use a device and account the abusive partner cannot monitor when possible.
- Do not co-sign a loan or open a credit line under pressure.
- Review credit reports for accounts opened in your name. Consider a credit freeze or fraud alert if appropriate to your situation.
- Saving money separately may help only when it can be done safely. New-account mail, transaction alerts or browser history can expose the plan.
- If preparing to leave, copies of identification, children’s documents, health-insurance cards and bank statements may be useful, but collect only what you can obtain safely.
Do not confront an abusive partner about finances if that could increase danger. Contact a confidential local domestic-violence service, legal-aid provider or trusted advocate for an individualized safety plan. Safety takes priority over completing a document checklist.
A practical review checklist
At the end of a planning session, both spouses should be able to answer these questions without guessing:
- Where are income, savings, investments, retirement funds and insurance held?
- Which debts exist, what are their due dates and which payments are automatic?
- Which account pays each shared bill, and what happens if one income stops?
- Who can withdraw from each account, and what authority has been granted to any third party?
- Where is the secure emergency file, and can each spouse retrieve it?
- Where are the will, POA, property, tax and marital-agreement documents?
- Who should be contacted if one spouse is ill, incapacitated, unemployed or deceased?
- When were beneficiaries, ownership records and contact details last reviewed?
- Is anyone being denied money, work, information or safe access as a form of control?
A good plan is specific enough for a spouse or authorized helper to keep essential obligations running, flexible enough to change with the household, and cautious enough to respect state law and personal safety. The Connecticut Department of Banking summarizes the choice of account structure this way: “There’s not one right answer. What’s important is that you’re both comfortable with your arrangement.”
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




