
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →A workable plan for supporting parents and children starts by putting every obligation on the same page: your household income, essential bills, debt, insurance, savings, support for children, parent-related costs and likely care expenses. Then set written limits, protect your ability to earn and save for retirement, arrange legal authority for a parent’s finances, and verify tax and benefit rules for the relevant year and state.
This is general U.S. planning information, not individualized tax, investment or legal advice. Family circumstances, state law, benefit eligibility and tax rules change, so use the linked government guidance and qualified professionals for decisions that depend on your facts.

As an Amazon Associate I earn from qualifying purchases.
Why a two-generation plan needs a different approach
When you are paying for a child’s needs while helping an aging parent, the danger is not only a large bill. It is the accumulation of untracked transfers, reduced work hours, missed retirement contributions, emergency borrowing and decisions made without knowing who has authority to act. A plan has to protect three households at once: the parent’s safety, the child’s needs and your own long-term stability.
CFP Board Consumer Advocate Eleanor Blayney described the dilemma this way: “Many Americans find themselves having to keep multiple generations afloat, often at the expense of their own long-term security,” and asked, “how can I say ‘yes’ to my own financial needs and goals, when it is impossible to say ‘no’ to needy family members?” The point is not to rank one generation above another. It is to make the trade-offs visible before a crisis makes them for you. CFP Board’s consumer guidance recommends written expectations, a realistic look at your earning capacity and explicit planning for elder-care responsibilities.
#1 Best Overall

- 【Comprehensive End of Life Organizer Binder】This end of life organizer binder covers 20 sections including personal info, medical, finances, will, beneficiaries, and final wishes, ensuring all essential details are safely recorded and accessible, helping loved ones easily find everything they need
- 【Durable 3-Ring Binder with PVC Pockets】Made with a sturdy 3-ring design and 10 acid-free binder pockets, this when i die organizer binder keeps records protected from water, wear, and damage, preserving your legacy for years, helping you organize your final arrangements in a light-hearted way
- 【Fits Standard 8.5"x11" Pages & Large Print】The end of life document folder is designed to fit standard letter-size paper, making it easy to insert, update, or print documents. The 120gsm non-bleed paper ensures a smooth writing experience. A practical way to keep all essential information neatly organized
- 【Tabbed Sections for Easy Navigation】Featuring 8 durable dividers, the before death organizer binder allows quick access to medical data, login details, finances, dependents, and more—helping loved ones easily find what they need, not only reduces the burden on loved ones but also brings peace of mind
- 【Peace of Mind & Thoughtful Gift】This death planner organizer binder reduces stress for families, helps initiate important but difficult conversations about end of life wishes with family, ensures wishes are honored. A practical and caring gift for seniors, parents, and loved ones
Use the process below as a household operating system. It can be adapted whether support is a regular monthly payment, shared housing, transportation, medical bills, unpaid care or occasional emergency help.
1. Put the whole household on one page
Gather a complete monthly baseline
Start with a recent month, then add annual or irregular costs so the plan does not mistake a low-expense month for the normal one. Use take-home income rather than gross salary for the first cash-flow view. Separate support for children and parents from general spending; otherwise the transfers disappear and you cannot tell which obligation is growing.
| Section | Include | Question to answer |
|---|---|---|
| Income | Pay, self-employment income, benefits, support received and reliable other income | Which income is stable, and which depends on hours, health or a contract? |
| Your household essentials | Housing, utilities, food, transportation, insurance premiums, taxes and necessary medical costs | What must be paid before discretionary support? |
| Debt | Minimum payments, interest rates, balances and co-signed or parent-related debt | Which payment creates the greatest risk if income falls? |
| Children | Child care, school costs, activities, clothing, health expenses, allowance and regular transfers | What is recurring, and what is a one-time request? |
| Parents | Housing help, food, prescriptions, insurance gaps, transportation, home maintenance and care payments | Which costs are yours, and which could be shared with siblings or other relatives? |
| Saving and protection | Emergency savings, retirement contributions, education saving, life or disability insurance and sinking funds | What future protection is being reduced to fund today’s support? |
| Irregular and expected care | Deductibles, travel, home repairs, periods of extra care, legal fees and possible changes in living arrangements | What event would require cash within 30, 90 or 365 days? |
For each parent-related payment, record the date, amount, purpose and whether it is a gift, a loan, a bill paid directly or reimbursement. Keep a separate line for unpaid care time. Hours spent arranging appointments, managing medications or transporting a parent can affect your work even when no check is written.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Make the parent’s information usable
With the parent’s consent, create an inventory that another authorized person could understand. The Consumer Financial Protection Bureau (CFPB) recommends keeping financial information organized and accessible. Gather:
- Bank, brokerage, retirement and savings account names and contact details;
- mortgages, credit cards, personal loans and recurring payment instructions;
- insurance policies, premiums, beneficiaries and claims contacts;
- retirement-benefit and Social Security information;
- property records, tax returns and other documents needed to establish ownership or obligations;
- names and contact details for financial, legal and medical professionals; and
- a secure explanation of where original documents and account credentials are stored.
Do not put passwords in an ordinary spreadsheet or email. Use a secure storage method and tell the people who may need access how to find it. Update the inventory after a move, account change, diagnosis, death, divorce or change in the person designated to help.
2. Turn support into explicit family agreements
Define help for children
For a child who is a minor, identify the costs you are responsible for and the costs that are discretionary. For an adult child, write down the amount, purpose and expected duration of help. A contribution toward tuition, rent, health insurance or a one-time emergency should not silently become an open-ended monthly obligation.
A short written agreement can answer:
- How much will be provided and on what date?
- Is the money a gift, a loan or direct payment to a provider?
- What is the child expected to contribute through work, applications for aid, budgeting or household tasks?
- What event causes a review, such as graduation, a new job, a move or a change in your income?
- Who will decide whether an exception is affordable?
Writing this down is not a lack of generosity. It prevents different family members from relying on different assumptions.
Free tools Windows power users keep installed
One-click scans. No signup required.
Define help for parents and coordinate with relatives
Discuss the parent’s priorities while the parent can participate. List which expenses you will pay, which expenses the parent will pay, and which costs are being considered but not yet approved. Ask siblings or other relatives for specific commitments rather than a general promise to “help later.” Contributions can be money, transportation, appointment coordination, home maintenance or scheduled care hours; record each in the plan.
Rank #2
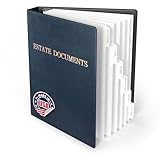
- Complete estate planning binder kit: Includes estate document binder, 6 pre-labeled index tabs, 6 heavy-duty sheet protectors, interior document folder, and USB holder for digital backups — everything needed to organize important documents in one place.
- re-labeled tabs for instant organization: This estate planning organizer includes six clearly labeled sections — Trust Agreement, Funding, Last Will & Testament, Power of Attorney, Health Care Directives, and Miscellaneous — so your estate binder is set up in minutes.
- Premium construction, made in the USA: Faux leather cover and durable 1.5" D-ring binder securely hold your documents while maintaining a clean, professional appearance for home or office use.
- Designed for the moments that matter most: Clearly labeled sections make it easy for family members or attorneys to quickly locate critical documents — even in high-stress situations — without confusion or searching.
- A thoughtful way to protect what matters most: Whether for yourself or as a meaningful gift for parents, spouses, or clients, this estate organizer ensures important documents are organized, accessible, and never left behind.
CFP Board guidance recommends putting elder-care responsibilities in writing, including expectations for siblings and other relatives. Include what happens if a contributor loses a job, moves away or becomes unable to provide care. Agree on who will communicate with providers and how receipts and account information will be shared.
Set review triggers before conflict starts
Choose a regular review date, such as quarterly, and add event-based reviews. Useful triggers include a hospitalization, a diagnosis that changes care needs, a child starting or leaving school, a job change, a major rent increase, a new debt, a change in benefits or a parent’s move to a different living arrangement. A trigger does not automatically cut support; it starts a fresh decision using current facts.
3. Protect your earning capacity, retirement and benefits
Your future income is an asset the family may need for decades. CFP Board cautions that leaving work to provide care can reduce retirement and Social Security benefits and can make it difficult to return at a comparable level. That is a risk to weigh with your family, not a rule that every caregiver must refuse unpaid care.
Show your current retirement contributions, employer match, health coverage, disability coverage and paid-leave benefits beside the support budget. Then model what changes if care needs increase or your hours fall. Ask an employer about flexible scheduling, leave policies and benefit effects before resigning or reducing hours.
| Possible approach | Potential effect on your plan | Questions to resolve |
|---|---|---|
| Continue working and arrange paid or shared care | Higher current care cost, but preserves wages, benefits and contribution capacity | Can the cost be shared, and is the arrangement reliable enough for work hours? |
| Temporarily reduce hours | Lower income and possibly lower benefits; may provide more predictable care time | How long is “temporary,” and what happens to retirement contributions and insurance? |
| Take leave | May protect the job under applicable rules, but pay and benefit treatment varies | What does the employer’s written policy provide, and how will bills be paid during leave? |
| Leave employment | Removes wages and may interrupt retirement and Social Security accrual; returning at a comparable level may be difficult | What is the return-to-work plan, and what reserve covers the gap? |
Before diverting retirement money or stopping contributions, calculate the long-term cost with a fiduciary financial professional if the decision is complex. Keep an emergency reserve appropriate to your income volatility and family responsibilities. Do not use “I will make it up later” as the plan unless you have modeled when and how.
4. Build cash-flow layers instead of one undifferentiated budget
Organize money in layers so an urgent request does not automatically consume every goal:
- Essential operating cash: Keep housing, food, utilities, transportation, insurance, minimum debt payments and necessary medical costs current.
- Near-term family reserve: Set aside money for known school costs, deductibles, travel to help a parent, equipment, home repairs or a likely care transition. Give each reserve a purpose and a target date.
- Long-term protection: Continue retirement saving and maintain insurance protection as far as your cash flow allows. These are not optional luxuries; they reduce the chance that your children or parents will need to support you later.
- Flexible support: Use the remaining amount for discretionary help, gifts and improvements that can be paused without endangering essentials.
When the plan is short, identify the exact layer being reduced. A temporary cut in a flexible contribution is different from missing an insurance premium or taking on high-cost debt. If essential costs already exceed dependable income, seek professional debt, tax or benefits advice rather than promising an amount the household cannot sustain.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errors5. Prepare for parent care and financial decision-making
Have the conversation while the parent can participate
Ask the parent how bills are paid, which accounts exist, who should be contacted in an emergency and what kind of help would feel acceptable. Explain that organizing information is a safety measure, not an attempt to take control. Revisit preferences as health, housing or family relationships change.
Rank #3

- Cash Envelopes System:1pcs PU leather money saving binder,8pcs A6 6-holes binder pockets,12pcs expense budget sheets,3 sheets of category sticker labels,Budget binder with cash envelopes perfect for you to save money.
- PU Leather Binder:Cash binder has attractive double-colors cover,Premium PU leather A6 binder has many hidden compartments and pen hoops,which is convenient for storing pen, passports, ID cards, bank cards.
- Binder Pockets:8PCS A6 zipper cash envelope made from superior material. It is resists tearing and acid-free which can protect your items from water and dust.As cash envelopes is convenient for storing money, cards, stamps, tickets, pens.
- Category Stickers & Budget Sheet: Money binder with category stickers and budget sheets can help you organize your expenses and track your deposits and withdrawals and achieve budget goals.
- Easy to Carry:A6 Binder Budget Envelopes System fits in your handbag, backpack,suitcase or desk;A6 ring binder suitable for all standard A6 size inner pages.
Understand the difference between financial and health-care authority
The CFPB describes a durable financial power of attorney as a document that gives someone legal authority to make financial decisions if the parent cannot. It does not replace authority for health-care decisions. Investment transactions for another person require legal authority; being a relative or having access to an account is not the same thing.
Ask an attorney familiar with the parent’s state law whether a durable financial power of attorney is appropriate, when it becomes effective, how it can be revoked and where it should be stored. State requirements, accepted forms and institutional procedures differ. A trusted contact can help a financial institution reach someone if concerns arise, but a trusted contact is not automatically authorized to move money.
Use safeguards when someone acts for the parent
Keep the parent’s money separate from your own, preserve receipts, document decisions and follow the authority granted in the legal instrument. Do not use a parent’s funds for your household unless the transaction is authorized and recorded. The CFPB’s Managing someone else’s money guides, last modified June 25, 2026, provide role-specific information for agents under a power of attorney, court-appointed guardians, trustees and government fiduciaries.
The CFPB’s planning-for-diminished-capacity guidance, last modified December 8, 2025, also discusses advance designation, trusted contacts and organizing records. Use the parent’s own lawyer for document preparation and state-specific questions.
6. Handle taxes with current, fact-specific rules
Paying expenses does not automatically make a parent your dependent
The IRS caregiver FAQ says dependent status requires meeting all applicable tests. Two central questions are whether you paid more than half of the parent’s support and whether the parent’s gross income is below the limit for the applicable tax year. The IRS page currently displays a $5,200 gross-income threshold, but that figure is tax-year-sensitive and must not be treated as a permanent amount.
Start by listing the parent’s support from every source: Social Security, pensions, wages, investment income, benefits, savings and contributions from other people. Then document what you paid and what the parent paid. The IRS applies additional tests and exceptions, so check the current Publication 501 and ask a tax professional whether the parent qualifies for your filing year. Do not claim a dependent solely because you pay rent, premiums or medical bills.
Keep records for any medical or care-related tax question
Save invoices, statements, proof of payment and an explanation of whose expense each item was. Whether a medical expense, dependent-related cost or other payment is deductible depends on the tax rule, the person receiving the care, your filing status and the year. The IRS caregiver FAQ and current publications should control over an old checklist or a family tradition.
Use a year-end tax checklist
- Confirm the tax year and the current income threshold before applying the dependent tests.
- Reconcile support paid by you with support paid by the parent and other relatives.
- Keep records showing dates, amounts, purpose and recipient for significant payments.
- Ask whether any written cost-sharing or loan arrangement has tax consequences.
- Provide the records to a qualified tax professional when the facts involve multiple households, medical costs, a parent’s sale of property or a change in filing status.
For the federal caregiver FAQ and links to current rules, see the IRS caregiver guidance.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.7. Check public and community help without assuming eligibility
Public programs and community services may reduce the amount your family must pay, but eligibility is local and changes over time. CFP Board recommends checking with the local Medicaid office and other community resources. Contact the relevant state or local agency directly for current income, asset, functional-need, residency and application rules. Ask what documentation is required and whether there is a waiting list.
Do not build the budget around an unverified benefit, an old program name or an assumed approval date. Record the agency, representative, date, application number and next action. Recheck eligibility after a move, income change, marriage, inheritance, diagnosis or change in care setting.
8. Compare care arrangements using the same decision criteria
No single arrangement fits every parent or every budget. Compare options on the same axes, then revisit the comparison as needs change.
Recommended Free Tools
| Arrangement to evaluate | Monthly cost and effect on savings | Parent’s needs and preferences | Who coordinates care | Flexibility and assistance eligibility |
|---|---|---|---|---|
| Family-provided hours or shared housing | May reduce cash spending but can reduce work hours, privacy and retirement saving | Does the parent feel safe and respected in the arrangement? | Which person schedules, transports, supervises and documents care? | What happens when a family caregiver is ill, working or away? |
| Paid in-home services | Price depends on hours, tasks, location and provider terms; include taxes, transportation or minimum-hour rules when applicable | Can the service meet medical, mobility and companionship needs? | Who hires, supervises and covers an absence? | Could a public or community program help, and what are its current rules? |
| Community, respite or day services | Assess fees, transportation and the cost of time needed to coordinate attendance | Is the schedule and setting acceptable to the parent? | Who handles enrollment, medication information and pickup? | Is availability limited by location, capacity or eligibility? |
| Residential or assisted setting | Compare the full recurring charge with deposits, care-level changes and the effect on household reserves | Does the setting match the parent’s health, safety and preferences? | Who visits, reviews statements and communicates with staff? | What happens if care needs or finances change? |
Ask each provider or agency for written fees, what is included, cancellation terms, staffing or service limits and the process for changing care levels. Keep those documents with the household plan rather than relying on a verbal estimate.
9. Put the plan into motion over 90 days
- Days 1–14: build the baseline. Collect income, bills, debt, insurance, savings and every parent- and child-related payment. Create the parent document inventory with the parent’s consent.
- Days 15–30: identify the sustainable amount. Separate essentials from flexible support, calculate the effect of current contributions on retirement and emergency savings, and list the events that would force a review.
- Days 31–45: hold the family meeting. Discuss the parent’s preferences, the children’s responsibilities, sibling contributions, care options and who will communicate with providers. Write down decisions and unresolved questions.
- Days 46–60: address authority and protection. Ask the parent’s attorney about a durable financial power of attorney and health-care documents, confirm trusted contacts and secure records. Ask your employer about leave, scheduling and benefit effects.
- Days 61–75: verify taxes and assistance. Check the current IRS rules for the filing year, gather support records, contact the local Medicaid office or other relevant agencies and note eligibility decisions in writing.
- Days 76–90: automate and schedule. Set transfers or bill payments only after the amount is agreed, label reserves by purpose, store the signed family agreement and schedule the next quarterly review.
If the plan cannot cover essentials before support, pause new commitments and seek qualified debt, tax, legal or financial advice. A written “not yet” is safer than an open-ended promise that leads to unpaid bills.
10. Common failure modes and practical fixes
| Failure mode | What it looks like | Fix |
|---|---|---|
| Hidden support | Small transfers, subscriptions and errands are scattered across accounts | Log every parent and child cost for one full month and create separate categories. |
| Caregiving replaces a work plan | Hours are reduced before anyone calculates lost pay, benefits or retirement saving | Model paid, shared and leave options first; ask the employer for written benefit information. |
| Family assumptions conflict | One sibling expects another to pay or provide all care | Hold a meeting, assign specific responsibilities and record review triggers. |
| No legal authority | A relative tries to change investments or pay bills using informal access | Ask the parent’s attorney about appropriate authority; do not transact beyond what the document permits. |
| Tax eligibility is assumed | A caregiver claims a parent because they paid a large bill | Apply every current IRS test, verify the tax-year threshold and keep support records. |
| Outdated benefit information | The budget depends on a program, amount or waiting period found years ago | Confirm with the responsible state or local agency and record the date of confirmation. |
| Care costs are compared only by sticker price | The cheapest option causes missed work, unsafe gaps or repeated emergencies | Compare total household cost, reliability, the parent’s preferences and the effect on savings. |
11. Review the plan when life changes
At each quarterly review, update the cash-flow page, confirm that agreements still match reality and check whether the parent’s records and legal documents remain current. At least annually, review:
- income, work hours, employer benefits and retirement contributions;
- insurance coverage, deductibles and beneficiaries;
- parent and child support totals against the written limits;
- debt balances and any new co-signed obligation;
- care needs, provider fees, housing and transportation;
- the parent’s account inventory, trusted contact and legal authority;
- current IRS rules and any tax professional’s advice; and
- confirmed availability and eligibility for local or state assistance.
Revisit immediately after a hospitalization, job loss, divorce, inheritance, move, death in the family, diagnosis or substantial change in care needs. The purpose of the review is to make one deliberate adjustment, not to relitigate every past decision.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteBottom line
A sustainable sandwich-generation plan makes support visible, sets limits that the household can actually keep, protects the caregiver’s ability to earn and retire, and gives a parent’s finances the right legal safeguards. Written agreements, organized records, current tax checks and verified local assistance turn a series of urgent requests into decisions the family can review and revise.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




