Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →There usually is no true one-day, seven-day, or 30-day car insurance policy from a major U.S. insurer. Auto insurance is commonly sold in six-month or annual terms. The right short-term solution depends on whether you own the vehicle, are borrowing it, renting it, or simply drive an owned car very few miles.
In most cases, the best approach is one of these: buy a normal policy and cancel it when you no longer need it, rely on the owner’s permissive-use coverage for an occasional borrowed car, buy a non-owner policy if you borrow or rent regularly, or combine rental-company and existing insurance for a rental vehicle.
Best temporary car insurance by situation
| Your situation | Usually the best option | What it typically covers |
|---|---|---|
| You own the car and need it for a short period | Buy a standard policy and cancel it after selling or taking the car out of use | Liability plus any collision and comprehensive coverage you select |
| You occasionally borrow a friend’s or relative’s car | Use the owner’s policy after confirming permissive-use terms | Usually liability; damage coverage varies |
| You borrow cars often but do not own one | Non-owner car insurance | Usually your liability to other people, not damage to the borrowed car |
| You rent a car | Check your personal policy, then compare rental-company protection and credit-card benefits | Liability and/or rental-car damage, depending on the coverage |
| You own a car but drive very little | Pay-per-mile or usage-based insurance | Regular auto coverage priced partly on mileage or driving behavior |
| Your car is stored and will not be driven | Ask about reducing coverage while retaining appropriate parked-vehicle protection | Often comprehensive-type protection, subject to policy and state rules |
If you own the vehicle: buy regular insurance, then cancel correctly
If you have just bought a car, the practical substitute for temporary insurance is normally a standard auto policy. You can later cancel it when the vehicle is sold, transferred, permanently taken out of service, or otherwise will not be driven.
Do not cancel merely because you expect not to drive for a few days. An uninsured vehicle may violate state or registration rules, and driving it without liability insurance can result in fines, license or registration consequences, and more expensive insurance later. A financed or leased vehicle will also have insurance requirements imposed by the lender or leasing company.
Free tools Windows power users keep installed
One-click scans. No signup required.
#1 Best Overall

- 【HIGH QUALITY】: made of premium PU leather and durable vinyl PVC, strong and firm enough for your long-term use.
- 【SAFE PROTECTION】: this registration and insurance card holder keeps your document free from tearing, bending or being ruined by moisture.
- 【TIME SAVER】: clear inner pouches design helps you identify the correct document quickly with one glance.
- 【WIDE RANGE OF USES】: can store your bills, insurance cards, vehicle registration and other essential paperwork.
- 【SPECIAL GIFT】: beautiful sleek and trim design. This car document holder is a good gift for yourself, your lover, friends and family.
Before starting the policy, ask the insurer how an early cancellation will work. Get the answers in writing, including:
- The exact date and time coverage ends.
- Whether unused premium will be refunded.
- Whether the insurer charges a cancellation, short-rate, or administrative fee.
- Whether the insurer reports the cancellation to the DMV or whether you must handle that filing.
- Whether your lender, lessor, or state still requires coverage after cancellation.
For example, a registered car may still need insurance even if it sits in a driveway. California generally requires liability insurance for a registered vehicle unless the owner files an Affidavit of Non-Use. A vehicle under that status cannot be driven or parked on public roads.
How to cancel without creating a coverage gap
- Sell, transfer, deregister, or place the vehicle into a legally recognized non-use status.
- Remove or return the plates if your state requires that step.
- Contact the insurer and request a specific cancellation effective date.
- Ask for written confirmation and details of any refund.
- Notify the lender or leasing company if the vehicle is financed or leased.
- Do not drive the vehicle after the cancellation time unless new coverage is active.
If you are borrowing someone else’s car
For occasional, permitted use, the owner’s auto policy is often the first source of coverage. Most liability policies cover a licensed driver who uses the vehicle with the owner’s permission, but the policy may limit coverage or exclude particular drivers and types of use.
Before borrowing the car, confirm all of the following:
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsRank #2

- 👁️Quick Accessible: Inside the car insurance and registration card holder, the clear inner material makes you easy to find documents when you open it up, you can see exactly what they are and quickly show them when asked, even no need to take the stuff out.
- 💼Document Well Organized: The car document holder keeps your car documents organized and keep them tidy and secured, which make it easy to quickly identify and reach paper or cards in the folder. The glove box organizer for car has 6 compartments to keep all your car essential auto car essentials organized.
- 🧲Hidden Magnetic Closure: The glove box document holder are built with hidden magnetic closure, which will keep your car paperwork organizer neat and tidy and ensure the certifications stay closely and and completely protective within the registration pouch.
- 💖Premium Material: The car manual holder is made from high-quality ECO-friendly PU leather material. The car insurance holders with the best sewing and crafted is durable, wear-resistant, and has a luxurious look. This material of the registration holders is durable, wear resistant and waterproof. The insurance card holder for car has a clear window so you can easily see all the documents when you open it up.
- 🌷Compact Size: With the perfect size dimensions of 5.0in x 9.4in x 0.4in, this vehicle license and registration holder for car will fit into glove compartments, sun visors, door holders, consoles, etc. The glove box organizer is precisely designed to fit all of your car documents.
- The owner has given you express permission.
- You have a valid driver’s license.
- You are not listed as an excluded driver.
- You will use the car occasionally, rather than as your regular vehicle.
- You will not use it for delivery, rideshare, or another excluded business purpose.
- The liability limits are adequate for the trip.
- The policy explains whether physical damage is covered when a permissive driver causes an accident.
Permissive use is not the same as purchasing your own temporary policy. The owner’s insurer may reduce coverage for an unlisted driver, and an excluded driver generally is not covered even if the owner gave permission. Someone who lives in the owner’s household or drives the vehicle regularly may need to be listed on the policy.
Best option for regular borrowing: non-owner car insurance
A non-owner auto policy is designed for someone who drives but does not own a vehicle. It generally provides liability coverage for bodily injury and property damage you cause while driving a borrowed or rented car. Depending on the insurer and state, it may also include uninsured or underinsured motorist coverage and medical-payments coverage.
Non-owner insurance is usually written for a normal policy term, not for a single day. It can make sense if you regularly borrow cars, rent vehicles frequently, need an SR-22 filing, or want to maintain continuous insurance history while temporarily not owning a car.
Coverage is commonly secondary to the vehicle owner’s policy. Most importantly, a non-owner policy generally does not cover physical damage to the car you are driving. It is not a substitute for collision coverage, comprehensive coverage, or a rental company’s loss-damage waiver.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteRank #3

- ESSENTIAL Car Auto Insurance Registration BLACK Document Wallet Holders 2 Pieces
When non-owner insurance is a poor fit
- You own the vehicle.
- The car is furnished or available for your regular use.
- You live with the owner and routinely drive the vehicle.
- You need insurance to repair or replace the borrowed car.
- You use the vehicle for rideshare, delivery, or another commercial activity.
Before buying, ask whether the policy applies to the states where you drive, whether it covers rental cars, whether it is secondary, and whether it excludes vehicles available to you regularly.
Best temporary coverage for rental cars
Rental companies often sell several different products. They protect different risks and should not be treated as interchangeable:
| Rental protection | What it may do | What to watch for |
|---|---|---|
| Liability protection | Helps cover injuries or property damage you cause to others | Check limits, exclusions, and whether it is primary or excess |
| Loss-damage or collision-damage waiver | May protect against damage, theft, or vandalism involving the rental car | Exclusions can apply for prohibited drivers, roads, or uses |
| Personal accident coverage | May provide benefits for injuries to the renter or passengers | May overlap with health or life insurance |
| Personal-effects coverage | May cover belongings stolen from the rental vehicle | Homeowners or renters insurance may already provide some protection |
Your personal auto policy may extend liability, comprehensive, and collision coverage to a rental car. That does not automatically mean every rental loss is covered. Confirm whether the rented vehicle qualifies, whether your policy applies in the destination country, and whether it pays loss-of-use charges, administrative fees, towing, or diminished value. Your normal deductible may apply.
Credit-card rental protection is also easy to misunderstand. Many cards focus on collision and theft protection, often on a secondary basis. They generally should not be assumed to provide primary liability insurance. Read the card’s benefit guide, comply with its payment requirements, and check whether you must decline the rental company’s damage waiver.
Rank #4
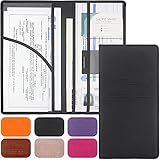
- 💼 CAR ORGANIZER PRACTICALITY: Car registration and insurance holder has multi-function clear compartments which can organize various items very well. The car document holder large pocket for insurance documents and 2 pockets for vehicle registration, 3 small pockets for driver's license, ID cards, AAA cards, business cards, receipt, key contact information cards, etc. It can fully meet your needs
- 👁EASY TO ACCESS AND READ: Car registration and insurance holder keeps your documents organized and keep them tidy and secured, which is stress-free to identify the documents in the folder and quickly reach the document when asked
- 🧲MAGNETIC CLOSURE DESIGN: The car insurance card holder is built with inner magnetic closure, which will keep your vehicle paperwork organizer closed to secure your vehicle documents from humidity and wear and tear. The car insurance holder is your first choice for protecting important car documents and certificates
- ✨PREMIUM MATERIAL: Car registration and insurance holder are made of high-quality PU leather and vinyl PVC. The beautiful cover of 3d embossing provides a comfortable soft touch feeling and professional look. This material is durable, Tolerant, and looks very naturally beautiful
- 💖SECURED & ASSURED: If you have any product problem when you use our car registration and insurance holder. Please feel free to contact us by email, we will do our best to offer a satisfactory solution for you within 24 hours
List every driver on the rental agreement. If an unauthorized person drives, the renter may be responsible for damage even when a waiver was purchased.
Pay-per-mile and usage-based insurance
Pay-per-mile insurance is not temporary insurance, but it can be less expensive than a conventional policy if you own a car and drive it infrequently. These programs generally combine a fixed base charge with a mileage charge.
- Allstate Milewise: uses a daily rate plus a per-mile charge and tracks mileage through a device or connected vehicle. Allstate’s current support information says a reporting failure can result in a default mileage assessment of 40 miles per day.
- Nationwide SmartMiles: combines a base premium with a per-mile premium. Nationwide lists the program as unavailable in Alaska, Hawaii, Louisiana, Michigan, North Carolina, New York, and Oklahoma, although availability and eligibility can change.
- Progressive Snapshot: evaluates driving factors such as mileage, time of day, hard braking, acceleration, and, in some app-based programs, phone use. It is usage-based insurance, not coverage for only a few days, and high-risk driving can affect the rate.
Compare the total cost rather than assuming low mileage guarantees savings. Add the base premium, expected mileage charge, taxes, and fees. A pay-per-mile program may cost more than ordinary insurance for a long commute, road trip, or frequent driving.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.If the car is being stored
Do not cancel every coverage on a stored vehicle without checking with the insurer, your state, and any lender. A parked car can still be stolen, vandalized, damaged by weather, or struck by a falling object.
Best Value

- Protect Your Documents: Car registration and insurance holder protects documents from wear and tear, takes up little space in the glove compartment or on the visor. It enables your essential vehicle and insurance paperwork organized and easily accessible.
- Easy to Find: Your automotive and social security documents are protected and kept neat for inspection with this organizer. When asked, confidently reach for your documents, knowing exactly where they are. Perfect as a glovebox document holder.
- Style: The Canopus premium PVC auto car registration and insurance card organizer has a hook and loop side that securely snaps in place when you are done sorting your documents.
- Great Design: This 5" x 4 1/2" car registration and insurance holder includes 2 clear pockets and easily fits in most truck and car glove boxes or consoles. It is easy to read your registration, insurance documents, business cards, AAA cards, etc. without having to remove them.
- The package includes 2 packs of holders and a Canopus reclosable fastener that works with most toll passes including EZ Pass, IPass, FastLane, and other toll passes.
Some insurers allow an owner to suspend liability and collision coverage while retaining comprehensive-type protection. This may reduce the cost while the vehicle is stored, but the option and eligibility rules vary. Storage coverage does not authorize road use. If the car will be driven—even briefly—it may need active liability insurance and legal registration.
Claims about temporary insurance that are often wrong
| Claim | What is more accurate |
|---|---|
| “Any major insurer can sell me one-day insurance.” | Major U.S. insurers generally sell policies for longer terms. Treat daily or weekly advertisements cautiously and verify the seller’s license. |
| “A non-owner policy covers the car I borrow.” | It is primarily liability coverage and normally does not pay for damage to the borrowed vehicle. |
| “The owner’s policy always covers every permissive driver in full.” | Coverage can be reduced, physical damage may be excluded, and regular or household drivers may need to be listed. |
| “Credit-card rental insurance replaces liability insurance.” | Card benefits often focus on collision and theft and may be secondary. |
| “Temporary substitute vehicle” means temporary insurance. | That phrase usually describes a replacement vehicle used while a covered car is being repaired—not a standalone short-term policy. |
| “Canceling early is always free with a full refund.” | Fees, refunds, notice requirements, and state rules vary by insurer and policy. |
How to choose and buy the right coverage
- Identify who owns the vehicle. Ownership determines whether you need an ordinary policy, permissive-use coverage, or a non-owner policy.
- Ask what coverage already exists. Check the vehicle owner’s policy, your personal policy, the rental agreement, and any credit-card benefits.
- Choose the risk you need to insure. Decide whether you need liability only or also protection for damage to the vehicle.
- Check regular-use and household-driver rules. Do not rely on permissive use if you drive the car routinely or live with its owner.
- Review excluded uses. Confirm coverage for delivery, rideshare, business use, international travel, and all intended drivers.
- Get cancellation terms in writing. Ask about the effective date, refund, fees, and DMV notification before buying a standard policy for a short ownership period.
- Verify the seller. Confirm that the insurer or agent is licensed in your state, especially when an unfamiliar website offers unusually cheap daily coverage.
FAQ
Can I buy one-day car insurance in the U.S.?
Usually not from a major U.S. insurer. Most auto policies run for six months or a year. If you own the car, a standard policy that you later cancel is usually the practical alternative; if you are borrowing or renting, check the owner’s, rental company’s, personal, or non-owner coverage.
Does non-owner car insurance cover damage to a borrowed car?
Generally, no. Non-owner insurance is mainly liability coverage for injuries or property damage you cause to others. It normally does not include collision or comprehensive coverage for the borrowed vehicle.
Am I covered when I borrow a friend’s car?
You may be covered under the owner’s policy if you have permission and use the car occasionally. Coverage can be reduced or excluded for household members, regular drivers, excluded drivers, business use, or damage to the vehicle. Confirm the policy terms before driving.
What is the cheapest way to insure a car I rarely drive?
Compare a conventional policy with a pay-per-mile or usage-based plan. If the car is stored, ask whether the insurer permits reduced coverage while retaining appropriate protection against theft and other parked-vehicle damage. Do not drive a stored or uninsured vehicle until liability coverage is active.
The Bottom Line
For most U.S. drivers, the best “temporary car insurance” is not a special one-day policy. If you own the car, buy standard coverage and cancel it only after the vehicle is legally no longer being driven. If you occasionally borrow a car, confirm the owner’s permissive-use coverage. If you borrow or rent regularly without owning a car, compare a non-owner policy with rental-company protection—but remember that non-owner insurance generally does not cover damage to the vehicle itself.
Before paying an unfamiliar seller, verify the insurer’s license, exclusions, cancellation terms, and the exact date coverage begins and ends.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →



