What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
There is no single best term-life insurer for every applicant. The right choice depends on your age, health, tobacco use, state, coverage amount, desired term, military or occupational risks, and whether you may need to convert the policy later.
For U.S. individual term life insurance, our 2026 shortlist is organized by use case rather than a rigid ranking: Pacific Life for a strong all-around balance, Banner Life and William Penn for long terms and price-sensitive shoppers, Protective for 35- and 40-year coverage, Guardian for certain health situations, New York Life for annual renewable term and agent support, USAA for military households, and Thrivent for conversion flexibility when you qualify.
Research date: August 10, 2026. Rates, underwriting rules, policy forms, ratings, and state availability can change. Use this guide to build a shortlist, then obtain quotes using identical assumptions and read the actual policy contract before replacing existing coverage.
As an Amazon Associate I earn from qualifying purchases.
7 Best Term Life Insurance Companies of 2026
Quick comparison
The companies below are editorial picks for particular situations—not a claim that any one carrier is always cheapest or best. A company-level rating or customer-service score also does not necessarily describe the specific term policy you will receive. For example, NerdWallet says its ratings apply to the insurer overall, not specifically to its term policy.
| Company | Best for | Published term options | Published coverage information | Purchase channel | Main limitation | Financial-strength evidence |
|---|---|---|---|---|---|---|
| Pacific Life | Healthy applicants seeking a broad, flexible term menu | 10, 15, 20, 25, or 30 years | $50,000 minimum; up to $3 million for the reviewed product | Carrier or agent-assisted process; accelerated underwriting may apply | Traditional PL Promise Term is unavailable in New York; conversion choices are comparatively narrow | A+ AM Best, affirmed December 11, 2025 |
| Banner Life family Banner Life and William Penn |
Long terms and price-sensitive applicants | 10, 15, 20, 25, 30, 35, or 40 years | Starts at $100,000 and can exceed $10 million, subject to underwriting | Agent or broker distribution | William Penn is the New York issuer; term-length and age limits vary | Banner’s financial-strength page lists AM Best A, Fitch A+, and S&P A; page updates shown in early 2026 |
| Protective | 35- and 40-year level term | 10, 15, 20, 25, 30, 35, or 40 years | $100,000 to $50 million, subject to financial justification and underwriting | Agent or broker-assisted process | Long-term policies have strict issue-age limits and can be costly | A+ Superior AM Best rating for primary life subsidiaries, affirmed September 4, 2025 |
| Guardian | Applicants with certain managed health conditions | One-year, 10, 15, 20, or 30 years in the reviewed materials | $100,000 to $5 million in NerdWallet’s review; qualified HIV applicants may be considered for $100,000 to $10 million | Generally agent-based | Health-condition pathways are not guarantees and may have specific requirements | A++ Superior AM Best, affirmed September 12, 2025 |
| New York Life | Annual renewable term and agent support | Yearly renewable term; level terms of 10, 15, or 20 years in reviewed materials | At least $250,000 for yearly renewable term and $100,000 for level term in NerdWallet’s review | Agent quote generally required | Annual premiums rise with age and may be less competitive for a long fixed term | Verify the current rating of the exact issuing company before applying; the reviewed materials did not supply a dated rating |
| USAA | Military households | Typically 10 to 30 years | $100,000 to $10 million and ages 18–70 in NerdWallet’s reviewed information | Direct and member-oriented service | Military riders, eligibility, exclusions, and state forms must be checked in the policy | Verify the current rating and legal issuer for the product selected |
| Thrivent | Conversion flexibility, if eligible | 10, 15, 20, or 30 years | $100,000 to $2 million on Thrivent Direct’s page; NerdWallet lists up to $3 million for its reviewed product | Online entry point followed by financial-professional assistance | Faith-affiliation eligibility applies; Thrivent Direct is unavailable in New York | Verify the current rating of the exact issuing company before applying; the reviewed materials did not supply a dated rating |
Coverage limits, issue ages, riders, conversion rights, and availability are product- and state-specific. A published maximum is not a promise that every applicant can obtain that amount.
#1 Best Overall

- 【Large Accordion File Organizer】- Expandable from 2 inch to 20.5 inch, Yoassi expanding file folder can hold up to 4000 sheets Legal / Letter / A4 /A5/A6/A7/A8 size papers and makes files easy to access.
- 【Improved Size For Legal / Letter Papers】- Most alphabetical file folders can not fit legal papers, so we extended its length to 15.2 inch, the height to 10 inch to make sure the labels not being blocked by documents.
- 【Thickened Pockets & Shell】- Traditional accordian folders are prone to ripped during high frequency use. Yoassi reinforce the thickness of the 24 inner pockets to 0.032 inches, 44% thicker than the normal files folders sold at AMAZON whose thickness is 0.018 inches only.
- 【Extra Tabs & Stickers】- The 64 stickers & Card holders at the front gives your files a convenient classification.
- 【Important Document Organizer 】- A capable assistant on sorting legal papers, tax receipts, bills, loan documents, letter of instruction, deeds files, student's assignments, etc.
What term life insurance is—and what it is not
Term life insurance covers you for a defined period, such as 10, 20, or 30 years. If you die while the policy is active and premiums are current, the insurer generally pays the policy’s death benefit to the beneficiaries. If you are alive when the term ends, the policy normally expires without a death benefit.
Unlike whole life or universal life insurance, ordinary term insurance generally does not build cash value. Its principal advantages are straightforward protection and a lower initial premium than comparable permanent insurance. The National Association of Insurance Commissioners describes term insurance as lower-cost coverage for a specific period.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Common forms include:
- Level-premium term: The premium is designed to remain level for the selected period. This is the most common comparison for family income replacement.
- Annual renewable term: The policy renews one year at a time, usually without new proof of insurability, but the premium generally rises as you get older.
- Convertible term: The owner can exchange some or all of the term coverage for an eligible permanent policy without new medical underwriting, subject to the contract’s deadline and product rules.
- Decreasing term: The death benefit declines over time, making it potentially suitable for a debt that is being paid down.
- Return-of-premium term: A policy form that may return specified premiums if the insured outlives the term. It typically requires a different premium structure and should be compared against simply buying lower-cost level term and investing the difference.
Term insurance is not automatically right for everyone. Someone with no dependents, no debt that another person would inherit, and no financial obligation to another person may have little need for an individual policy. Employer coverage, savings, or permanent insurance may also be part of the answer—but they should be measured against the actual financial need.
1. Pacific Life: best overall for many healthy applicants
Pacific Life is the strongest all-around starting point for many healthy shoppers who want a conventional level-term policy, a 25-year option, and a defined conversion path. “Best overall” here means the best balance in this guide among term choices, issue-age flexibility, underwriting convenience, pricing potential, and conversion—not universally the lowest premium.
What the policy offers
- Product: PL Promise Term.
- Level terms: 10, 15, 20, 25, and 30 years.
- Issue ages: Public product material lists ages 18–80, subject to the product and state.
- Coverage: $50,000 minimum; Forbes reports up to $3 million for the reviewed product.
- Accelerated underwriting: Pacific Life’s PAL+ process may provide up to $3 million without a medical exam for eligible applicants ages 18–60. “May” is important: eligibility does not guarantee an exam-free decision.
- Conversion: PL Promise Term can generally convert during the level-premium period, up to the applicable age limit, to PL Promise Conversion UL without new underwriting. The eligible product and deadline should be confirmed in the policy issued in your state.
See Pacific Life’s product page and client guide for current product details.
Strengths and limitations
- Strengths: The 25-year term is useful for a mortgage or family need that falls between the common 20- and 30-year choices. The high published issue age may also help older applicants who remain insurable.
- Limitations: The conversion route is narrower than a policy that permits conversion to several permanent products. The $3 million PAL+ amount is an eligibility ceiling, not a guaranteed no-exam amount. Traditional PL Promise Term is not available in New York.
Pacific Life Insurance Company’s A+ AM Best financial-strength rating was affirmed December 11, 2025, according to AM Best’s company profile. Ratings are opinions about financial strength and can change; they do not tell you whether the policy’s conversion deadline or premium fits your needs.
Free tools Windows power users keep installed
One-click scans. No signup required.
2. Banner Life family: best for long terms and price-sensitive applicants
Banner Life and William Penn should be treated as one product family for comparison purposes, but they are not one legal insurer. Banner Life sells in 49 states and Washington, D.C.; William Penn sells exclusively in New York. The state determines which legal company and policy form you receive.
What the policy offers
- Product: OPTerm.
- Terms: 10, 15, 20, 25, 30, 35, and 40 years.
- Coverage: Starts at $100,000 and can exceed $10 million depending on underwriting and financial need.
- Issue ages: Generally 20–75, with limits that vary by term duration and underwriting.
- Flexibility: Renewable and convertible term policies are available, along with stackable term riders.
The broad term menu makes this family particularly useful for people who need 35 or 40 years of level protection but do not want to buy permanent insurance immediately. A stackable rider can also provide extra early coverage that declines as a mortgage balance falls or children become financially independent.
Review the term product page, OPTerm information, and company and state structure before applying.
Strengths and limitations
- Strengths: One of the broadest level-term menus available, including 35- and 40-year periods. It can be a useful quote for price-sensitive applicants, smokers, and some people with family-history concerns, although actual underwriting decides the result.
- Limitations: A 40-year policy can be expensive and may outlast the actual need. Age limits become more restrictive for the longest terms. Banner’s advertised examples, including a “starting at” monthly price, are tied to a particular age, health class, coverage amount, and date—not a representative quote.
Banner’s financial-strength page lists AM Best A, Fitch A+, and S&P A, with page updates shown in January through March 2026. Check the current financial-strength page and the legal issuer named in the application.
3. Protective: best for 35- and 40-year level term
Protective is a particularly clear fit when a 30-year policy is not long enough. Its Classic Choice term product offers 35- and 40-year periods, although those durations have strict issue-age and tobacco-status limits.
What the policy offers
- Product: Protective Classic Choice term.
- Terms: 10, 15, 20, 25, 30, 35, and 40 years.
- Coverage: $100,000 to $50 million, subject to underwriting and financial-need justification.
- Premium: Guaranteed and level during the selected term.
- Conversion: Conversion to permanent insurance without a medical exam is available under the product’s rules, but the eligible permanent products, deadline, amount, and state availability vary.
- Age limits: A December 2025 product sheet shows 40-year issue ages generally up to 45 for non-tobacco applicants, with different limits for tobacco applicants.
Read the Protective product page and the Classic Choice term sheet for the relevant issue-age and conversion details.
Strengths and limitations
- Strengths: It is one of the strongest comparisons for coverage that needs to continue through most of a person’s working years. The high published coverage ceiling and conversion feature add flexibility for applicants with substantial, documented financial needs.
- Limitations: The $50 million maximum is not broadly available. A 35- or 40-year term may cost much more than a shorter policy or a ladder of policies. Conversion rights vary by term length and product.
Protective’s primary life subsidiaries had an A+ Superior AM Best financial-strength rating affirmed September 4, 2025, according to AM Best’s announcement.
4. Guardian: best for certain health conditions
Guardian is worth placing in the quote set when an applicant has a particular managed health condition that may receive different treatment from one insurer to another. It is especially notable because Guardian publicly describes an underwriting pathway for some qualified applicants living with HIV.
What the policy offers
- Product: Guardian Level Term.
- Terms: One-year, 10, 15, 20, and 30 years in the reviewed materials.
- Coverage: NerdWallet lists $100,000 to $5 million for the reviewed term product. Guardian says qualified applicants living with HIV may be considered for $100,000 to $10 million, at standard or substandard premiums depending on the complete application.
- Features and riders: The reviewed materials identify conversion, waiver-of-premium, guaranteed-renewability, accelerated-death, accidental-death, and charitable-benefit provisions, depending on policy and rider selection.
- Distribution: Applicants generally work through an agent rather than completing the entire purchase online.
Guardian’s level-term explanation and HIV underwriting page explain the relevant distinctions. The HIV pathway has specific medical and treatment requirements; it is not guaranteed acceptance or guaranteed standard pricing.
Strengths and limitations
- Strengths: A specific health-condition underwriting pathway can make Guardian an important comparison that a generic cheapest-price list would miss. Guardian also has a strong financial-strength profile and favorable complaint indicators in current secondary comparisons.
- Limitations: No insurer can promise approval based solely on a diagnosis label. Underwriting may depend on the date of diagnosis, treatment, medication, control, complications, age, tobacco use, requested amount, and state.
Guardian Life’s A++ Superior AM Best rating was affirmed September 12, 2025. See AM Best’s announcement. An A++ rating is not proof that Guardian will offer the lowest rate or the most favorable conversion provision.
Rank #2

- Double Layers Protection: Our newly designed file folder uses different materials than other folder.Double Layered design, high quality Black Non-itchy Liquid Silicone Coated Fireproof Fiberglass which can withstand temperatures as high as 1832℉,this bag is FIRE and WATER RESISTANT.Fireproof file folders can fully protect your important documents, paper,birth certificate, passport.
- Size: 16" x 10.6" x 0.8"(Legal size) ,Weight:450g/15.9ounce,13 individual pockets. Fireproof file folder makes it suitable for daily filing and storing of documents(with Color Labels).
- Wide Range of Applications: Fireproof zipper added security and safe transport.It's very durable.Not only can you put your file folder at home, office, car,it's also a good decision to put it in the safe box. You can be 100% assured that your important information is in a safe place.
- Perfect Gift:Beautiful design and creative folders can also be used as anniversaries or personal gifts for students, employees, colleagues, etc.
- Customer Service: ENGPOW provide friendly after-sale service and no risk refund for our customers. If you have any issue,please contact us and we will try out best to solve your issue!
5. New York Life: best for annual renewable term and agent support
New York Life belongs on this list because some buyers value guaranteed renewal and agent guidance more than the lowest long-term level premium. Its yearly renewable term can be useful when the need is temporary or when preserving future insurability matters.
What the policy offers
- Products: Yearly Renewable Term and Level Premium Term.
- Level terms: 10, 15, and 20 years in the reviewed materials.
- Coverage: NerdWallet lists at least $250,000 for yearly renewable term and $100,000 for level premium term.
- Issue ages: Generally 18–75 in NerdWallet’s reviewed information.
- Conversion: Both term types can be converted to permanent coverage under the applicable contract rules.
- Purchase process: Quotes generally require contact with a New York Life agent rather than an instant online quote.
See New York Life’s pages on term products, annual renewable and level term, and term comparisons.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Strengths and limitations
- Strengths: Annual renewal can avoid a new medical examination when you need to continue coverage. Conversion can also preserve an option to obtain permanent insurance after a health change. Agent support may be valuable for older applicants or complex financial situations.
- Limitations: Annual premiums rise as the insured ages and can become an expensive long-term strategy. New York Life may not be price-competitive with specialized term carriers for a healthy buyer seeking a fixed 20- or 30-year policy.
Before choosing yearly renewable term, ask for the actual premium schedule, maximum renewal age, and conversion deadline. “Guaranteed renewable” does not mean “guaranteed level price.”
6. USAA: best for military households
USAA is the most situation-specific pick on this list. Its value is not simply a generic term policy; military households should examine provisions related to deployment, war, military injury, and future insurability.
What the policy offers
- Terms: Typically 10 to 30 years.
- Coverage: NerdWallet lists $100,000 to $10 million and ages 18–70 for the reviewed products.
- Military features: USAA describes coverage during war, guaranteed coverage after leaving the military, expedited handling for deployment-related applications, and a Military Severe Injury Benefit Rider.
- Severe-injury benefit: USAA states that the rider can provide up to $25,000 for qualifying injuries.
- Future insurability: Eligible policyholders may have future-insurability and life-event coverage-increase features.
Review USAA’s military-benefits page and level-term information. The actual rider, exclusions, eligibility rules, state form, occupation provisions, and legal issuing company control.
What military families should compare
Compare individual coverage with SGLI and VGLI rather than assuming either is sufficient. Ask specifically about deployment, combat or war exclusions, special operations, aviation, hazardous duty, and what happens if the insured separates from service. USAA’s military-specific features make it a logical quote, but they do not eliminate the need to compare the private-market premium and contract.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minute7. Thrivent: best for conversion flexibility, if eligible
Thrivent is a strong fit for an eligible applicant who wants term coverage now but is concerned that a future health change could make permanent insurance difficult to obtain. Its conversion privilege can preserve insurability—but the deadline is more limited than many readers assume.
What the policy offers
- Product: Thrivent Direct term insurance.
- Terms: 10, 15, 20, and 30 years.
- Issue ages: 18–75 on the listed product, with narrower limits for longer terms.
- Coverage: $100,000 to $2 million on Thrivent Direct’s plan-details page; NerdWallet lists up to $3 million for its reviewed product.
- Conversion: During the first five years, the policy can be converted in whole or in part to an eligible Thrivent permanent product without underwriting or health questions. An extended conversion rider may allow conversion later, subject to its terms.
- Distribution: The online process is an entry point, but completing the application requires working with a financial professional.
Check the current Thrivent plan details, online product page, and conversion explanation.
Important eligibility and state limitation
Thrivent insurance is restricted to applicants who meet its faith-affiliation eligibility requirements, according to NerdWallet’s current review. That restriction belongs near the recommendation, not buried in the application process. The listed Thrivent Direct product is also unavailable in New York.
Conversion without new underwriting does not mean the permanent policy will be inexpensive. Premiums are based on the permanent product and its pricing rules, so ask for an illustration before converting.
How these companies were selected
This is a dated editorial synthesis for U.S. individual term life insurance. We considered:
- Financial strength and claims-paying ability.
- Comparable pricing potential across different ages, terms, coverage amounts, health profiles, and tobacco statuses.
- Availability of 10- through 40-year level terms.
- Conversion deadlines, eligible permanent products, and renewal rights.
- Accelerated or alternative underwriting and the treatment of specific health conditions.
- Complaint information, using the appropriate legal subsidiary and complaint index rather than raw complaint counts.
- Customer experience and distribution, including direct, online, agent, and broker channels.
- State availability and transparency about product limitations.
Other current comparisons reach different conclusions because they use different methods. Forbes Advisor’s August 2026 analysis evaluated 15 insurers using rates, consumer sentiment, conversion options, complaints, and guaranteed renewability, and highlighted Pacific Life, Minnesota Life, Symetra, Western & Southern, and Protective. NerdWallet’s June 2026 list named Guardian, New York Life, USAA, Northwestern Mutual, and Thrivent. MoneyGeek’s July 2026 analysis named Banner Life, Transamerica, and Nationwide. The differences show why a ranking is not a substitute for profile-specific quotes.
Customer satisfaction is another separate measure. In J.D. Power’s 2025 individual-life study, Mutual of Omaha ranked highest overall, followed by State Farm and Nationwide. That does not make those companies the cheapest or best fit for every term-policy buyer.
How much term life insurance do you need?
Do not use “10 times income” as a universal answer. Start with a needs-based estimate:
Recommended Free Tools
Rank #3
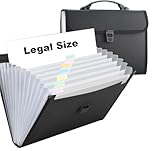
- Expanding File Folder - This accordian file organizer have 13 Legal size/Foolscap pockets. Most file folders can not fit legal papers, this expanding file folder larger than Letter size /A4 folder, it is great for organizing 9’’x 14’’/8.5’’ x 14’’ papers, files, scripts, notebooks, etc.
- Expandable File Folder Organizer - Ergonomic adjustable handle and upgrade buckle keeps contents safe and secure. It's a great assistant when your documents are always on the go.
- Easy Divide & Clear Organization - This accordion file organizer come with blank index labels, keep each slot separated and organized. Two name card pockets for easy marking of this filing briefcase.
- Large Capacity - The file organizer size: 15.2’’x 10.2’’x 1.2’’. Sturdy bottom ensure your important documents will never fall out. Suitable for home, office, school and travel.
- Security & Strong - This expanding file briefcase made of premium PP, oxford reinforced prevent sides from tearing, the outer matte cover gives you a great feel, leaving no fingerprints and scratches. Great assistant on sorting legal papers, tax receipts, bills, loan documents, letter of instruction, deeds files, student's assignments, etc.
Coverage need = income replacement + mortgage and debts + education and childcare + final expenses + special-needs funding + business obligations - savings and investments - existing individual life insurance - other reliable resourcesThe DIME method—debt, income, mortgage, and education—is a useful starting framework. Then adjust for taxes, inflation, childcare, the cost of replacing a stay-at-home parent’s work, special-needs care, business commitments, and the surviving household’s existing assets.
Coverage should replace the financial contribution that would disappear, not merely a salary. A stay-at-home parent may require substantial coverage because childcare, transportation, household management, and other services would need to be purchased. Employer coverage is an asset in the calculation, but it may be limited, age-based, or lost when you change jobs.
Guardian’s consumer material similarly describes coverage needs as dependent on income, assets, debt, marital status, health, and dependents rather than a single multiplier.
How long should the policy last?
Choose the term to cover the longest period of financial dependence—not merely the shortest term with an attractive initial premium.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstall| Term | Potential fit | What to check |
|---|---|---|
| 10 years | A short debt, business obligation, or late-career need | Whether the obligation truly ends within a decade |
| 15 years | A mortgage nearing payoff or children approaching college age | Education and childcare timing |
| 20 years | A common choice for a family with children | Whether the youngest dependent will still need support afterward |
| 25 years | A longer mortgage or family formed later | Whether a 25-year product is available in your state |
| 30 years | A young parent or new homeowner with decades of working-life exposure | Cost versus the likelihood that the need lasts 30 years |
| 35 or 40 years | Coverage through most working years | Strict issue-age limits, tobacco rules, and the higher premium |
A shorter term is not automatically better. Replacing it later may be more expensive or impossible after a health change. A longer term is not automatically better either: it may cost substantially more and outlast the actual obligation. A ladder of multiple policies—such as a larger 20-year policy plus a smaller 30-year policy—can sometimes match declining needs more efficiently than one large long-term policy.
How much does term life insurance cost?
There is no responsible single answer to what a $500,000 policy costs. The premium can change materially with age, sex classification used by the insurer and jurisdiction, tobacco use and time since quitting, health history, medications, family history, height and weight, occupation, driving record, hazardous activities, coverage amount, term, state, underwriting class, and payment method.
A valid comparison should use the same assumptions for every carrier. For example:
| Quote variable | Use the same assumption across carriers |
|---|---|
| Applicants | Age 30 and age 40; compare the applicable sex classifications separately |
| Health | Preferred nonsmoker for the baseline, then separate smoker and health-condition scenarios |
| Coverage | $500,000 and $1 million |
| Terms | 10, 20, 25, and 30 years; add 35 or 40 years where available |
| Payment | Compare annual and monthly payment totals |
| Location | Identify one state; repeat the comparison in the applicant’s actual state |
| Date | Record the quote date; use current policy forms |
Run separate comparisons for a healthy nonsmoker, an older applicant, a smoker, and an applicant with a health condition. Do not use a young healthy applicant’s marketing example to represent an older buyer or someone with a different underwriting profile. Annual payment may also cost less overall than paying monthly, depending on the carrier’s modal factors.
The cheapest carrier can change substantially by age, coverage amount, term, state, health, and tobacco status. For that reason, compare at least three carriers—and preferably a mix of specialized term insurers and carriers known for the applicant’s specific situation.
The policy features that matter most
Financial strength
AM Best, S&P, Moody’s, and Fitch ratings are opinions about an insurer’s ability to meet obligations, not guarantees of claims payment or evidence that a policy is suitable. Identify the exact legal company issuing the policy; do not substitute a parent-company rating for a subsidiary’s rating.
Ratings are also dated. An A++ affirmed in September 2025 and an A+ affirmed in December 2025 are both strong financial-strength opinions, but they are not policy comparisons and neither is permanent. The California Department of Insurance consumer guide recommends considering financial soundness and using independent rating agencies.
Conversion rights
Ask these questions in writing:
- Is conversion included or does it require a rider?
- What is the exact conversion deadline?
- Can all or only part of the death benefit be converted?
- Which permanent products are eligible?
- Is the original underwriting class retained?
- Is conversion allowed while disabled or after a claim?
- Is conversion available in your state?
- Are premiums based on attained age when you convert?
“Convertible” alone is not enough. A conversion option can preserve insurability, but the resulting permanent policy may be substantially more expensive and may have different guarantees, fees, cash-value treatment, and surrender provisions.
Renewability
Distinguish level term from annual renewable and guaranteed renewable coverage. A renewable policy may continue without new medical evidence, but the premium can rise sharply with age. Ask for the premium schedule and maximum renewal age before buying. The NAIC specifically advises consumers to ask about renewal premiums and the maximum renewal age.
Rank #4
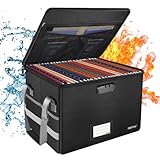
- Fireproof and water-resistant: Fireproof lock box is made of double layered non-itchy silicone coated fiberglass which stands up the temperature up to 2000℉.It has passed the UL94 -V0/5VA flame retardant test.Fireproof file box is not only fireproof but also high water resistant in case it gets wet for any reason.Nothing is completely foolproof, but added protection is always a good idea.
- Anti-static and reflective strip design:Are you still worried about the storage box is often covered with dust? The anti-static material can prevent dust from sticking to the outside of our fireproof box, always keep it neat and tidy.The reflective strip design on the side of the box allows you to immediately find your fireproof box even at night, protecting irreplaceable documents and valuables from fire.
- Portable and secure: High quality combination lock design for added storage security, includes instruction manual for combination lock. Sturdy adjustable handle makes it easy to carry everything you need(You can adjust the carrying handle to the length you want), two zippers make it easier to open and close the box, Side pockets and label slots let you store small items and labels.The file lock box collapses down simply for easier storage when not in use.
- Dimensions: 15.55" x 12.2" x 10".The fireproof lock box fits both letter and legal size files fitting your filing system,it also can protect your important documents,books,CDs, DVDs,USBs,albums,passports, social security cards,birth certificates and other valuables.Combining our fireproof bag and fireproof safe box together is the best solution to offer your documents and valuables a complete protection in any fire accident.
- Trusted after sales service:How can we better protect our valuables from any fire? ENGPOW keep researching and developing on fireproof materials,safety technology.We only wish to present the best to customers,to protect your valuables.If there any quality problem, please feel free to let us know.We promise to arrange a REPLACEMENT or 100% REFUND immediately. Ready to respond within a 24 hour time,your suggestion has a great impact on the upgrade of our products.
Distribution and customer experience
Some carriers quote online; others require an agent or financial professional. An independent broker may compare several insurers, while a captive agent may offer deeper support for one carrier’s products. Neither channel is automatically better, but the difference affects the help you receive during underwriting, policy delivery, conversion, and claims.
J.D. Power’s 2025 study found that direct-to-carrier purchasers averaged 696 satisfaction points, while customers purchasing through agents, brokers, agencies, or financial advisers averaged 57 points lower. The study also found materially higher satisfaction when customers had a trusted agent relationship than when that relationship was disengaged. Distribution channel and the quality of the relationship therefore matter, not just the insurer’s name.
Complaint data
Use the NAIC Consumer Insurance Search to check the correct legal subsidiary, individual-life complaints, and the latest available three-year period. Focus on the complaint index rather than raw complaint counts, because large insurers naturally receive more complaints simply due to their size.
The NAIC explains that complaint indexes are affected by complaint volume, premiums, market conditions, and company size. Treat the index as one input—not a complete quality score.
How to choose: a practical decision guide
- Healthy and price-sensitive, with a 20- or 30-year need: Compare Pacific Life, Banner, Protective, and at least two additional carriers using the same quote assumptions.
- Need 35 or 40 years: Start with Banner and Protective. Check issue-age limits before spending time on an application.
- Have a health condition or HIV: Include Guardian and ask an independent broker to submit an informal inquiry to other carriers. Do not assume one diagnosis predicts the result.
- Military household: Compare USAA with SGLI or VGLI and independent-market quotes. Review deployment, war, aviation, hazardous-duty, and post-service provisions.
- May need permanent coverage later: Compare Thrivent, Guardian, Pacific Life, and New York Life by reading the exact conversion deadline and eligible product list.
- Need annual renewable coverage: Compare New York Life and other annual-renewable options, including Northwestern Mutual, but model the premium increases year by year.
- Live in New York: Verify the legal issuer and product form. Pacific Life’s traditional PL Promise Term and the listed Thrivent Direct product are unavailable in New York; William Penn is the Banner family’s New York issuer.
The application process, step by step
- Calculate the need. Include debt, income replacement, dependents, education, childcare, existing assets, employer coverage, business obligations, and future expenses.
- Choose the target term. Base it on the longest financial responsibility, not just the lowest initial premium.
- Obtain preliminary comparisons. Use an independent broker or several direct carriers before submitting formal applications.
- Ask about underwriting fit. Tell the broker or agent about age, diagnoses, medications, tobacco, driving, occupation, aviation, dangerous sports, and foreign travel. Ask which carriers are likely to be competitive before creating an application record.
- Standardize the quotes. Keep the state, amount, term, tobacco status, payment frequency, and desired underwriting class consistent.
- Complete the application accurately. Omissions or inaccurate answers about medications, diagnoses, marijuana, tobacco, alcohol, driving, or hazardous activities can create problems during underwriting or a later claim.
- Authorize data collection. Accelerated underwriting may use prescription history, medical records, motor-vehicle records, MIB data, public records, and other external information.
- Complete the required underwriting. This could mean no exam with data-based underwriting, a telephone interview, a paramedical examination, blood or urine testing, saliva testing, or medical-record review.
- Review the offer. Check the rate class, annual premium, policy fee, riders, exclusions, conversion deadline, renewal schedule, and legal issuing company.
- Keep existing coverage in force. Do not cancel an old policy until the new policy is issued, accepted, delivered, and within any applicable free-look period.
- Check the issued policy. Confirm beneficiaries, ownership, premium mode, amount, term, riders, exclusions, and delivery documents.
- Calendar future dates. Record the conversion deadline, renewal dates, free-look deadline, and a periodic coverage review.
The NAIC notes that accelerated underwriting may remove the exam but does not guarantee issuance without traditional underwriting. An applicant initially routed to an accelerated process may still be referred for an examination or additional medical records.
What to do if you are rated, delayed, or declined
If you are rated
A rated offer means the insurer approved coverage but at a higher premium than the preferred or standard estimate. Ask for the specific rating reason, whether a corrected medical record could change the decision, and whether another carrier’s underwriting is more favorable. Do not conceal the condition on a new application.
If the application is delayed
Ask what is missing: an attending physician statement, prescription clarification, lab result, telephone interview, financial justification, or occupation questionnaire. Respond promptly and keep copies of every submission. A delay is not a decline, but a quote is not coverage until the policy is issued and accepted.
Recommended Free Tools
If you are declined
- Ask for the general underwriting reason and whether the decision is postponement, decline, or a request for more information.
- Request your medical records and correct factual errors with the provider.
- Ask an independent broker about carriers with different underwriting approaches; do not submit multiple applications blindly.
- If MIB information influenced the decision, request your consumer file and dispute inaccurate information.
- Consider a lower amount, a shorter term, a different underwriting class, or a guaranteed-issue product only after understanding its limits and cost.
- Keep any existing policy active while alternatives are evaluated.
MIB explains how consumers can request their file. A MIB file generally exists only when a person applied with a member carrier and underwriting-significant information was found. Correcting an error does not guarantee that a carrier will approve coverage, but it can prevent inaccurate information from being reused.
Special cases that can change the answer
No-medical-exam policies
No exam does not mean no underwriting. The insurer may still review prescriptions, medical records, MIB data, driving records, public records, financial information, and hazardous-activity information. Some applicants are initially offered accelerated underwriting and later referred for a conventional exam. Compare the premium, maximum amount, approval speed, and conversion rights—not just the absence of an exam.
Health conditions
There is no reliable universal “best insurer for diabetes,” depression, cancer survivors, or any other diagnosis. Underwriting can depend on the diagnosis date, treatment status, medications, control level, complications, age, coverage amount, state, and smoking status. Use a broker who can make informal inquiries before submitting a formal application.
Tobacco, marijuana, alcohol, and recreational drugs
Ask every carrier how it defines cigarette use, cigars, nicotine replacement, vaping, marijuana frequency and route, alcohol history, DUI history, and recovery periods. A “nonsmoker” classification is not identical across insurers. Answer every question consistently and accurately.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallMilitary, aviation, and hazardous occupations
Ask about deployment, combat or war exclusions, special operations, piloting, skydiving, scuba diving, private aircraft, offshore work, law enforcement, and emergency-response duties. These factors may affect eligibility, premium class, exclusions, or rider availability.
Employer life insurance
Employer coverage can supplement an individual policy, but it may be limited, age-based, or not portable after you leave the job. Calculate the household’s need independently, then subtract only the employer benefit that is reliable under the expected employment situation.
Best Value

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
Replacing an existing policy
Do not replace an existing policy casually. A replacement can reset contestability periods and suicide exclusions where applicable, create new underwriting risk, trigger surrender charges on permanent coverage, remove favorable conversion rights, and produce a higher premium because you are older. The California Department of Insurance guide discusses buyer documents and replacement warnings. The policy and state replacement rules control.
Alternatives to a single term policy
- Permanent life insurance: Consider it when the financial need is lifelong, estate planning is central, or a permanent death benefit is more important than minimizing initial cost.
- Employer coverage: Useful as a supplement, but review portability, amount, and age-based pricing.
- Accidental-death coverage: It may supplement life insurance but does not replace income-replacement coverage because it pays only for covered accidental deaths.
- Decreasing-term coverage: Potentially appropriate for a debt whose balance declines.
- A policy ladder: Multiple term policies can match different obligations that end at different times.
- No individual policy: May be reasonable when nobody depends on your income or financial support and no meaningful debt or obligation would transfer to another person.
Frequently Asked Questions
Is term life insurance worth it?
It is often worth considering when a spouse, child, business partner, or other person depends on your income or would inherit your debts and expenses. Term coverage can provide a large death benefit at a lower initial premium than comparable permanent insurance. It may be unnecessary for someone with no dependents, no significant obligations, and enough assets to cover the consequences of death.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsHow much does a $500,000 term-life policy cost?
There is no universal price. Age, state, term length, health, tobacco use, coverage class, occupation, and payment frequency can change the premium substantially. Obtain quotes for the same applicant profile, $500,000 amount, term, state, and payment mode from several carriers. A marketing example for a young healthy applicant is not a quote for everyone.
Is a 20-year or 30-year term better?
Choose the term that lasts through the longest period of financial dependence. Twenty years may cover children until adulthood for some families; 30 years may better fit a young parent, new homeowner, or late-starting family. A 30-year policy costs more, but buying a cheap 20-year policy and reapplying later can be expensive or impossible after a health change.
What happens if I outlive my term policy?
The policy normally expires and pays no death benefit if you are alive. Depending on the contract, you may be able to renew annually at higher age-based premiums, convert some or all coverage to an eligible permanent policy without new medical underwriting, or apply for a new policy subject to your then-current age and health. The policy contract controls the deadline and options.
Can I renew term life insurance without a medical exam?
Many renewable policies permit renewal without new proof of insurability, but the premium can increase substantially as you age. Check the renewal schedule and maximum renewal age. Guaranteed renewal means the insurer cannot require new medical evidence under the contract; it does not mean the premium stays level.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Can I convert term life insurance to whole life?
Some term policies can be converted to whole life, universal life, or another eligible permanent product, but the exact choices vary. Check the conversion deadline, whether partial conversion is permitted, the eligible products, and the premium calculation. Convertible does not mean the permanent policy will be inexpensive, and not every policy converts specifically to whole life.
Is no-exam term life insurance reliable?
It can be legitimate coverage, but no-exam does not mean no underwriting. The insurer may use prescription databases, medical records, MIB data, driving records, and other information, and may later require an exam. Compare the policy’s price, coverage limit, exclusions, issue process, and conversion rights rather than choosing solely because an exam is not initially required.
Can smokers get term life insurance?
Yes, smokers can often qualify, but premiums are usually higher and the definition of tobacco use varies. Ask how the insurer treats cigarettes, cigars, vaping, nicotine replacement, marijuana, and time since quitting. Be accurate: inconsistent or incomplete answers can create problems during underwriting or a claim review.
Can people with pre-existing conditions qualify?
Many people with pre-existing conditions qualify, sometimes at a higher rate or with a different underwriting class. The outcome depends on the diagnosis, date, treatment, medications, control, complications, age, requested coverage, state, and tobacco status. Compare multiple carriers through an independent broker and avoid assuming that one insurer’s decision applies everywhere.
Free tools Windows power users keep installed
One-click scans. No signup required.
Does employer life insurance replace an individual policy?
Not automatically. Employer coverage may be too small, may increase in cost with age, and may end or become expensive when you leave the job. Include it in the needs calculation only to the extent it is reliable, then compare the remaining need with an individual policy that you own and can generally keep when changing jobs.
Is the life-insurance death benefit taxable?
The death benefit is generally income-tax-free to the beneficiary, but ownership, transfer-for-value, estate-tax, and other circumstances can change the result. Consult a qualified tax or estate professional for a large policy, business arrangement, trust, or unusual ownership structure.
What happens if I miss a premium?
Most policies provide a contract-specific grace period, but coverage can lapse if the premium is not paid within the required period. Check the policy for the grace period, reinstatement rules, interest, and evidence of insurability requirements. Contact the insurer promptly rather than assuming a late payment is harmless.
Can I cancel or replace a term-life policy?
You can generally cancel, but do not cancel existing coverage until replacement coverage has been issued, accepted, delivered, and reviewed during any applicable free-look period. Replacing a policy can reset contestability and suicide provisions, create new underwriting risk, remove conversion rights, or raise the premium because you are older.
What if an insurer declines my application?
Ask whether the decision was a decline, postponement, or request for more information and whether inaccurate medical or MIB data contributed. Correct factual errors, then work with an independent broker to identify carriers with different underwriting approaches. Keep current coverage active and consider adjusting the amount or term only after understanding the trade-offs.
Quick Recap
The Bottom Line
The best term-life company is the one that offers an affordable, appropriate policy for your specific need—and still gives you useful options if your health, job, family, or finances change. Start with Pacific Life for a broad all-around comparison; Banner or Protective for unusually long terms; Guardian for certain health situations; New York Life for annual renewal and agent help; USAA for military households; and Thrivent for conversion flexibility if you meet its eligibility rules. Then compare at least three offers using the same assumptions, verify the legal issuer and state form, and do not replace existing coverage until the new policy is fully active.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




