Some links on this page are affiliate links: if you buy through them we may earn a commission, at no extra cost to you.
Katie Haun’s case for stablecoins is that a dollar-backed token can move like internet data: across borders, at any hour, and on programmable blockchain networks. That could help people and businesses poorly served by conventional payment systems. But a growing market is not proof that every token is safe, payments are always cheaper, or users capture the value. Since the GENIUS Act became U.S. law in July 2025, the central question has shifted from whether Washington will set rules to how those rules, reserve economics and consumer protections shape a new layer of private money.
From a 2018 debate to a digital-dollar thesis
In 2018, Katie Haun debated economist Paul Krugman in Mexico City about cryptocurrency. As TechCrunch later recounted, Haun steered attention toward a less volatile possibility than Bitcoin: digital tokens designed to hold the value of a dollar. Her interest was not simply in crypto prices. It was in whether a digital dollar could travel through a new payment infrastructure.
Haun came to the subject as a former federal prosecutor who worked on financial crime and helped establish a cryptocurrency-focused government task force. She then moved into venture capital, becoming the first female partner at Andreessen Horowitz and co-leading its crypto funds. In 2022 she left to establish Haun Ventures, an investment firm focused on crypto and related technologies.
That background informs her public argument. Haun has argued that public blockchains can make transactions more traceable than cash and that clear rules can distinguish compliant, well-backed issuers from riskier projects. Those are her positions, not guarantees: blockchain addresses are often pseudonymous, and enforcement still depends on issuer controls, exchanges, analytics, sanctions systems and cooperation across jurisdictions.
#1 Best Overall

- Effortlessly build your crypto portfolio via the all in one Ledger Wallet app: buy, sell, send, receive, swap, stake and more across popular blockchains. 15,000+ coins & tokens in a single dashboard. Keep a close eye on the market. Compare service providers. Track performance. Get timely alerts. Build your portfolio with confidence.
- Effortlessly build your crypto portfolio via the all in one Ledger Wallet app: buy, sell, send, receive, swap, stake and more across popular blockchains. 15,000+ coins & tokens in a single dashboard. Keep a close eye on the market. Compare service providers. Track performance. Get timely alerts. Build your portfolio with confidence.
- Enjoy Bluetooth connectivity, iOS access, and hours of battery use with this mobile-first, secure backup signer. Freedom you can depend on.
- Genuine Check: confirm your signer is authentic during setup with the Ledger Wallet app.
- Protect your signer: keep it in mint condition at all times with a bespoke Pod or Case to avoid scratches and everyday wear and tear.
What a stablecoin is—and what the name does not promise
A stablecoin is a digital token designed to keep a steady value relative to an asset, most often the U.S. dollar. A fiat-backed payment stablecoin is generally issued against reserves such as dollars, bank deposits or short-term government securities. Holders transfer tokens on a blockchain rather than moving a conventional bank payment through the same rails.
“Stable” describes the target price, not a guarantee. The token can trade below a dollar, redemption can be delayed or restricted, and a holder may be unable to access reserves directly. Stablecoins are also not a single uniform category:
- Fiat-backed tokens, such as USDC and USDT, depend on an issuer and the quality, liquidity and accessibility of its reserves.
- Crypto-collateralized tokens rely on digital assets as backing, often with collateral exceeding the tokens issued. Their resilience depends on collateral values, liquidation mechanisms and market liquidity.
- Algorithmic or inadequately collateralized designs rely partly on market incentives or mechanisms rather than robust liquid reserves. They can fail abruptly when confidence and market conditions turn against them.
- Tokenized deposits and money-market products may also represent dollars on a blockchain, but they are not automatically legally or economically equivalent to payment stablecoins.
So the useful comparison is not simply “stablecoin versus crypto.” A dollar token is closer to a privately issued payment claim or settlement instrument than to a volatile asset such as Bitcoin. That does not make it the same as a bank deposit or a government-backed dollar.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Why Haun thinks the U.S. experience can mislead
For a U.S. consumer with a bank account, card, payment apps and a relatively stable currency, the need for a digital dollar may be hard to see. Haun’s strongest case is that this experience is not universal. In countries where local currencies lose purchasing power, banking access is limited, or international transfers are expensive, a dollar-linked token may offer a way to hold and move dollar value using a phone and an internet connection.
That potential should be tested at the point where a person actually uses the money. A token may need to be bought through an exchange or intermediary, transferred over a supported network, screened for compliance, and converted into local currency before the recipient can spend it. Network fees, exchange spreads, provider charges, cash-out costs and local availability all affect the result. A token can remain stable against the U.S. dollar while still failing to preserve purchasing power against local inflation, and access can be limited by law or provider policy.
Stablecoins may also be useful to businesses that need to move dollars across borders or between entities outside banking hours. They can enable near-real-time transfers, programmable payments and settlement on a 24/7 network. But a blockchain fee alone is not the cost of the transaction. A fair comparison includes the full path from source currency to purchase or minting, transfer, compliance review, redemption or exchange, foreign-exchange conversion and recipient access. The Bank for International Settlements cautions that lower costs and faster payments are not guaranteed in every case.
Rank #2

- Proven security at scale: Over 9 years and millions of cards issued with no known remote hacks, while military‑grade EAL6+ security keeps your private keys locked inside the chip. Your cryptocurrencies stay strongly protected from online attackers.
- Tap once to manage your entire crypto wallet across 90 blockchains - no USB cables or Bluetooth, no batteries, no setup. Access 14,100+ coins & tokens, DeFi, NFTs, and staking instantly from your phone
- Smart backup: Use your second Tangem Wallet as your Backup keys with end‑to‑end encryption; no more papers, pictures. If one card is lost, the remaining can still restore full access, with an optional seed phrase available for advanced users.
- Engineered to last up to 25 years: Waterproof (IP69K), shockproof and tested for extreme temperatures from −25°C to 50°C. A durable cold wallet with long‑term protection and independently audited security.
- Trusted by 6 million users worldwide (4.9 App Store, 4.8 Google Play) - buy, sell, swap, stake, and spend cryptocurrency directly. The secure offline storage wallet designed for how people actually use crypto wallets
The use cases are uneven. Cross-border business transfers and remittances may benefit where conventional intermediaries are costly or slow, but compliance and local cash-out remain hurdles. Crypto trading already uses stablecoins for settlement and collateral, though that activity is largely internal to the digital-asset ecosystem. Merchant payments face adoption, tax and reporting questions. On-chain lending can make tokens composable as collateral, but brings smart-contract and liquidation risk. Tokenized assets may support new settlement arrangements, but they do not remove securities rules, eligibility limits or the need for genuine liquidity.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteTechCrunch reported in 2025 that companies including Walmart, Amazon, Uber, Apple and Airbnb were exploring stablecoin applications. That reporting is not evidence that each company launched a production service or that consumers can now pay those businesses with stablecoins. Exploration, pilots and live payment products are different stages.
A large market is not the same as widespread payment use
Stablecoins have moved from a niche crypto instrument toward a significant digital-dollar market. Federal Reserve researchers estimated aggregate stablecoin market capitalization at about $317 billion on April 6, 2026; the BIS put it at roughly $320 billion at the end of May 2026. These estimates are snapshots from different dates, not measures of the same day’s activity.
Market capitalization tells readers how much value is represented by outstanding tokens at a point in time. It does not establish how many people use them for ordinary purchases, how much of reported transaction volume reflects economic payments rather than trading or internal transfers, or whether transfers are cheaper after all fees. The market remains far smaller than the U.S. banking deposit system and concentrated in dollar-linked instruments. The growth supports Haun’s claim that digital dollars matter; it does not prove they will replace banks or payment networks.
Her broader thesis is that stablecoins can be an initial building block for tokenized financial assets, from money-market funds and private credit to real estate and equities. Tokenized claims could, in principle, settle on shared digital infrastructure and move outside traditional business hours. That remains a forward-looking investment thesis, not a settled consumer reality. As Haun has reportedly cautioned, a technology can be inevitable without being imminent.
Haun Ventures has a stake in the outcome
Haun’s advocacy is also an investment thesis. Haun Ventures describes digital assets, stablecoins and instant cross-border payments as part of the infrastructure for a broader digital economy. The firm launched in 2022 with more than $1.5 billion in assets under management, according to the 2025 TechCrunch profile; that historical figure should not be mistaken for a current total. On May 4, 2026, the firm announced $1 billion in new funds in its Fund II announcement.
Rank #3
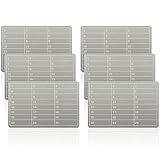
- Sturdy Structure: This metal seed phrase plate is constructed from stainless steel, featuring corrosion resistance, waterproof property, shockproof performance and anti hacker function for crypto wallet, its melting point exceeds 2500 degrees Fahrenheit, which can be applied for long term cryptocurrency private information storage and cold backup use
- Complete Package: the package contains 6 pieces of metal seed phrase plates and matching lock screws for crypto seed phrase storage, each plate measures about 50 x 90 mm/1.97 x 3.54 inches, 5.7 mm/0.22 inch row spacing leaves ample space for letter engraving on plate
- Bip39 Compatibility: the password stamp design of plate matches bip39 vocabulary, which supports 12 or 24 word seeds in languages, ideal for private cryptocurrency information storage and offline cold storage system matching ledger crypto wallet
- Wide Application Scope:This stainless steel cold storage plate fits bip39 wallets and mainstream hardware wallets, which supports up to 24 mnemonic phrases for crypto seed phrase storage, covering multiple cryptocurrency storage scenarios with stable matching performance
- Multi purpose Function:Besides recording bitcoin seed phrases via crypto wallet, this metal seed phrase plate can be applied to store important passwords, key dates and time information, expanding daily data storage functions beyond cryptocurrency backup
This does not invalidate Haun’s arguments, but it is relevant context. If stablecoin adoption expands, companies working on issuance, payments, wallets, exchanges, compliance or tokenized assets may benefit. The questions for readers are concrete: which parts of the ecosystem does the firm back, how do those businesses earn revenue, and do their incentives align with lower costs and better protections for users? A venture investor may favor a regulatory framework that improves trust and makes institutional adoption easier, while also benefiting from the sector’s growth.
What the GENIUS Act changed—and what it did not
The GENIUS Act was signed into U.S. law in July 2025, so it is no longer awaiting congressional passage. It establishes a framework for covered payment stablecoins. Among its central requirements, covered issuers must hold at least one dollar in permitted reserves for each dollar of covered stablecoin obligations. Permitted reserve categories include U.S. dollars, Federal Reserve notes, certain funds at insured or regulated depository institutions, short-term Treasury securities, Treasury-backed reverse repurchase agreements and certain money-market funds. The White House summary of the law’s reserve and yield provisions provides further context.
The law does not turn every dollar-denominated token into a regulated payment stablecoin. Nor does authorization mean that a token is an FDIC-insured bank deposit or that government guarantees a holder against every loss. The exact issuer, product, reserve arrangements, redemption terms and applicable rules still matter. The law’s treatment of yield is also consequential: reserve income earned by an issuer is not automatically interest paid to token holders. A yield-bearing token, a tokenized Treasury or money-market product, a deposit account and a payment stablecoin are distinct products, with different risks, rights and regulatory treatment.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Clearer reserve requirements can address some concerns about backing, but rules do not eliminate operational failures, runs, fraud, weak controls or uncertainty over access to redemption. The policy debate has therefore moved toward implementation and market structure: which issuers qualify, how they are supervised, what disclosures users receive and how consumer protections compare with those for familiar payment methods.
The strongest objections to the digital-dollar case
Reserve quality and redemption
A stablecoin’s ability to hold its peg depends on more than a statement that it is backed. The important questions are what assets the issuer holds, how liquid they remain under stress, whether users can redeem at par, who is eligible to redeem, how quickly redemption happens and whether disclosures are timely and independently checked. A reserve may be sufficient on paper yet difficult to turn into cash quickly during a wave of redemptions.
Run risk
Holders often expect to redeem at or near face value, while reserves may include assets that are not instantly available in the same form. If users lose confidence in reserves, custody or redemption access, they may rush to exit together. Federal Reserve Governor Michael Barr has warned that stablecoins lack deposit insurance and that reserve incentives can matter to their safety. The Federal Reserve’s 2026 analysis notes that safer, more liquid reserves have been associated with stronger adoption, while growth can increase links between digital assets and traditional finance.
Rank #4

- Sturdy Structure: This metal seed phrase plate is constructed from stainless steel, featuring corrosion resistance, waterproof property, shockproof performance and anti hacker function for crypto wallet, its melting point exceeds 2500 degrees Fahrenheit, which can be applied for long term cryptocurrency private information storage and cold backup use
- Complete Package: the package contains 6 pieces of metal seed phrase plates and matching lock screws for crypto seed phrase storage, each plate measures about 50 x 90 mm/1.97 x 3.54 inches, 5.7 mm/0.22 inch row spacing leaves ample space for letter engraving on plate
- Bip39 Compatibility: the password stamp design of plate matches bip39 vocabulary, which supports 12 or 24 word seeds in languages, ideal for private cryptocurrency information storage and offline cold storage system matching ledger crypto wallet
- Wide Application Scope:This stainless steel cold storage plate fits bip39 wallets and mainstream hardware wallets, which supports up to 24 mnemonic phrases for crypto seed phrase storage, covering multiple cryptocurrency storage scenarios with stable matching performance
- Multi purpose Function:Besides recording bitcoin seed phrases via crypto wallet, this metal seed phrase plate can be applied to store important passwords, key dates and time information, expanding daily data storage functions beyond cryptocurrency backup
Consumer protections and irreversibility
Stablecoin transfers can be difficult or impossible to reverse. A lost private key, phishing attack, wallet drain or transfer to the wrong network can leave a user with little practical recourse. Addresses may be frozen, accounts closed, exchanges become insolvent and redemptions delayed. A regulated issuer does not by itself give users the same fraud or unauthorized-transfer protections they may expect from a conventional payment instrument. Barr’s remarks on stablecoin risks discuss these distinctions. Users must also account for smart-contract vulnerabilities, geography-based restrictions and the possibility that an intermediary—not the token protocol—controls their access.
Free tools Windows power users keep installed
One-click scans. No signup required.
Traceability does not solve illicit finance
Public blockchains can leave transaction records that investigators may analyze, which is the basis for Haun’s argument that digital-asset flows can be more traceable than cash. But a visible ledger does not identify every person behind an address or prevent crime. Funds can move through pseudonymous addresses, mixers, multiple chains and offshore or unregulated services. Effective oversight still relies on compliance by issuers and intermediaries, investigative capacity and cross-border enforcement.
Banking, monetary sovereignty and concentration
If people or businesses shift funds from bank deposits to stablecoins, banks could face changes in their funding base and lending capacity. The scale and effects depend on adoption and product design; stablecoins remain small relative to bank deposits. At the same time, dollar-linked tokens can extend the dollar’s reach, including in countries whose authorities may prefer residents to use local currency. The BIS has highlighted financial-integrity and stability challenges as stablecoins connect more closely with traditional finance.
There is also a concentration problem. A system marketed as open or decentralized may rely on a small number of issuers, reserve banks, custodians, exchanges, blockchains and compliance providers. Those firms can influence who can access the system, which transfers are frozen and how quickly users can exit. Federal Reserve officials have raised concerns about mixing bank-like activity with commerce and about potential competitive distortions. Replacing one set of intermediaries with another does not necessarily make money more competitive or resilient.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Who earns the return on the reserves?
Reserve economics are central to the argument over stablecoin yield. When an issuer holds Treasury securities or other interest-bearing assets, the reserves can generate income. In a non-yield-bearing payment token, that income may flow chiefly to the issuer and its distribution partners rather than to ordinary holders. Haun has questioned why users should not receive something closer to the return available on savings.
Recommended Free Tools
But paying yield changes the product and its incentives. It can make a token more attractive to hold, but it may also affect how funds move from bank deposits, how issuers compete and what investment-product rules apply. A payment stablecoin is not automatically a savings account; a tokenized money-market product is not automatically a deposit; and a yield-bearing token is not necessarily a cash equivalent. Readers should ask who owes the payment, what assets support it, whether the return can change, what redemption rights apply and what protections are absent.
Best Value

- Unparalleled Security: Protect your assets NDA-free EAL 6+ Secure Element, offering robust defense and complete transparency
- Simple & Secure Interface: Manage your digital assets easily with a clear OLED screen for secure on-device confirmations
- Supports 1000s of Coins & Tokens: Securely handle thousands of assets, including Bitcoin, Ethereum, and more, all in one wallet
- Effortless Asset Management: Monitor and transact seamlessly with Trezor Suite, our intuitive desktop and mobile app
- Enhanced Backup Solution: Rest assured with Multi-share Backup, eliminating single points of failure for secure cold wallet recovery
The trade-off is structural: users may want higher returns and immediate liquidity, while supervisors may prioritize safe, liquid reserves. Issuers and distributors have incentives to grow balances and earn revenue. Reserve rules can limit risk-taking, but they cannot make every business incentive identical to a user’s interests.
When might stablecoins make sense?
Stablecoins are not a general-purpose recommendation for savings or everyday spending. They may be worth evaluating for an internationally active business with recurring cross-border settlement, a developer building a payment application, or a user who has a lawful and reliable way to obtain and redeem dollar tokens where conventional options are limited. For a U.S. consumer already served by a bank and payment apps, the added benefit may be modest unless a specific service works better on-chain.
Before using one, an individual should check:
- Issuer and reserves: What backs the token, how often are reserves disclosed, and who verifies them?
- Redemption: Can you redeem directly at par, or only through an exchange or approved intermediary? Are there fees, minimums or geographic limits?
- Custody: Will a company hold the token for you, or will you manage your own keys? Self-custody removes some intermediary dependence but makes key loss and transaction mistakes your responsibility.
- Network and exit: Which blockchain is supported, what could a transfer cost, and can you reliably convert to a bank balance or local currency?
- Legal and tax treatment: Is the product available and lawful where you live, and what records must you keep?
- Security and recourse: What happens after fraud, a frozen address, an incorrect transfer or a provider failure?
Businesses should calculate the full settlement cost, not compare a network fee with a wire fee in isolation. They should also review sanctions and identity screening, treasury controls, accounting, refunds and chargebacks, customer demand, provider responsibility if funds are frozen, integration requirements and recovery procedures for wrong-network transfers. A business that cannot explain its redemption and failure plan should not treat a blockchain transfer as a routine payment upgrade.
The verdict: important infrastructure, not a universal cure
Haun’s most persuasive claim is not that stablecoins will replace banks, cash or cards. It is that dollar claims which can move around the clock on programmable networks are becoming an important form of financial infrastructure, particularly for cross-border and on-chain activity. The market’s growth and the arrival of a U.S. legal framework make that argument harder to dismiss than it was in 2018.
Whether the infrastructure benefits the public depends on what happens next: how safe and transparent reserves are, who can redeem, how competition develops, what users pay at every step, and whether consumer protections keep pace. A digital dollar can be useful without being insured, risk-free or better for every user. Haun is both an advocate and an investor in the ecosystem; readers should take the potential seriously while scrutinizing who controls the rails and who captures the yield.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.



