Free tools Windows power users keep installed
One-click scans. No signup required.
Some links on this page are affiliate links: if you buy through them we may earn a commission, at no extra cost to you.
Square is the best starting point for many small U.S. businesses, Stripe is strongest for online and custom payments, Helcim is a leading transparent interchange-plus option, PayPal is best for familiar wallet checkout, Chase Payment Solutions suits businesses wanting bank integration, and Stax is worth evaluating at consistently high volume.
There is no universally cheapest payment processor. Your best choice depends on average transaction size, card-present versus online sales, monthly volume, payment methods, software needs, payout preferences, and tolerance for subscriptions or contracts. The pricing and availability below are U.S.-specific starting points and should be confirmed before signing up.
Quick verdict
| Provider | Best for | Why consider it | Main caution |
|---|---|---|---|
| Square | Small retailers, restaurants, salons, mobile and service businesses | Easy all-in-one POS and payments | Flat-rate pricing can become expensive at higher volume |
| Stripe | Online businesses, SaaS, marketplaces and custom apps | Powerful developer platform and broad payment infrastructure | Requires more technical setup |
| Helcim | Cost-conscious established merchants | Published interchange-plus pricing with volume tiers | More complex statements and fewer universal integrations |
| PayPal | Ecommerce businesses | Recognizable PayPal and Venmo checkout | Wallet transactions can cost more than ordinary cards |
| Chase Payment Solutions | Chase customers and traditional merchant-service buyers | Bank integration and potentially fast Chase funding | Some products may include monthly fees |
| Stax | Higher-volume, consistent merchants | Subscription-style interchange-plus economics | Can be poor value at low or seasonal volume |
These are “best for” recommendations rather than a single numerical ranking. A provider with a higher published rate may still produce a lower total cost if it replaces separate POS, invoicing, appointment, inventory or subscription software.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWhat is a payment processor?
A payment processor handles the authorization, routing and settlement of a transaction. In everyday business conversations, “processor” may also refer to several related pieces:
#1 Best Overall

- With Square Terminal, you can ring up sales, accept payments, and print receipts, all with one device. Use it at the counter or ring up customers anywhere in your store.
- Accept all major credit and debit cards and pay one low rate with no hidden fees and no long-term contracts.
- Process chip cards in just two seconds.
- Get your money as soon as the next business day.
- Use it cordlessly with the built-in battery, designed to last all day.
- Payment gateway: Technology that securely transmits online payment information.
- Merchant account: The underwriting and account relationship used to receive card funds.
- Payment facilitator or aggregator: A platform such as Square, Stripe or PayPal that onboards businesses through its broader payments infrastructure.
- POS system: Hardware and software used to sell, track inventory, manage staff and accept payments.
Square combines many of these functions in an operating system for small businesses. Stripe emphasizes programmable online payments. PayPal emphasizes its consumer wallet. Traditional providers such as Chase may combine merchant services with a banking relationship.
How payment processing fees work
The advertised rate is only one part of the cost. A realistic comparison includes:
- A percentage of each transaction.
- A fixed per-transaction charge.
- Underlying card-network and interchange costs.
- Monthly software, subscription or account fees.
- Gateway, PCI, batch or compliance charges.
- Hardware purchase, rental or replacement costs.
- Chargeback and dispute fees.
- ACH, wallet, international, currency-conversion and instant-payout fees.
- Contract, cancellation or minimum-volume obligations.
Why the fixed fee matters
At a rate of 2.9% + 30¢, a $10 transaction has a nominal processing charge of 5.9%; a $100 transaction has a 3.2% charge; and a $1,000 transaction has a 2.93% charge. This is a mathematical illustration, not an estimate of total effective cost.
Flat-rate versus interchange-plus
Flat-rate pricing is easier to understand and often suits new businesses, unpredictable volume and owners who value simple statements. Its drawback is that it can be expensive at higher volume or with a favorable debit and card mix.
Interchange-plus pricing separates card-network costs from the processor’s markup. It can be more economical and transparent for established merchants, but the final cost varies by card type, rewards program, industry, transaction method and qualification. A quoted margin is not an all-in rate.
Do not compare a rate such as 2.6% + 10¢ directly with “interchange + 0.40% + 8¢” without estimating the underlying interchange and network costs.
1. Square: best overall for many small businesses
Best for: Retailers, restaurants, salons, appointment-based businesses, contractors, market vendors and other businesses that want payments plus basic operating software.
Square supports in-person payments, online checkout, invoices, payment links, virtual terminals and Tap to Pay. Businesses can begin without buying hardware and add readers, terminals or registers later.
Rank #2

- Get your money as soon as the next business day.
- Get set up quickly with no long-term commitments. Download the Square Point of Sale app for free, create an account, and start taking payments anywhere.
- Run your business all in one place with the free Square Point of Sale app. Track your sales, manage inventory, accept tips, send receipts digitally, and more.
- Works with Apple devices with a Lightning connector.
Published U.S. pricing signals
- In-person tap, dip or swipe: 2.6% + 15¢ on the Free plan.
- Online card payments or invoices: 3.3% + 30¢ on the Free plan.
- Online API payments: 2.9% + 30¢.
- Manually entered or card-on-file transactions: 3.5% + 15¢.
- ACH through invoices: 1%, with a $1 minimum and $10 cap on applicable plans.
- Custom processing pricing may be available above $250,000 in annual processing.
See Square’s current fee schedule for plan-specific conditions.
Strengths and weaknesses
Square’s main advantage is low setup friction. Its POS ecosystem can include inventory, appointments, staff permissions, invoicing, loyalty and reporting. It is particularly useful when a business wants to avoid assembling separate payment, POS and invoicing systems.
The trade-off is that flat-rate pricing may cost more as volume grows. Keyed and card-on-file transactions cost more than properly captured card-present payments. Complex subscriptions, marketplaces, authorization logic or unusual risk profiles may require another platform.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problems2. Stripe: best for online businesses and custom integrations
Best for: SaaS, ecommerce, subscriptions, marketplaces, startups and businesses with developers or a technical implementation partner.
Stripe offers hosted and embedded checkout, payment links, APIs, webhooks, subscriptions, Billing, Tax, fraud tools and marketplace capabilities. Stripe says its platform supports more than 100 payment methods, 135 currencies and customers in 195 countries, subject to product, country and account availability. See Stripe Payments for current scope.
Published U.S. pricing signal
Stripe lists 2.9% + 30¢ per successful domestic card transaction as standard pricing. Custom pricing, interchange-plus options, volume discounts and multi-product discounts may be available for larger or more complex businesses. See Stripe’s pricing page.
Stripe is compelling when payment functionality is part of the product itself. APIs and webhooks support recurring, usage-based and marketplace-style models. It is less convenient for a nontechnical local business that primarily needs a register, inventory and employee-management system.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Evaluate international, currency-conversion, dispute, alternative-payment and instant-payout fees separately. API access also does not eliminate underwriting reviews, reserves or payout restrictions.
Rank #3
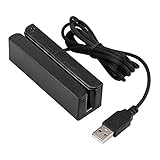
- MSR90 is a USB emulation keyboard interface that not need any driver or software,USB simply plug and play
- Reads up to 3 tracks of information,can reads ISO7811, AAMVA, CA DMV and most other card data formats
- Threaded inserts for mounting. LED indicator, green light is on when connecting,green light blinks when cards swiped
- Bi-directional swipe reading, superior reading of high jitter, scratched, and worn magstripe cards, reliable for over 1,000,000 card swipes
- Configuration software makes configuration changes easy,works with: Windows OS and Mac OS
3. Helcim: best for transparent interchange-plus pricing
Best for: Established small and midsize merchants who want cost-plus pricing without a conventional monthly subscription.
Helcim says its merchants receive interchange-plus pricing. The processor passes through interchange and network costs, then adds a margin that declines across five tiers based on a three-month rolling average. Its published U.S. margins are:
| Monthly card volume | Card-present margin | Card-not-present margin |
|---|---|---|
| $0–$50,000 | 0.40% + 8¢ | 0.50% + 25¢ |
| $50,001–$100,000 | 0.35% + 7¢ | 0.45% + 20¢ |
| $100,001–$500,000 | 0.25% + 7¢ | 0.35% + 20¢ |
| $500,001–$1,000,000 | 0.20% + 6¢ | 0.25% + 15¢ |
| $1,000,001+ | 0.15% + 6¢ | 0.15% + 15¢ |
These are processor margins, not total rates. Interchange and network assessments still vary by card, channel and industry. Helcim also publishes ACH pricing of 0.5% + 25¢, capped at $6 for approved transactions below $25,000; a $15 chargeback fee refunded when the merchant wins; a $199 card reader; and a $349 smart terminal. Details are available in Helcim’s U.S. fee disclosures.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Helcim can be attractive when volume makes cost-plus economics meaningful. It is less ideal for merchants who need the largest developer ecosystem, have very small tickets, or prefer a single simple blended rate.
4. PayPal: best for familiar online wallet checkout
Best for: Ecommerce businesses that want customers to use PayPal or Venmo alongside cards.
PayPal can be deployed for online checkout, invoices and payment links, with some in-person and Tap to Pay options. Its published U.S. starting signals include:
- Card processing: 2.89% + 29¢.
- PayPal and Venmo payments: 3.49% + 49¢.
- Tap to Pay and POS: starting at 2.29% + 9¢.
See PayPal’s business fee page; rates and eligibility vary by transaction type.
PayPal may improve checkout familiarity and confidence because customers may already have credentials. However, wallet payments can cost more than standard card payments. PayPal may be most useful as an additional checkout option rather than the only processor for every channel. Review account-review, reserve, dispute and payout terms before routing all business cash flow through it.
Rank #4
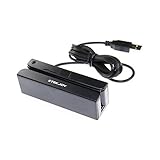
- USB interface, keyboard emulation, no need to install software to read, configuration software for changing settings available.
- Read data from all 3 tracks, high and low coercivity cards, ISO7811, AAMVA, CA DMV and most magnetic card data formats.
- Work on Windows, Mac and other USB capable systems. Work with TXT, notepad, Word, Excel, POS systems and son on.
- Compact size, with 145cm USB cord, two 3mm-diameter screw holes for fixing at the bottom, a LED indicator light
- Perfect for POS, Banking, Loyalty, Access Control, ID verification and other applications.
5. Chase Payment Solutions: best for bank integration
Best for: Existing Chase business customers and merchants who value a traditional financial-services relationship or potentially fast funding into Chase accounts.
Chase publishes these U.S. starting rates:
- Tap, dip or swipe: 2.6% + 10¢.
- Manually keyed transactions or payment links: 3.5% + 10¢.
- Ecommerce: 2.9% + 25¢.
Monthly fees may apply to certain products and pricing plans. Custom pricing, including interchange-rate options, may be available. Chase says eligible merchants may receive funds the same day at no additional cost when funds are directed to an eligible Chase business checking account, depending on the solution and setup. Verify the details at Chase’s merchant-fee page.
Chase can accept major cards and wallets, including Visa, Mastercard, American Express, Discover, JCB, Apple Pay and Google Pay. The trade-off is that onboarding may involve a payment advisor rather than being completely self-serve, and headline rates may not include hardware, software, gateway or special-method fees.
6. Stax: best for higher-volume subscription-style pricing
Best for: Established merchants with consistent volume, larger average tickets and enough monthly processing to justify a subscription.
Stax is positioned as an interchange-plus provider with a monthly subscription rather than a purely blended flat-rate model. That structure can outperform flat-rate pricing when processing savings exceed the subscription and other fees.
Do not rely on a generic Stax price or markup. Request a current written quote showing the monthly subscription, processor markup, per-transaction fee, gateway costs, PCI fees, chargeback fees, equipment costs, contract term, cancellation charges and any annual or regulatory fees. Exact pricing is quote-dependent and should be confirmed directly through Stax.
Stax is usually a poor fit for low-volume, newly launched or seasonal businesses unless the subscription can be paused and the savings remain meaningful during slow months.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Side-by-side pricing signals
| Provider | In-person | Online or keyed | ACH / wallet signal | Pricing model |
|---|---|---|---|---|
| Square | 2.6% + 15¢ | 3.3% + 30¢ online; 3.5% + 15¢ keyed/card-on-file | ACH invoice: 1%, $1 minimum, $10 cap on applicable plans | Flat-rate; Free and paid plans |
| Stripe | Depends on product | 2.9% + 30¢ domestic cards | Varies by method | Flat-rate; custom options |
| Helcim | Interchange + 0.40% + 8¢ at lowest tier | Interchange + 0.50% + 25¢ at lowest tier | ACH: 0.5% + 25¢, $6 cap under stated conditions | Interchange-plus; volume tiers |
| PayPal | Tap to Pay/POS from 2.29% + 9¢ | Cards from 2.89% + 29¢ | PayPal/Venmo: 3.49% + 49¢ | Method-specific flat rates |
| Chase | 2.6% + 10¢ | 3.5% + 10¢ keyed; 2.9% + 25¢ ecommerce | Wallet support; other fees vary | Flat-rate and custom options |
| Stax | Quote-based | Quote-based | Quote-based | Subscription plus interchange-plus |
Published figures are starting or advertised signals, not guaranteed effective rates. Hardware, software, card mix, chargebacks, international payments and plan eligibility can change the total.
Best Value

- Pay one transparent rate per swipe for Visa, Mastercard, Discover and American Express.
- Works in conjunction with most downloadable Square point-of-sale apps on your device. Customers can pay, tip and sign directly on your device. Track payments in cash, gift cards and more. Also lets you send receipts via e-mail or text message, makes it easy to apply discounts, keeps a data and sales history log and more.
- Accepts magstripe credit card payments, including those from Visa, Mastercard, Discover and American Express (fees apply).
- App sends deposits to your bank account within 1 to 2 business days, or enjoy instant deposits (fees apply).
Best provider by business type
- Retail store: Square or Chase; consider Helcim at higher volume.
- Restaurant: Square if its restaurant tools fit; compare Chase or a specialized provider for customized service.
- Salon or appointment business: Square.
- Mobile contractor or market vendor: Square or Chase Tap to Pay.
- Online store: Stripe or PayPal; Square is practical if you already use its POS.
- SaaS or subscription business: Stripe.
- Marketplace or platform: Stripe Connect or a specialized platform-payments provider, not a basic POS.
- B2B invoice-heavy business: Compare Helcim, Stripe and Square, especially their ACH terms.
- High-volume established merchant: Obtain quotes from Helcim, Stax, Chase and providers offering negotiated pricing.
- International ecommerce: Stripe is the strongest general candidate in this shortlist, but verify country availability, local methods, currencies and cross-border costs.
How to calculate your real cost
Use this monthly framework:
Monthly processing cost = percentage fees
+ per-transaction fees
+ monthly software or subscription fees
+ gateway, ACH, wallet and international fees
+ chargeback and dispute fees
+ hardware cost allocated over its useful life
+ contract or compliance fees
For each candidate, estimate monthly volume, transaction count, average ticket, card-present percentage, online percentage, keyed or card-on-file percentage, ACH share, wallet share, monthly software cost, hardware cost, chargebacks and international sales.
For example, a business processing $20,000 across 2,000 $10 transactions will feel fixed fees much more heavily than a business processing the same $20,000 across 200 $100 transactions. A subscription plan may help a stable, high-volume merchant but hurt a seasonal business during slow months. The correct comparison requires your own transaction mix rather than a universal threshold.
Operational risks to check before switching
Account reviews and payout delays
Aggregated platforms may review an account after signup or a sudden increase in volume. Keep invoices, shipping records, customer communications and proof of delivery. Understand reserves and payout terms, contact underwriting before a predictable seasonal spike, and maintain a backup way to collect urgent payments. This is a general payments-industry risk, not a claim that a specific provider routinely freezes funds.
Chargebacks
Compare the dispute fee, whether it is refunded when you win, evidence-submission tools, fraud controls and the effect of disputes on reserves or account standing. Helcim’s published disclosure lists a $15 chargeback fee and says it is refunded when the merchant prevails.
International sales
Do not use domestic U.S. rates to forecast international costs. Check cross-border fees, currency conversion, settlement currencies, local payment methods, country availability, tax requirements and local acquiring support.
Hardware and outages
Ask about offline payments, cellular backup, replacement times, device compatibility, Tap to Pay fallback, browser-based keyed payments and how deposits resume after an outage. Also check whether hardware is purchased, rented or tied to a contract.
Restricted or higher-risk businesses
Acceptance depends on each provider’s acceptable-use and underwriting policies. Businesses in areas such as supplements, travel, ticketing, financial services, gambling, adult products or other regulated categories should confirm eligibility before migrating volume.
Recommended Free Tools
Common mistakes
- Choosing by percentage alone: Include cents, software and every extra fee.
- Ignoring average ticket size: Fixed fees dominate low-value transactions.
- Missing keyed pricing: Card-not-present and manually entered payments often cost more than chip or tap transactions.
- Assuming no monthly fee means lowest cost: A higher blended rate may replace the subscription.
- Assuming interchange-plus guarantees savings: Card mix and qualification determine the underlying cost.
- Signing an equipment lease without reading it: Check term, cancellation, ownership and replacement obligations.
- Overlooking software value: A higher rate may be rational if it replaces separate POS or scheduling tools.
- Failing to request a complete quote: Ask for monthly minimums, PCI fees, gateway charges, batch fees, annual fees, equipment terms, dispute fees, instant-payout fees and international pricing in writing.
How to choose
Start with the simplest provider that supports your actual sales channels. Choose Square when you want an accessible business operating system; Stripe when payments are part of an online product; PayPal when wallet recognition matters; Helcim or Stax when predictable volume makes interchange-plus worth analyzing; and Chase when bank integration and traditional support are important.
Before committing, compare two or three providers using the same monthly volume, average ticket, channel mix and payment methods. Ask each provider what happens during a volume spike, how disputes are handled, when funds settle, and what fees appear outside the headline rate. The lowest advertised rate is not necessarily the lowest cost—or the safest operational choice—for your business.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.



