Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Some links on this page are affiliate links: if you buy through them we may earn a commission, at no extra cost to you.
Infosys is making artificial intelligence central to its growth strategy, and CEO Salil Parekh says the company’s AI capabilities are helping it win major transformation work. The evidence points to stronger AI adoption and deal momentum—but not yet to a clear AI-led acceleration in company-wide revenue. Infosys grew 3.1% in constant currency in FY26 and guided to 1.5%–3.5% growth in FY27.
What Infosys means when it says AI is driving growth
Infosys is pitching AI as a way to expand consulting, software engineering, data, cloud, business-process transformation and legacy-modernisation work—not simply as a market for chatbots. CEO and managing director Salil Parekh has said the company’s enterprise-AI proposition is helping it compete for large transformation opportunities. He has also described an “AI First value framework” and Topaz Fabric as part of the company’s effort to help clients move from experimentation to enterprise-scale deployment. Parekh’s FY26 earnings-call remarks set out the breadth of that opportunity.
That is a statement about strategy and commercial positioning, not proof that AI alone caused Infosys’ revenue growth. The company’s published results do not isolate a complete, audited figure for how much incremental consolidated revenue came specifically from AI.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteThe six areas in Infosys’ AI opportunity
Parekh grouped Infosys’ AI-services opportunity into six areas. Together, they show why the company treats AI as an extension of its broader enterprise-services business:
#1 Best Overall

- Built for Local AI Development: AMD Ryzen AI Halo is designed for local AI development and inference, featuring 128GB unified memory and support for up to 200B parameter models to build and run intensive AI workloads locally.
- 128GB Unified Memory: Features 128GB LPDDR5x unified memory at 8000 MT/s with 256 GB/s memory bandwidth, providing a shared memory pool across the CPU, GPU, and NPU to support larger AI models.
- AMD Ryzen AI Max+ 395 Processor: Features 16 cores, 32 threads, and Zen 5 architecture, paired with AMD Radeon 8060S integrated graphics featuring 40 RDNA 3.5 compute units and an AMD XDNA 2 NPU with up to 50 TOPS.
- Linux AI Developer Platform: Purpose-built for Linux-based AI development with full AMD ROCm software support and preloaded tools, models, and workflows optimized for local AI development.
- Compact, Connected Design: Includes a 2TB M.2 SSD, 10GbE LAN, Wi-Fi 7, Bluetooth 5.4, USB-C connectivity, and HDMI 2.1b.
- AI strategy and engineering: helping clients identify use cases, design their approach and build or integrate AI applications.
- Data: improving the data foundations, architecture and access that AI systems need.
- Process transformation: redesigning workflows and operations around AI, rather than inserting a model into an unchanged process.
- Legacy modernisation: updating older applications and systems, including the technology estates on which many large organisations still depend.
- Physical AI: applying AI in settings that interact with the physical world, such as industrial or operational environments.
- Trust: addressing governance, security, risk and responsible deployment.
In practice, a client project may combine several of these: for example, a company may need data work, application integration, workflow redesign and security controls before an AI tool is ready for use in a core business process.
Topaz, Topaz Fabric and Cobalt: what they are—and are not
Topaz is Infosys’ portfolio of generative- and agentic-AI services and solutions. Topaz Fabric is described by management as a broader AI framework or toolkit for enterprise delivery. It is not presented in the cited materials as an Infosys foundation model or a single consumer software product. Cobalt is the company’s cloud platform, relevant because enterprise AI typically depends on cloud infrastructure, data, integration, security and modernisation.
The distinction matters: Infosys’ pitch is principally about helping enterprises select, integrate, deploy and operate AI capabilities. Its commercial role may involve a mix of its own frameworks, client systems and third-party technologies. A toolkit or services portfolio is not the same thing as owning the underlying AI models.
How AI can generate revenue for an IT-services company
AI can create billable work at multiple stages. Infosys may advise on strategy and governance, build data foundations, integrate models into applications, modernise older systems, redesign workflows and then help operate the resulting services. It can also cross-sell AI work into existing outsourcing and transformation accounts. When clients consolidate vendors, a provider able to combine consulting, technology implementation, cloud and ongoing operations may have an advantage.
Partnerships are part of this model. Enterprise deployments often require a combination of model providers, cloud platforms, data systems, cybersecurity and industry software. Infosys’ value proposition therefore depends not just on proprietary assets but also on integration capability, industry knowledge and delivery scale. A partnership, by itself, does not establish exclusivity or show that the partner generates material revenue for Infosys.
The same model creates a complication: AI can help clients achieve an outcome with fewer hours of coding, testing, documentation or back-office work. If the provider is paid mainly for labour, a faster or more automated delivery process may reduce billable effort unless the contract’s pricing and scope capture the value created. Productivity is not automatically pricing power.
Rank #2

- EVOLUTION AMD RYZEN AI MAX+ 395 MINI PC - GMKtec EVO-X2 is the next evolution in AI mini PC Ryzen Strix Halo series. Thanks to AMD Simultaneous Multithreading (SMT) the core-count is effectively doubled, to 32 threads. Ryzen AI Max+ 395 has 64 MB of L3 cache and can boost up to 5.1 GHz, depending on the workload. The Ryzen AI Max+ 395 is currently rated as the "most powerful x86 APU" on the market for AI computing.
- AI NPU with XDNA 2 ARCHITECTURE - Powered by 16 “Zen 5” CPU cores, 50+ peak AI TOPS XDNA 2 NPU and a truly massive integrated GPU driven by 40 AMD RDNA 3.5 CUs, the Ryzen AI MAX+ 395 is a transformative upgrade and delivers a significant performance boost over the competition. The Ryzen AI Max+ 395 excels in consumer AI workloads like the llama.cpp-powered application: LM Studio. Shaping up to be the must-have app for client LLM workloads, LM Studio allows users to locally run the latest language model without any technical knowledge required and unleash their creativity and productivity.
- AMD RADEON 8090S iGPU GAMING PC - The AMD Radeon RX 8060S offers all 40 CUs with up to 2.9 GHz graphics clock and uses the new RDNA 3.5 architecture. The powerful iGPU is positioned between an RTX 4060 and 4070 laptop GPU and therefore enables gaming in FHD at maximum details in most demanding games. The 8060S can also utilize the full 64GB pool, which is perfect for running LLMs such as Deepseek 32B, which runs comfortably on this machine.
- EIGHT CHANNEL LPDDR5X - LPDDR5X is a new ground breaking memory small form factor installed on-board. With blazing speeds up to to 8000MT/s, it runs 1.5x faster than the DDR5 SODIMMs; 90% better performance over DDR5 SODIMMs in video conferencing and photo editing; 30% better performance in productivity apps; 4% better performance in digital content workloads.
- QUAD SCREEN 8K DISPLAY SUPPORT - EVO-X2 AI Mini PC support 4-screen 4K/8K output via HDMI 2.1 (8K@60Hz), DisplayPort 1.4 (4K@60Hz), and dual USB 4 40Gbps Transfer speed (supporting PD3.0/DP1.4/DATA). Ideal for gaming, video editing, and multitasking, it provides expansive and crisp multi-display support.
What the reported numbers say
Infosys’ fiscal year runs through March 31. FY26 ended on that date in 2026; FY27 began April 1, 2026. The company reported the following FY26 results and FY27 outlook:
| Measure | Reported figure | What it tells you |
|---|---|---|
| FY26 revenue | ₹178,650 crore ($20.158 billion) | Infosys passed $20 billion in annual revenue. |
| FY26 constant-currency revenue growth | 3.1% | Overall growth remained moderate. |
| FY26 large-deal total contract value (TCV) | $14.9 billion | Indicates contract momentum, not revenue recognised immediately. |
| Net-new share of large deals | 55% | The share management classified as new business. |
| FY26 adjusted operating margin | 21.0% | A measure of operating profitability on the company’s adjusted basis. |
| FY27 revenue-growth guidance | 1.5%–3.5% constant currency | Management’s outlook remains cautious about near-term growth. |
| FY27 operating-margin guidance | 20%–22% | The margin range management expects while continuing to invest. |
These figures come from the FY26 results and guidance filed with the SEC. Management linked its large-deal performance partly to its enterprise-AI proposition and gains in large transformation opportunities. That is relevant evidence of demand and sales positioning, but the $14.9 billion TCV is the value of contracts over their terms, not the amount of AI revenue earned in FY26. Contracts are delivered and recognised over time, and their scope or timing can change.
Infosys’ FY26 annual report says AI-led programmes had been deployed across 90% of its top 200 clients. That is a company-reported deployment statistic, not a measure showing that 90% of those clients’ spending—or Infosys’ revenue—was AI-driven. The annual report does not make deployment breadth equivalent to financial impact.
Management has also disclosed that AI-related work represented approximately 5.5% of revenue in an investor Q&A. That figure is a management disclosure, not a separately reported audited revenue line that establishes how much growth AI added. It should not be read as proof that AI generated 5.5% of incremental revenue. The investor-day Q&A is the source for the approximate figure.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Why the AI growth claim still needs a financial reality check
The clearest caution is the FY27 guidance: 1.5%–3.5% constant-currency revenue growth. That range does not mean AI is failing; it may reflect demand across the whole company, the timing of contract ramps and other business conditions. But it does show that management is not forecasting a company-wide growth breakout in the near term.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Several distinctions help keep the evidence in perspective:
Rank #3
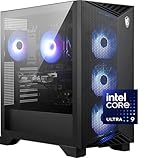
- Intel Core Ultra 9 285 Processor: Newly developed cores deliver ultra-smooth and responsive gameplay. AI accelerators prepare users for the next era of gaming on an AI PC.
- Simplistic Design: Enjoy the latest generation of Windows 11 Home for your everyday needs. *MSI recommends Windows 11 Pro for business use.
- NVIDIA GeForce RTX 5070 Ti GPU
- Cool While Gaming: In conjunction with an RGB CPU Air Cooler, the Aegis RS features four system cooling fans; three in the front and one in the rear to pull in cool air and push heat out of the PC.
- Turn on the Bright Lights: With the built-in RGB lighting, take your gaming experience to the next level by pressing the MSI LED button to cycle through lighting options. Customize lighting even further with MSI Center software.
- Bookings are not revenue. Large-deal TCV is pipeline and contracted work spread over time.
- Adoption is not value. A deployment does not by itself demonstrate client savings, higher sales or improved productivity.
- A pilot is not production scale. Proofs of concept do not establish repeatable, recurring enterprise use.
- AI-related revenue is not necessarily incremental. Some work may be existing cloud, data or outsourcing work relabelled or enhanced with AI.
- Productivity is not automatically profitable growth. Faster delivery can benefit clients, while affecting staffing, pricing and provider margins.
AI may also cannibalise older application-development, testing, support and business-process work. If clients require fewer labour hours, Infosys may need to sell higher-value outcomes, new services or recurring operations to replace revenue that traditional effort-based projects would have generated. The economic result depends on pricing, scope, adoption and whether efficiency gains are shared or retained.
Risks to the strategy
- Revenue quality: Investors need to distinguish new AI demand from existing work described in AI terms.
- Margin pressure: Training, hiring, tools, infrastructure and partnerships cost money; efficiency gains may take time to offset them.
- Client delays: Data constraints, uncertain returns, cybersecurity and regulation can keep promising pilots from reaching production.
- Intense competition: Infosys competes with global consultancies, Indian IT-services firms, cloud providers, software vendors, specialist AI companies and clients’ internal teams.
- Third-party dependence: Model and cloud vendors may control important technology or capture a significant share of the economics.
- Talent and governance: Demand may shift toward experienced architects, domain experts, data engineers and security professionals, while enterprise deployments must address privacy, intellectual property, bias, model errors and accountability.
The CEO transition is a test of continuity
Salil Parekh remains Infosys’ CEO and managing director through March 31, 2027. The board appointed Ashiss Kumar Dash CEO designate on July 23, 2026, with the planned transition effective April 1, 2027, subject to shareholder approval. Dash is therefore the incoming leader, not the current CEO. Infosys’ succession announcement describes his experience across customer-facing businesses, delivery, operations, geographies and sustainability, and notes his focus on growth, innovation and AI-led reimagination.
The transition makes the durability of the AI strategy an important question. Infosys credits Parekh’s tenure with taking revenue from roughly $10 billion to more than $20 billion. Dash has not, in the cited announcement, set out a different AI strategy. The useful test is whether the Topaz and AI First propositions become embedded in the company’s sales, delivery and financial results beyond Parekh’s tenure—not to assume a change before Dash takes office.
What would prove that AI is driving growth?
Investors and business readers should look for evidence that connects AI activity to economic outcomes, rather than relying on announcements alone:
- AI revenue as a share of total revenue, with a clear definition and year-over-year growth.
- AI-related bookings and large deals, separated where possible from broader transformation contracts.
- The number of production deployments and their recurring revenue, rather than only pilots or programmes launched.
- Quantified client outcomes, such as cost savings, productivity gains or additional revenue.
- Changes in revenue per employee, staffing mix, reskilling and operating margins.
- Evidence that AI demand is incremental, repeatable and profitable after implementation costs.
- Whether growth expectations change as FY27 progresses and how the incoming CEO sustains or develops the strategy.
For now, Infosys has credible signs of strategic momentum: a broad AI-services offer, company-reported client deployments and large-deal activity that management says is benefiting from its proposition. But moderate FY26 growth and restrained FY27 guidance mean the stronger claim—that AI is already accelerating company-wide growth—remains unproven in the disclosed financial results.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.



