What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Depreciation spreads the cost of a tangible, long-lived asset over its useful life; accounting amortization spreads the cost of a finite-lived intangible asset over time. In personal finance, “loan amortization” means paying down debt through scheduled payments of principal and interest. The right meaning depends on whether you are looking at an asset or a loan.
Amortization vs. depreciation at a glance
| Term | What it applies to | What is allocated over time? | Typical example |
|---|---|---|---|
| Depreciation | Tangible, long-lived assets | The asset’s cost or depreciable basis | Business equipment |
| Asset amortization | Finite-lived intangible assets | The intangible asset’s cost | A patent or customer relationship |
| Loan amortization | Debt repaid on a schedule | Payments are divided between interest and principal | A fixed-payment mortgage or auto loan |
How depreciation works
Depreciation is an accounting method for allocating the cost of a tangible asset, such as equipment, a vehicle, or a building, over the periods it is expected to help a business operate. It is not necessarily a measure of the asset’s current resale value. Land generally is not depreciated for U.S. federal income-tax purposes.
For book accounting, the amount and timing depend on the asset’s basis, estimated residual value, useful life, and method. Common methods include straight-line, declining-balance, and units-of-production; the method should reflect how the asset’s benefits are consumed under the applicable accounting framework.
Simplified depreciation example
If a business buys equipment for $12,000, expects to use it for four years, and estimates no residual value, straight-line depreciation would be $3,000 per year. This is a simplified book-accounting example, not a tax calculation.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errors#1 Best Overall

- Profitability calculations; cash flow function Calculates NPV and IRR for uneven cash flows
- Time-value-of-money and Amortization keys solve problems including: pension calculations, loans, mortgages, etc.
- Ideal calculator for students, managers and statisticians
- Built-in functionality : List-based one- and two-variable statistics with four regression options: linear, logarithmic, exponential and power
- The BA II Plus calculator is approved for use on the following professional exams: Chartered Financial Analyst exam. GARP Financial Risk Manager (FRM) exam. Certified Management Accountants exam
How asset amortization works
Accounting amortization allocates the cost of a finite-lived intangible asset, such as a patent, copyright, license, or customer relationship, over its estimated useful life. Like depreciation, the expense reduces reported profit and generally reduces the asset’s carrying amount, but the periodic expense is not itself a current cash payment.
Finite-lived intangible assets are generally amortized over their useful lives. Indefinite-lived intangible assets are not routinely amortized under the financial-reporting treatment described in the dossier; they are tested for impairment. Goodwill is generally treated this way for public-company accounting, though specialized private-company and not-for-profit alternatives can differ.
Simplified asset-amortization example
If a company acquires a customer relationship for $60,000 and estimates a five-year useful life with a straight-line pattern, simplified annual amortization would be $12,000. Actual accounting depends on the facts and applicable reporting rules.
Rank #2

- PROFESSIONAL FINANCIAL CALCULATOR : Built-in TVM, IRR, NPV. Engineered for business analysts, real estate investors, accountants, and finance students.
- ADVANCED CASH FLOW & AMORTIZATION : Execute time value of money, break-even analysis, depreciation schedules, and bond pricing. Trusted for professional exam prep", MBA coursework, and banking certifications.
- CATIGA CF-300 : Flip-open hard case with a snap-close design for a secure fit. Compact and portable: designed for daily professional use in office, classroom, or on-site.
- ALL-IN-ONE FOR PROFESSIONALS : From NPV/IRR for real estate analysis to statistical calculations for business analysts. Handles probability, linear regression, and complex financial formulas.
- MORTGAGE, LOAN & INVESTMENT CALCULATOR : Covers bond pricing, loan amortization, investment analysis, and exam-level computations. Your go-to accounting calculator, business calculator, and real estate calculator in one device.
How loan amortization works
With an amortizing loan, each scheduled payment is split between interest and principal. Interest is the cost of borrowing; principal repayment reduces the amount owed. On a typical fixed-payment loan, more of the payment generally goes to interest early in the schedule, while more goes to principal later as the balance falls.
A mortgage’s total monthly payment may also include escrowed property taxes, homeowners insurance, or mortgage insurance. Those amounts can raise the payment but do not reduce the mortgage principal. Some loans do not fully amortize: they may be interest-only, include a balloon payment, or have negative amortization, where unpaid interest causes the balance to grow.
How to read a loan amortization schedule
- Find the scheduled payment and separate principal and interest from any escrowed amounts.
- Check how much of the payment is applied to interest and how much reduces principal.
- Compare the remaining balance with the prior balance to see how much principal was paid down.
- Review the schedule for a balloon payment, interest-only period, or other terms that could prevent the balance from declining as expected.
What the accounting expenses have in common
Depreciation and asset amortization are cost-allocation methods, not direct appraisals of current market value. They typically reduce reported earnings and the related asset’s carrying amount over time. The original purchase or acquisition is when cash may have been paid or financing arranged; recording the periodic expense does not itself mean cash left the business in that period.
Rank #3
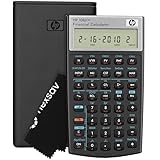
- HP 10BII+ FOR STUDENTS & PROFESSIONALS – This HP calculator is built for business, finance, accounting, and statistics courses. Perfect for learners and professionals who need to solve common financial problems quickly without memorizing formulas or relying on spreadsheets.
- 100+ FUNCTIONS FOR REAL WORLD MATH – Quickly solve time value of money, interest rates, loan payments, NPV, IRR, cash flows, and more. The 10bII+ also includes probability distributions for statistics courses—a feature not often found in financial calculators.
- ALGORITHMIC INPUT WITH DEDICATED KEYS – This high-school/college calculator uses algebraic and chain logic with minimal keystrokes. Layout appears the same as standard calculators for easy learning. Dedicated keys give quick access to commonly used financial and statistical functions
- APPROVED FOR MAJOR EXAMS – The HP 10bII+ algebra calculator is permitted for use on SAT, PSAT/NMSQT, and AP tests. An ideal statistics calculator and business calculator for school finance and accounting students preparing for class, coursework, or standardized exams.
- INCLUDES TRAVEL CASE, CLEANING CLOTH & BATTERIES– Slim, durable, and easy to keep on hand or store in a backpack or locker. Includes a protective case, cleaning cloth, and batteries so it’s ready out of the box. Large screen with clear contrast (non-backlit) is easy to read during exams or lectures.
Loan amortization is different: the borrower makes a cash payment, and the principal portion reduces the debt balance while the interest portion is borrowing cost. Do not confuse loan interest with accounting amortization of an intangible asset.
Book accounting and U.S. tax rules are different
Book depreciation and amortization follow the relevant financial-reporting framework and estimates; tax deductions follow tax law. For U.S. federal taxes, the IRS explains that qualifying property may be depreciated under rules that specify basis, recovery periods, methods, and conventions. Tax depreciation therefore may differ from book depreciation.
Recommended Free Tools
Qualifying Section 197 intangible assets generally are amortized for U.S. tax purposes over 15 years, or 180 months, under the IRS rules. This is a tax rule for qualifying assets, not a general rule that all intangible assets are amortized over 15 years. Financial-reporting amortization may instead follow the asset’s estimated useful life and applicable accounting standards.
Rank #4

- Solves time-value-of-money calculations such as annuities, mortgages, leases, savings, and more
- Performs cash-flow analysis for up to 32 uneven cash flows with up to 4-digit frequencies
- Calculates various financial functions: Net Future Value Net present Value Modified Internal Rate of Return Internal Rate of Return Modified Duration Payback Discounted Payback
- The Texas Instruments BAII Plus Professional features an Automatic Power Down (APD) function for extended battery life
- Prompted display guides you through financial calculations showing current variable and label. Ten-digit display
Which term applies to your situation?
- If you are allocating the cost of a physical long-lived asset, the relevant term is usually depreciation.
- If you are allocating the cost of a finite-lived intangible asset in financial statements, the relevant term is usually asset amortization.
- If you are looking at scheduled payments on a mortgage, auto loan, or installment loan, loan amortization describes how payments reduce debt and cover interest.
- For a tax return or financial statement, check the applicable rules and facts rather than assuming book and tax treatment match.
FAQ
Is amortization the same as depreciation?
They are both ways to allocate an asset’s cost over time, but depreciation generally applies to tangible assets and accounting amortization to finite-lived intangible assets. Loan amortization is a separate use of the term for scheduled debt repayment.
Does depreciation mean an asset has lost market value?
No. Depreciation allocates an asset’s cost for accounting or tax purposes; it does not directly measure its current resale price. An asset’s market value can move differently from its carrying amount.
Does a mortgage payment reduce principal by the full amount?
No. Part of the principal-and-interest payment covers interest, and the principal portion reduces the balance. Escrowed taxes and insurance may be included in the total payment but do not pay down principal.
Best Value

- Brand New in box; The product ships with all relevant accessories
- Dedicated keys allow easy access to common financial and statistics functions
- Easy-to-use design provides business, finance and statistical calculations fast
- Specially designed to meet the mathematical needs
Are depreciation and asset amortization cash expenses?
The periodic accounting expenses generally are noncash in the period recorded, although acquiring the asset may have required cash or financing. Loan payments, by contrast, are cash payments.
Are all intangible assets amortized over 15 years?
No. The 15-year period applies to qualifying Section 197 intangibles for U.S. federal tax purposes. Financial-reporting treatment depends on the asset’s useful life and applicable accounting framework; indefinite-lived assets are generally treated differently.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




